Available 7 Days/Week       MON - FRI  8am - 7pm       SAT - SUN  10am – 6pm
Call us (407) 955-4575
Apply Now

Tag: #floridamortgagerates

What Higher Mortgage Rates Mean for Home Sellers
What Higher Mortgage Rates Mean for Home Sellers Simplifying The Market

Higher mortgage rates don’t just affect buyers. They can change what it takes to sell your house, too.

That’s because today’s buyers are paying close attention to affordability. And when rates rise, even a relatively small change can make a noticeable difference in their monthly payment. So, they’re looking for ways to make the numbers work. And in some markets, new construction is giving them exactly that.

If you’re planning to sell, that doesn’t mean you can’t compete. But it does mean you need to understand what builders are doing to win over buyers – and what options you have, too.

Builders Are Competing on the Monthly Payment

New construction has something interesting going for it right now. While existing-home sales  (homes that have previously been lived in) continue to struggle under the weight of higher mortgage rates, new-home sales are holding up a bit better.

In a recent interview, Logan Mohtashami, Chief Economist at HousingWire explains new-home sales are at an 8-month high and are now running around 2019 levels. On the flip side, existing home sales are lagging behind and fall about 1 million home sales short of 2019 levels.

One big reason builders have been able to navigate higher rates differently is incentives. According to Realtor.com, nearly 1 in 5 (18.8%) newly built homes come with some kind of buyer incentive advertised up front:
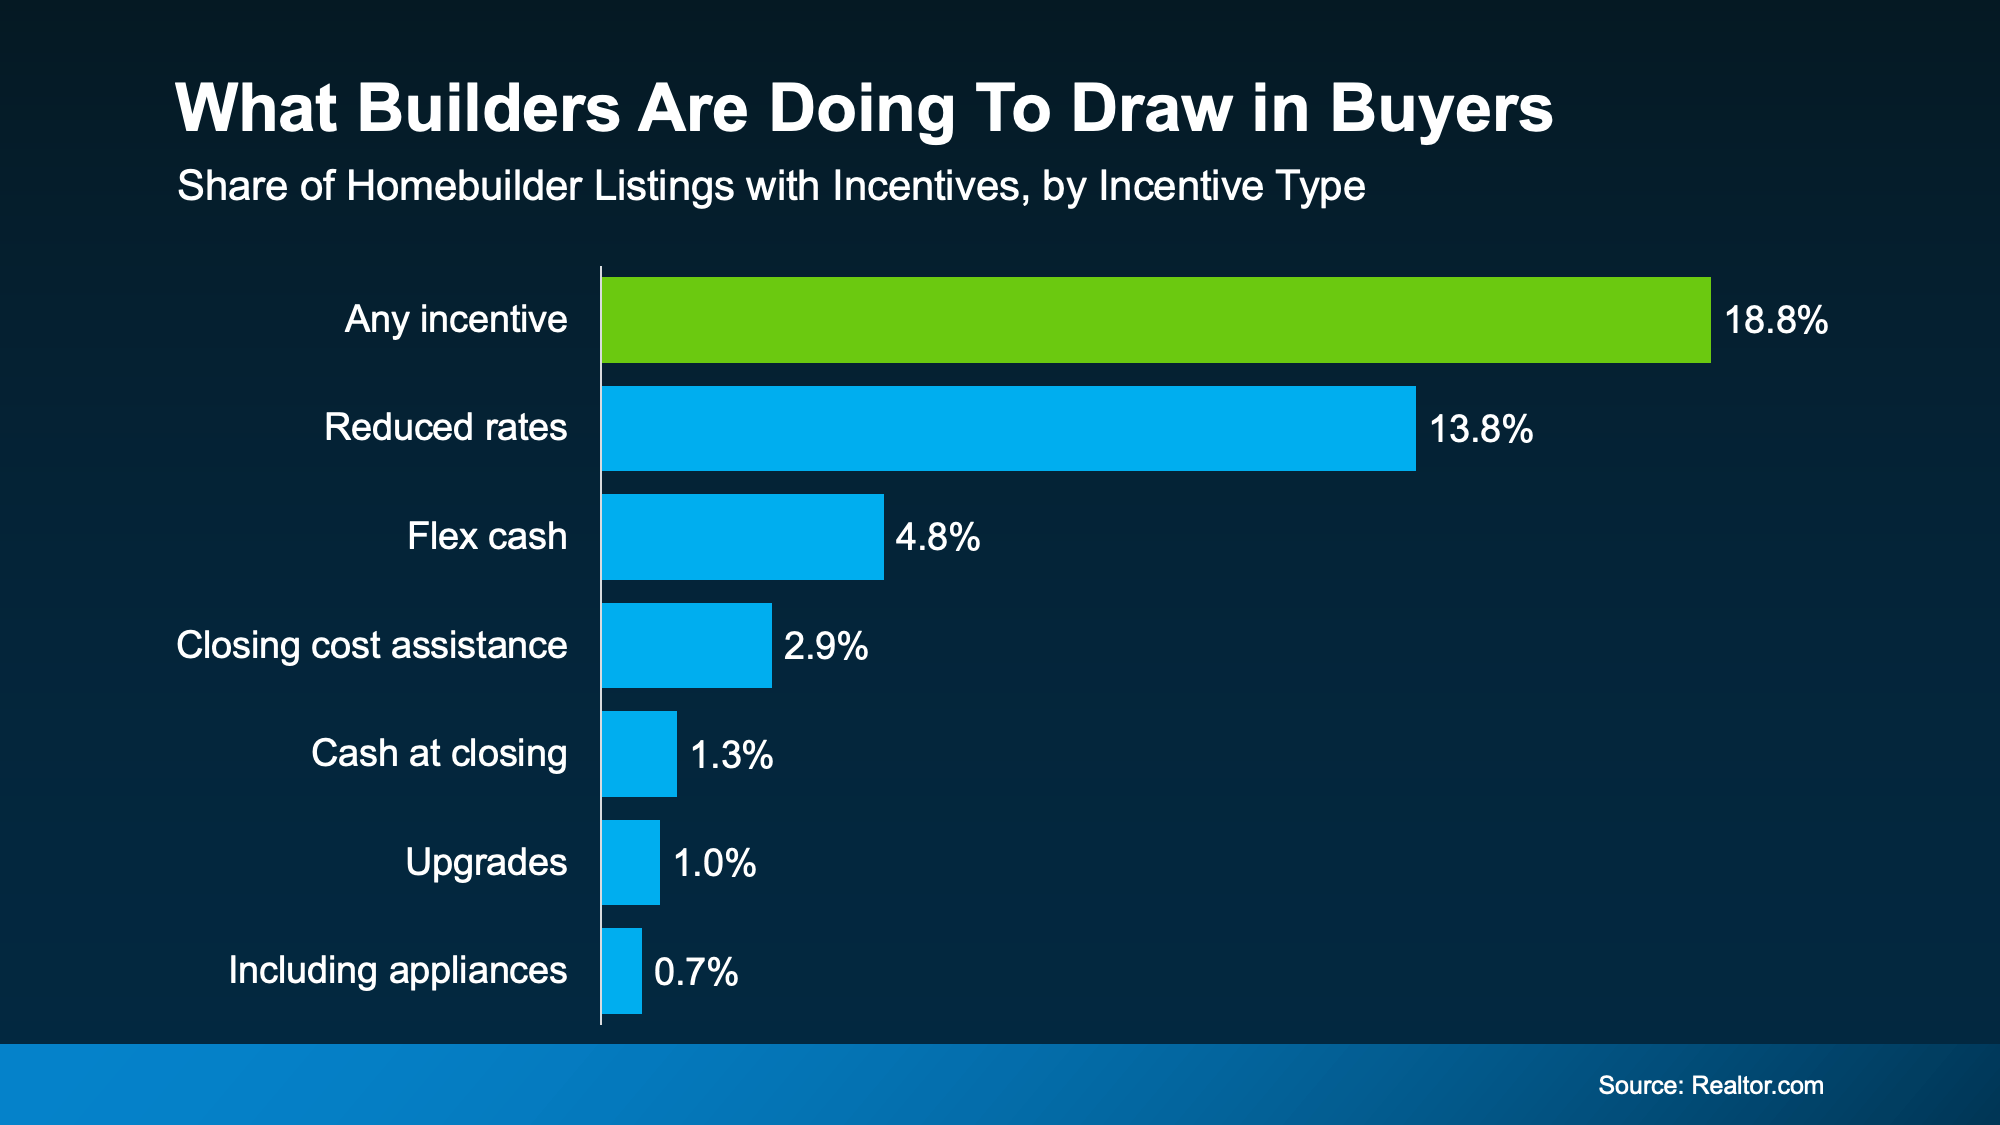
a graph of a company's sales

The most common may surprise you. As the graph shows, many builders are offering reduced rates, sometimes through something called a mortgage rate buydown.

It’s essentially where they pay upfront costs to help buyers get a lower rate, and by extension, a lower monthly payment. It has obvious draws for buyers. For homebuilders, it helps them get their houses sold. So, a lot of builders see it as a win-win. That’s why reduced rates are a part of 13.8% of new home listings.

In some cases, builders are offering rates below 6%, maybe even far below 6%. And that can help buyers shave hundreds off their monthly payment. That’s a big difference to a buyer who are feeling the pinch right now.

So, How Can Sellers Like You Compete?

First, don’t assume a mortgage rate buydown is something only a builder can offer. Sellers can contribute toward a buyer’s rate buydown too, depending on the loan and transaction. Does that mean you should offer one? Or that you have to if you want to compete? Not necessarily.

A buydown is just one possible lever. Depending on your market and the buyer, it may make more sense to negotiate on price, contribute toward your buyer’s closing costs, make repairs, or make sure your house stands out in ways a new build can’t. That’s why working with an agent who knows your local competition matters. Joel Berner, Senior Economist at Realtor.com, says:

“Sellers of existing homes are facing a lot of competition from the new-home space. . . so sellers should highlight the local amenities of their neighborhoods in contrast to the more suburban or exurban communities where many new homes are built.”

A great agent will do this naturally anyways. Knowing what makes your house different and showcasing that in your listing can help your house stand out. And remember, being open to making a few compromises or throwing in some concessions can make a bigger difference for buyers than you may think.

Today’s Market Rewards Sellers Who Adapt

Builders have also been quicker to adjust their prices based on what buyers can actually afford and where demand is. That’s putting pressure on the resale market in some areas. Robert Dietz, Chief Economist at the National Association of Home Builders (NAHB), explains:

“. . . existing homeowners now have to do the price discovery that builders have been doing since 2022.”

That’s an important message if you’re hoping to sell.

You don’t automatically need to slash your price or offer a big concession. But you do need to price and market your house based on what buyers can pay today – not what sellers could get a few years ago.

And remember, this varies tremendously by location. New construction represents a much bigger share of the competition in some markets than others, and builder incentives aren’t equally common everywhere. So, lean on an agent to see how big of a factor builders are in your area.

Bottom Line

Higher mortgage rates are making buyers more cost-conscious. Builders know that, and many are responding with rate buydowns, closing-cost help, price reductions, and other incentives.

If you’re thinking about selling, talk to an agent about what buyers are getting from other homes in your area – including new construction – so you can make sure your house is positioned to compete.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
An FHA mortgage could make homeownership more accessible than you think. FHA loans are popular with first-time and repeat homebuyers because they may offer: ? Down payments as low down payment

An FHA mortgage could make homeownership more accessible than you think. FHA loans are popular with first-time and repeat homebuyers because they may offer: ? Down payments as low down payment ? original sound – Fidelity Home Group® – undefined

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, floridamortgagecalculator

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In.

Hoping for (or Dreading) a Housing Crash? The Experts Just Weighed In. Simplifying The Market

Half the buyers out there are scared home prices are about to crash. The other half are hoping they will.

A recent survey from Clever found 58% of Gen Z buyers are actually rooting for a crash, just so homeownership feels within reach.

So, what do the forecasts actually say?

Every quarter, Fannie Mae surveys more than 100 housing experts on where prices are headed. The newest results are in. And spoiler alert: they’re not calling for a crash – not even the pessimists.

What the Newest Numbers Actually Say

The panel’s latest forecast has prices climbing every single year through at least 2030.

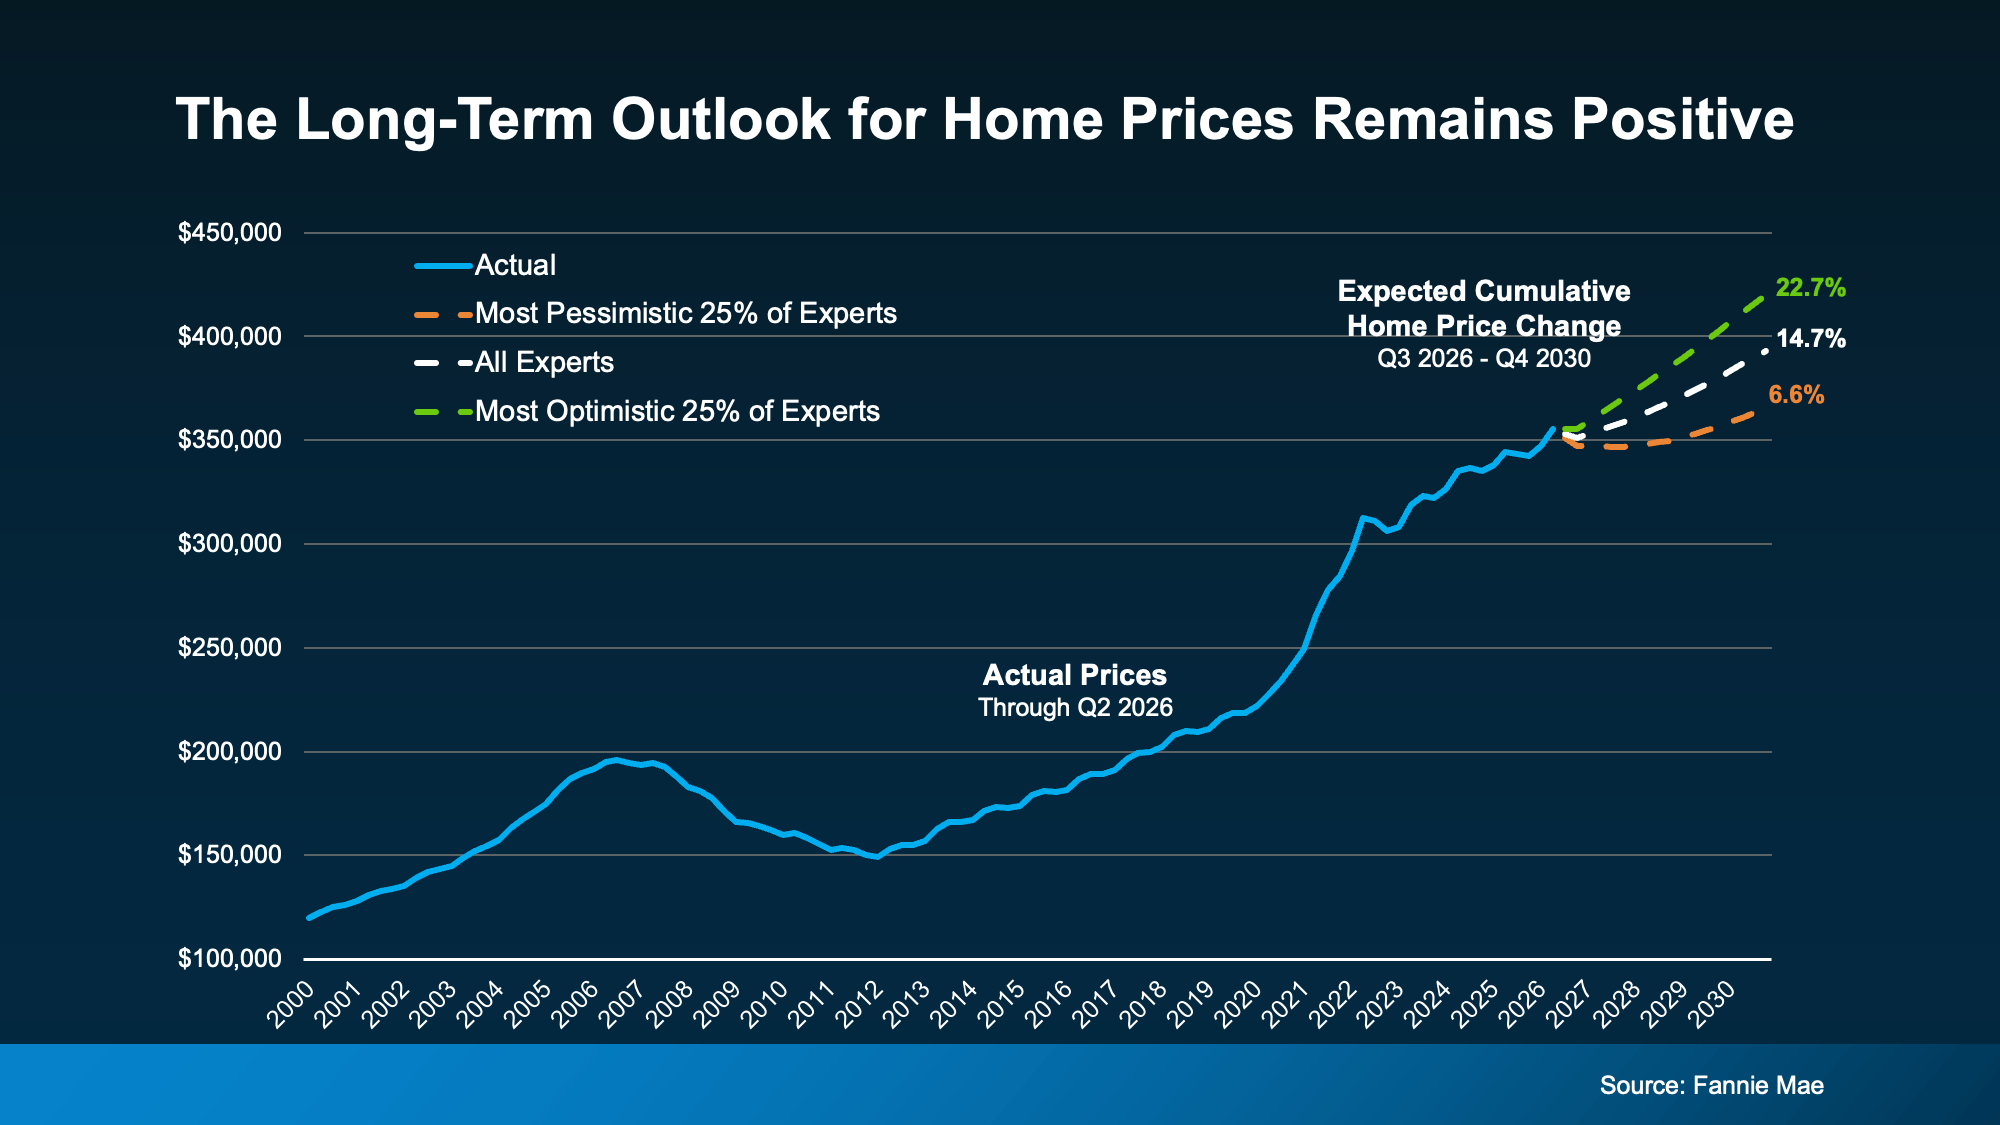
The panel’s average forecast is that prices will rise by 14.7% in the next 5 years. And here’s where it gets really interesting. If you split these experts into optimists and pessimists, even the pessimists still expect prices to increase about 6.6% by the end of 2030 (see graph below):

a graph showing the price of a home

The takeaway? If you’ve been waiting for prices to fall, you may be waiting a while.

One thing to keep in mind though – these are national numbers. Prices in your area could run a little hotter or a little cooler than this, so it helps to know what’s happening locally, too. But the big picture is prices aren’t crashing. Historically prices usually rise.

How This Quarter Compares to the Past

Here’s something you probably don’t realize. This survey runs 4 times every year, so you can track the panel’s mood over time.

A year ago, the panel expected home prices to grow 2.1% this year. Now they’re forecasting 2.5%. That means the near-term outlook actually got more optimistic. But that’s only part of the story. The years after that shifted, too (see graph below):

a graph of growth in a graph

Zoom out to 2027 through 2029 and the mood has cooled a bit. Each of those years is now expected to see a little less growth than the panel thought a year ago. That’s likely a reflection of where we are right now with everything that’s impacting the housing market.

But again, the overall takeaway here is every bar shows an increase in prices – the size of that increase has just moderated due to some of the factors at play.

A slower climb isn’t a bad thing, though. It’s a sign the market is settling into a more normal pace after a few wild years.

A little more growth here, a little less growth there. What hasn’t budged once is the idea that home prices will keep growing.

What It Means for Your Next Move

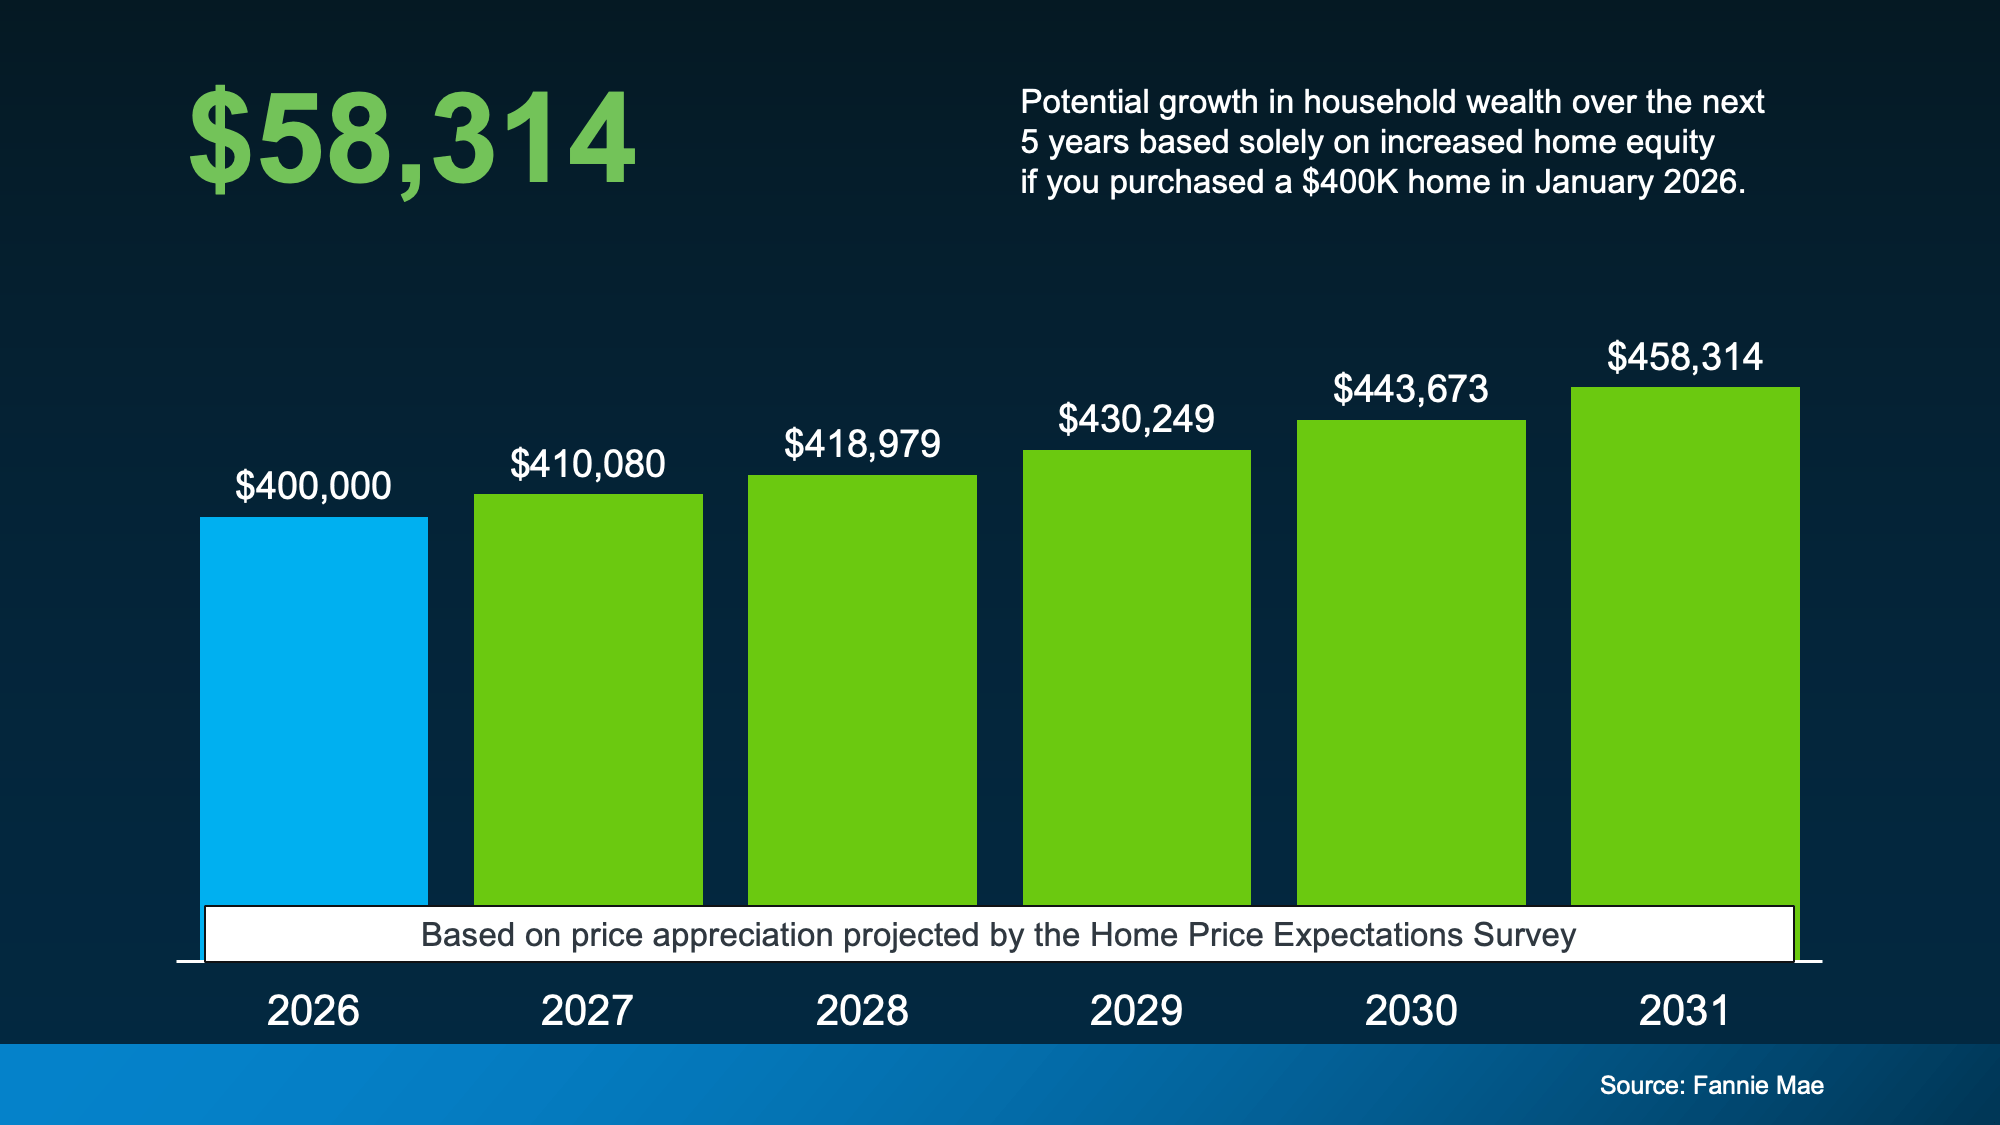
Now, percentages are great, but you probably care more about the actual dollars and cents of your move, so let’s graph that out, too.

Run the numbers on a $400,000 home bought in January, and the panel’s latest forecast puts you up about $58,000 in equity in 5 years just from price growth (see graph below):

a graph of growth in a number of green squares

That’s real wealth you could be building while others sit on the sidelines, waiting for a crash the experts don’t see coming. And with prices expected to keep rising, waiting could mean paying more for the same home later.

Bottom Line

Whether you’re bracing for a crash or hoping for one, the verdict is the same – prices are still expected to rise, not fall. Talk with a local real estate agent about what that means for your market and your plans.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get.

The Mortgage Rate You See Online Isn’t Necessarily the One You’d Get. Simplifying The Market

You may have seen the headlines saying mortgage rates have climbed to the highest point since January 2025. And if that’s left you reluctant to buy a home, here’s what you need to remember… 

That’s not necessarily the number you’d get. 

It’s a common misconception that the rate you see in the headlines is the same one you’d get when you buy. The truth is, mortgage rates shift often, and the rate you actually end up with can vary a lot from what you may see or hear about. 

What Determines Your Real Rate? 

Advertised rates and “real rates” aren’t always the same. That’s because real rates are based on your specific situation, which includes your overall finances and goals. The rates you see in the headlines can’t possibly reflect that. 

That’s why only a lender can tell you what your real rate will be. To figure out your unique number, they’ll look at:

  • Your credit score: Your credit score includes your payment history (if you’ve made late payments – and how often), credit utilization (are your accounts maxed out, or do you have available credit?), and the length of your credit history (how long have your accounts been open?). For example, someone with an exceptional credit score may qualify for a better rate.

  • Your debt-to-income ratio (DTI): This is calculated by dividing your monthly debt payments by your monthly income before taxes to come up with a percentage. The higher your DTI, the higher your rate could be.

  • The down payment size and Loan-to-Value (LTV): Your down payment is the percentage of the home’s price you will put down. The LTV is the percentage of a home’s sales price that equals your mortgage. 

  • The type and term of loan program options: Your loan officer will walk you through different loan options based on what you qualify for. Mortgage rates can vary between different loan products and programs. 

Even after you find a home you love, other things can have an impact too. For example:

  • A mortgage rate buydown: This helps you get a lower mortgage rate, and by extension, a lower monthly payment, by paying an upfront cost. Sometimes a seller, builder, or another party may even offer to cover that cost themselves as an incentive for you to buy.

  • Seller concessions: Sellers are allowed to pay buyer closing costs according to most loan program guidelines. Seller-paid closing costs can add up to thousands of dollars, which can free up some cash for you to increase your down payment, pay down debt, or make other financial adjustments to try to get a better rate. 

There’s a lot that can ultimately have an impact on your actual rate. 

Your First Step? Getting Pre-Approved.

If you want to know if your number could be higher or lower than the headlines on social, you need to talk to an expert. A simple conversation with a loan officer can help you determine when you’ll be ready to buy, how much you can borrow, and of course, what your real rate will be. 

Your lender may recommend a pre-qualification and pre-approval:

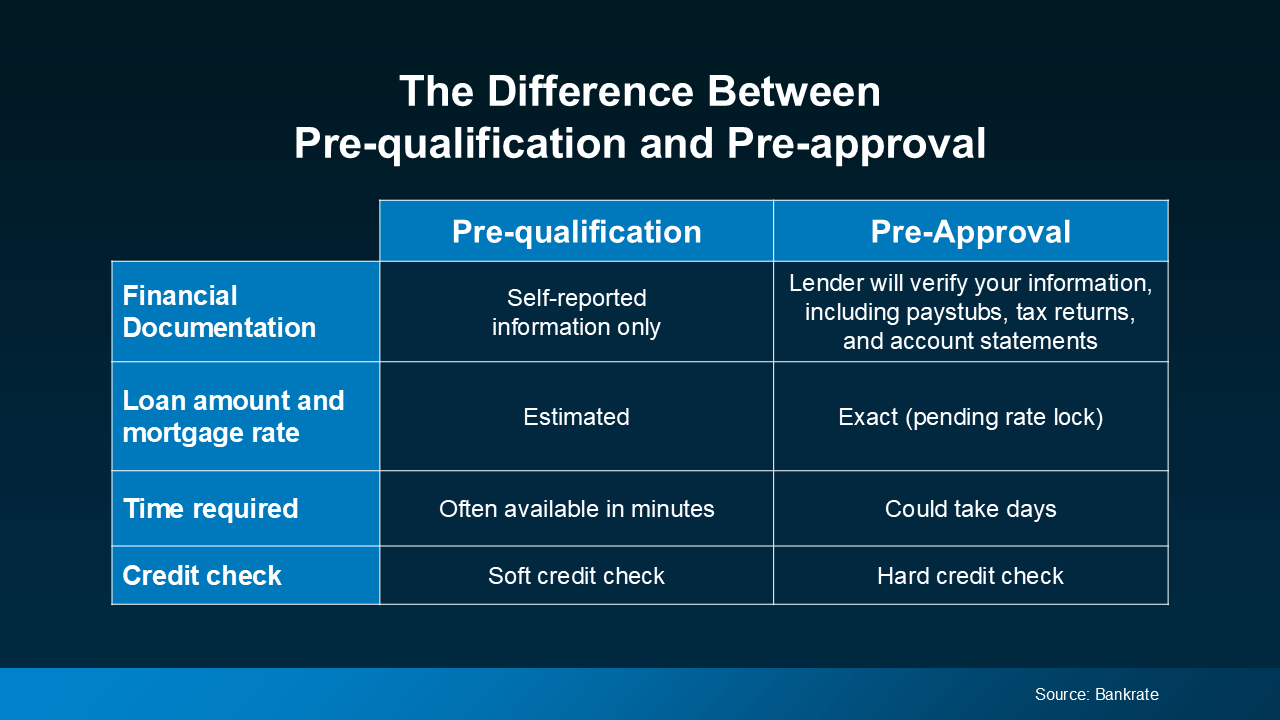
  • Pre-qualification is a general estimate of what you might be able to borrow based on self-reported information. 

  • On the flip side, pre-approval is actually a conditional commitment from a lender based on verified information. 

Just know that, of the two, the pre-approval process gives you a more accurate picture of your options than pre-qualification. Bankrate gives a quick comparison so you can see why:

a blue and white chart with white text

How To Get Ready for the Conversation

Ask your lender what documents you’ll need to gather for that conversation. And keep these questions in your pocket too. They’re good things to go over when you talk: 

  • What will I gain or lose by waiting to buy a home for 3, 6, or 12 months? 

  • Will I get any tax advantages by buying a home – and what are they? 

  • What’s the benefit of buying a home and starting to build equity now versus waiting? And how does that impact my finances in the long run?

  • How will rate changes in either direction affect me?

Once you find out your rate, maybe you can buy now. Or maybe you still need to wait. But at least you’d know your options and can make an informed decision.  

Bottom Line

Headlines and social media make today’s rates sound high. But you have to remember, the rate you’re seeing online and your actual rate could be different. The only way to know what your rate could be is to talk to a trusted lender. 

With the right help, you can find out what your real rate is – and where it can take you.


#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
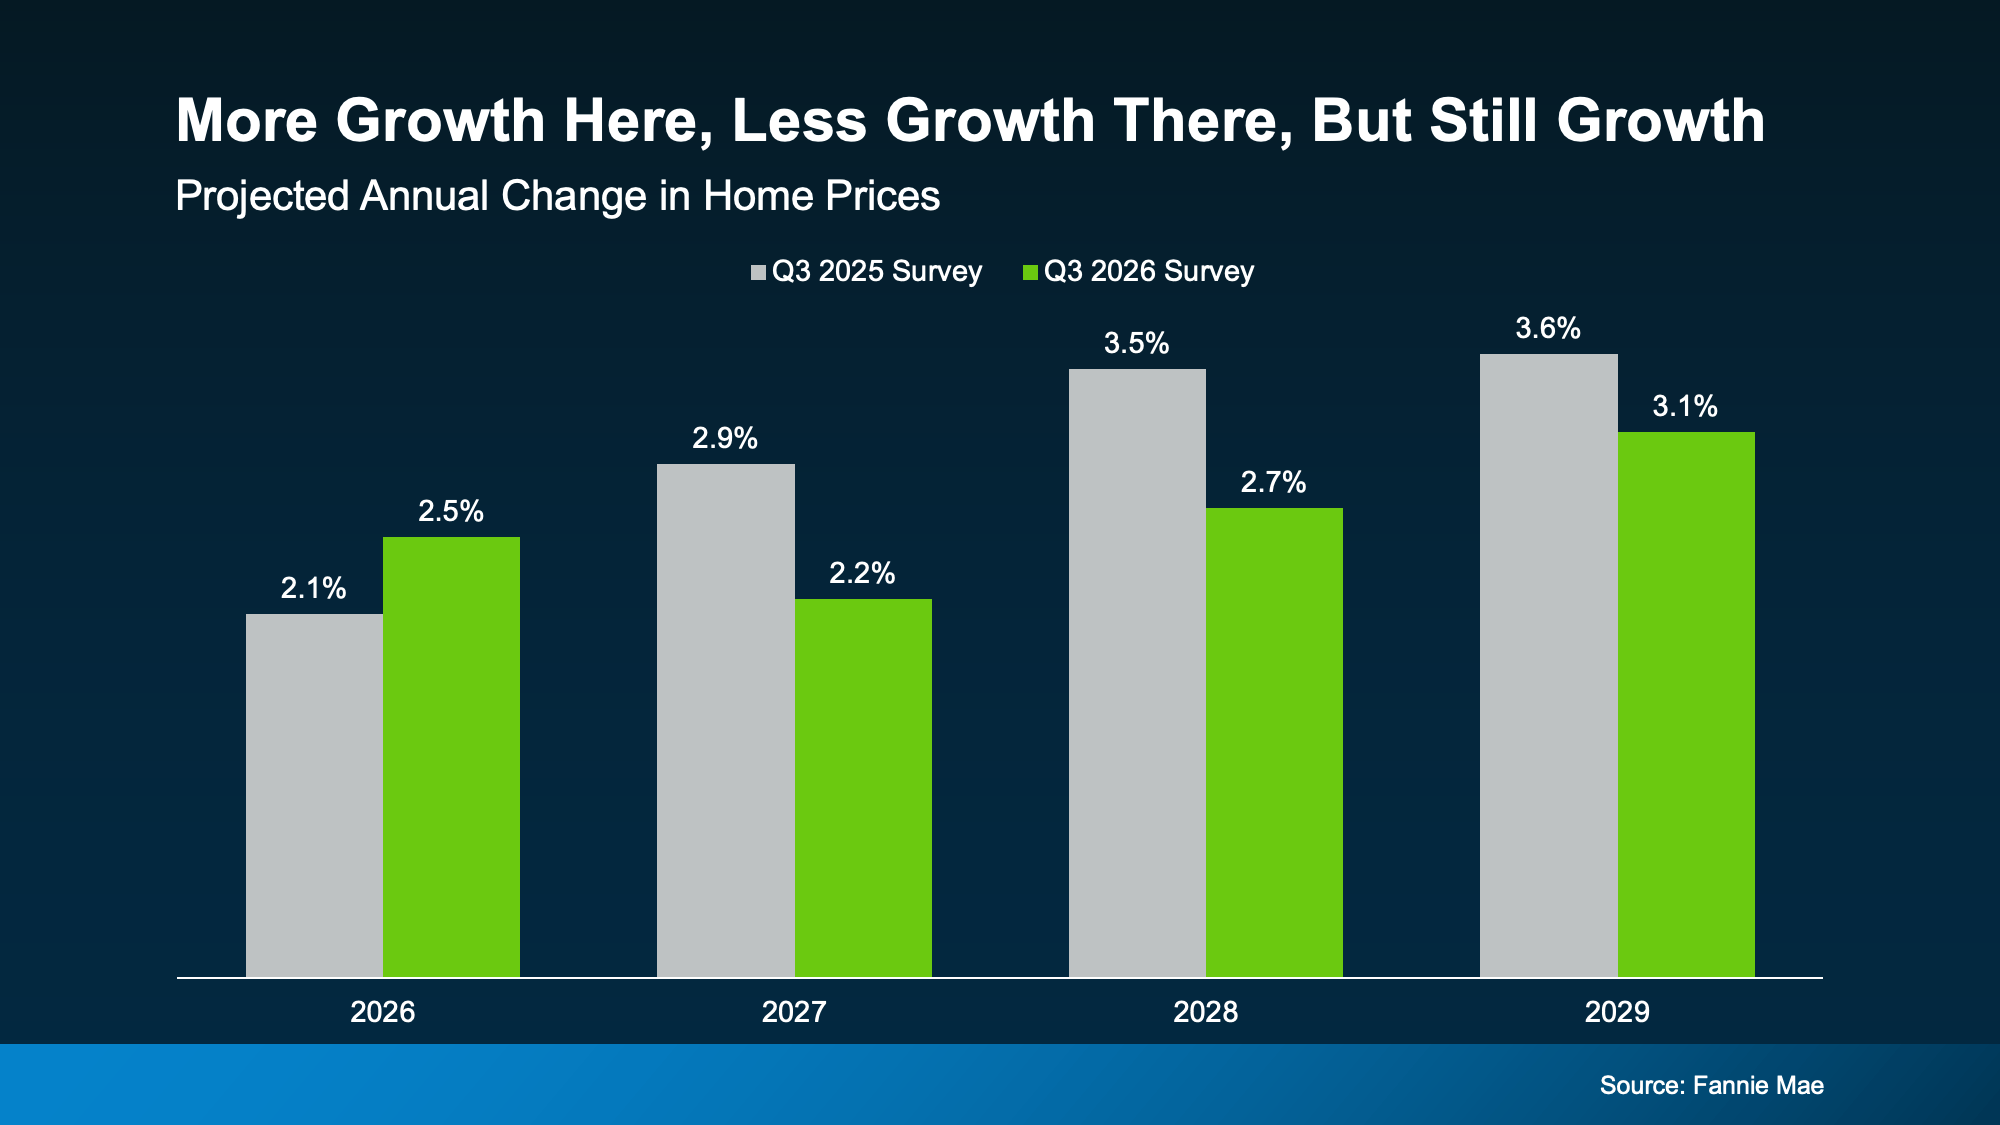
Your dream Florida condo just got flagged by every major lender. Here is who actually says yes. A non-warrantable condo is a unit or project that does not meet Fannie Mae and Freddie Mac eligibility criteria. When that happens, most lenders walk away and treat the deal as too high risk. A condo can be labeled non-warrantable for reasons like: New construction still selling out Owners lacking control over the HOA An underinsured master insurance policy Low HOA reserves A high percentage of non-owner-occupied units Short-term rentals allowed in the building A single entity owning more than 10% of the units Ongoing litigation involving the owner or developer Any one of these can stop a standard

Your dream Florida condo just got flagged by every major lender. Here is who actually says yes. A non-warrantable condo is a unit or project that does not meet Fannie Mae and Freddie Mac eligibility criteria. When that happens, most lenders walk away and treat the deal as too high risk. A condo can be labeled non-warrantable for reasons like: New construction still selling out Owners lacking control over the HOA An underinsured master insurance policy Low HOA reserves A high percentage of non-owner-occupied units Short-term rentals allowed in the building A single entity owning more than 10% of the units Ongoing litigation involving the owner or developer Any one of these can stop a standard mortgage cold. That does not mean the condo is unfinanceable. It means you need a lender who works these files every day. That is what we do. Non-warrantable condo loans are hard to find in Florida because most lenders do not offer them. We do, and we know how to turn a flagged unit into a closed loan. Have a condo that traditional lenders rejected? Call us 7 days a week at 407-955-4575. ? Link in bio ? original sound – Fidelity Home Group® – undefined

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, floridamortgagecalculator

Fidelity Home Group | Down Payment for a Conventional Loan

Do You Know the Minimum Down Payment for a Conventional Home Loan? NMLS ID 1834853 #conventionalloans #fidelityhomegroup #floridamortgage #floridamortgagerates #floridamortgagecompany #mortgagetips

#fidelityhomegroup, #floridamortgage, #floridamortgagerates

Why So Many Sellers Are Cutting Their Price Right Now

Why So Many Sellers Are Cutting Their Price Right Now Simplifying The Market

Price cuts are turning up everywhere right now, and they read very differently depending on which side of the deal you’re on.

Sellers tend to worry a cut means walking away with less than they hoped. Sometimes that’s true, but more often it just means the market moved faster than the listing did.

Buyers, for their part, often assume a cut means something’s wrong with the house. Most of the time, that’s not it.

This is what’s actually driving all those price cuts, and why it matters no matter which side of the deal you’re on.

42% of Homes for Sale Are Now Carrying a Price Cut

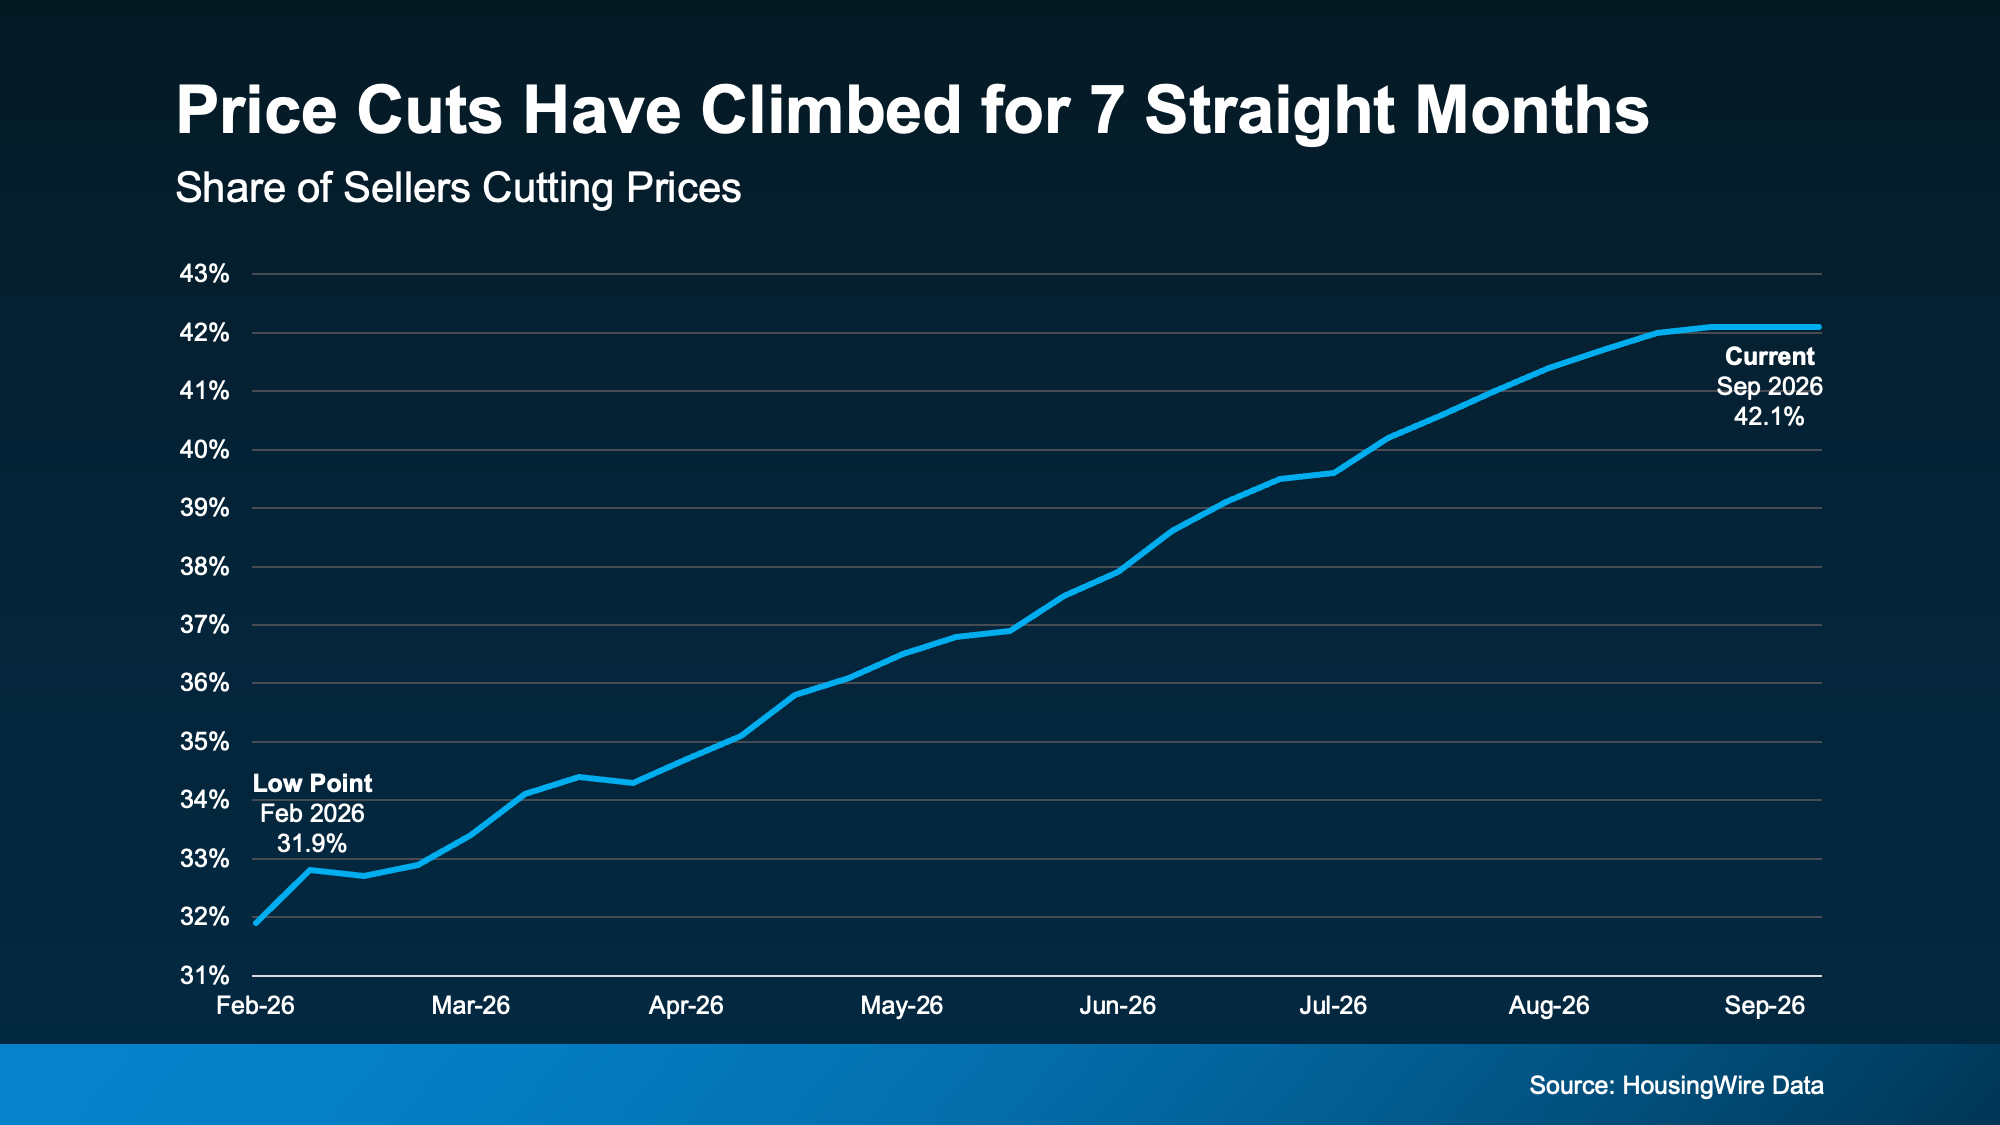
According to HousingWire Data, the share of sellers cutting their asking price has climbed every month for 7 straight months (see chart below):

a graph showing the growth of a straight month 

Today, more than 4 in 10 active listings have had at least 1 price cut, and the typical seller is cutting about $17,560 off their original number. 

Here’s why that’s happening. With rates still elevated and more homes to choose from, buyers can afford to wait for the right number. So, sellers who don’t start there often end up adjusting anyway.

What does that mean for you?

  • If you’re selling, this isn’t a red flag. But it is a sign that pricing it right from day 1 is your best bet. Just know that the market’s been shifting fast enough this year that sometimes even a well-priced house can fall behind within a matter of weeks. If that happens to you, dropping your price to catch up to where pricing actually stands today tends to bring in more buyers and helps you sell closer to true market value.

  • If you’re buying, it’s easy to assume a price cut means something’s wrong with the house. But with cuts happening on more than 4 in 10 homes right now, the reality is sellers are just catching up to where the market already is. And with affordability still tight, that’s exactly the kind of opening you need to get a better deal.

Why Sellers Are Adjusting Faster than Before

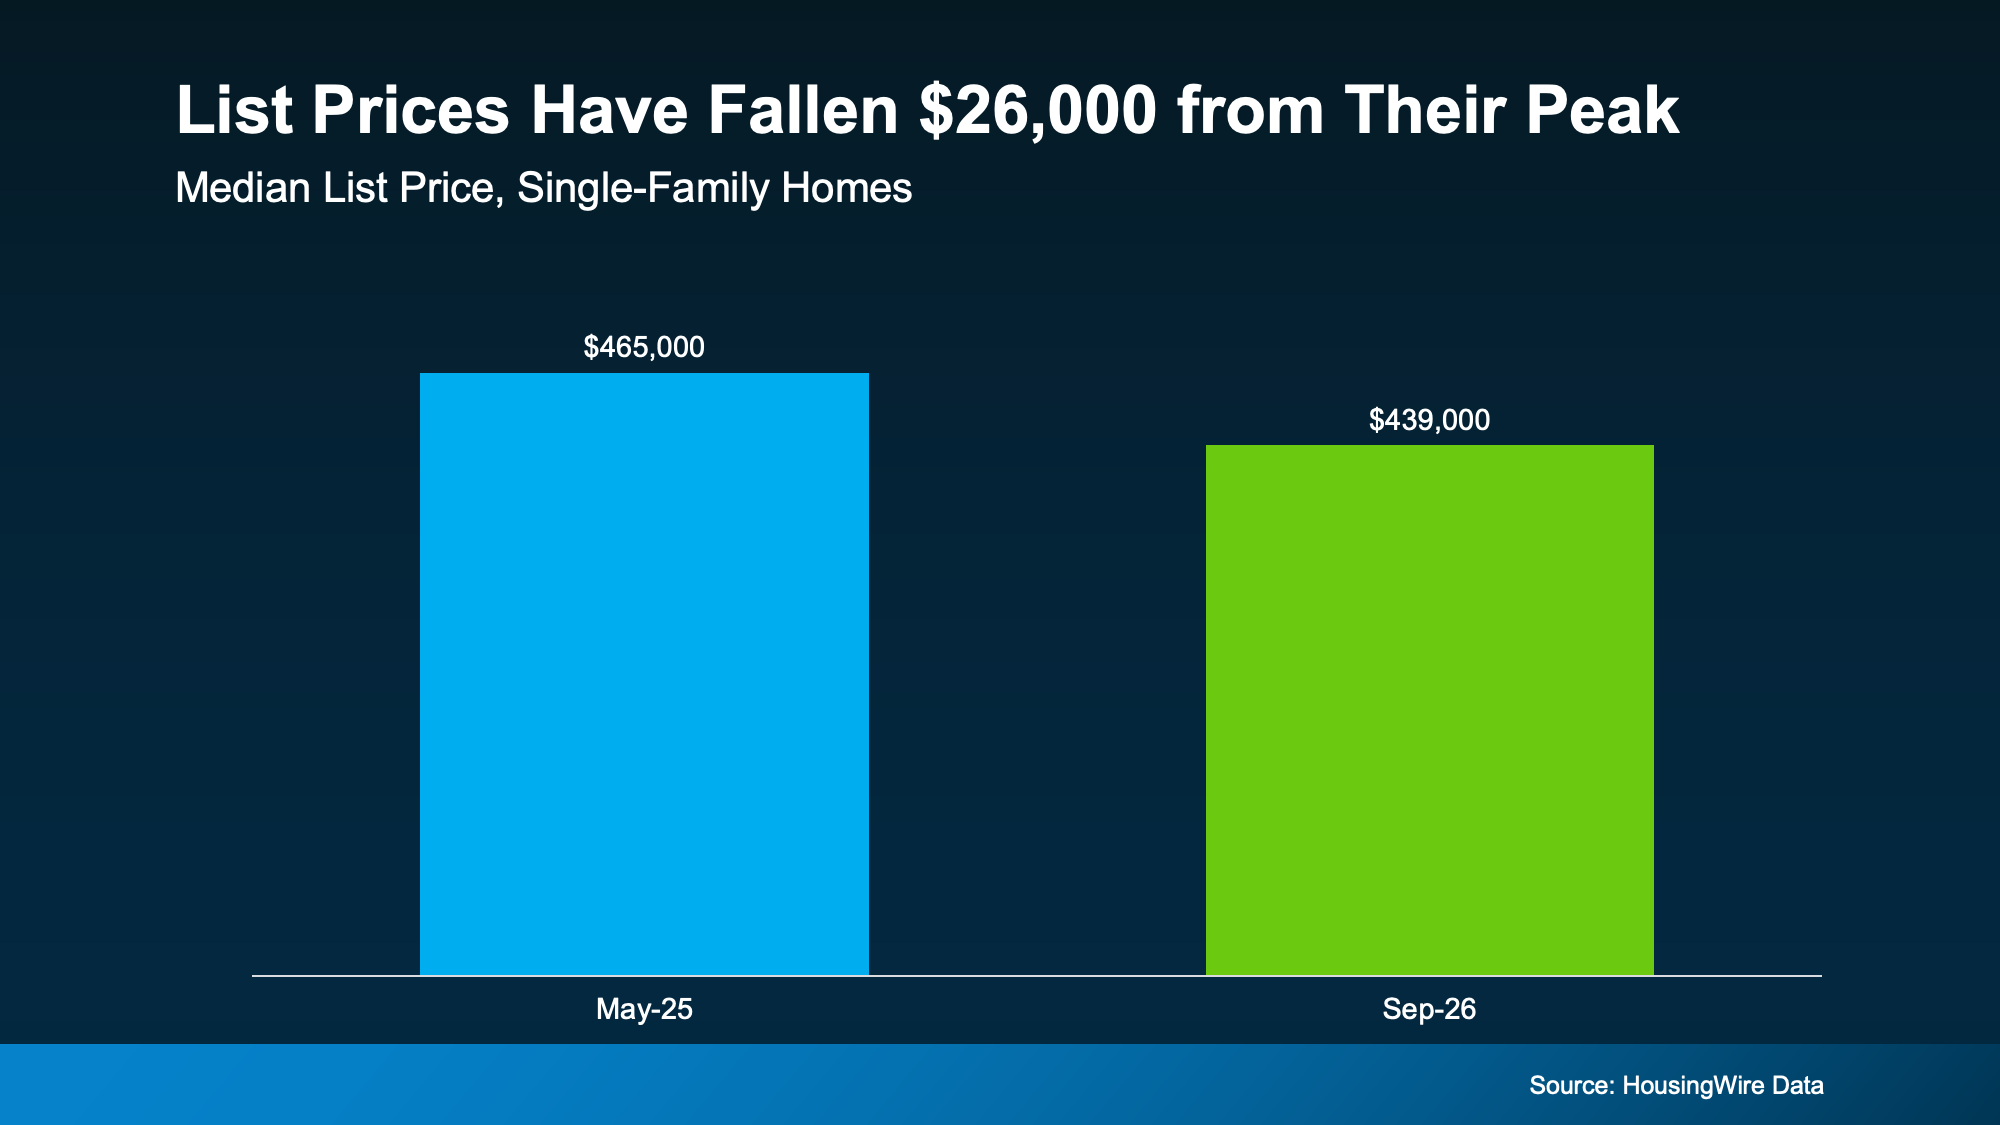
HousingWire Data also shows list prices are trending down nationally. That’s often a sign sellers are pricing more realistically from the start instead of listing high and getting stuck cutting later. List prices have fallen about $26,000 from last year’s peak.

Some of that decline is seasonal, since list prices typically soften each winter before rebounding in the spring. So, expect asking prices to keep drifting a little lower before turning back around (see chart below):

a graph of a number of people 

Jake Krimmel, Senior Economist at Realtor.com, explains: 

“That is good news for buyers, who are seeing lower asking prices and more room to negotiate, but it is also good news for sellers: Pricing to today’s demand is helping homes move and keeping more transactions alive in a high-rate environment.”

Translation – with rates still elevated, buyers can only stretch so far. Sellers who meet them where they are instead of holding out for unrealistic prices are the ones actually getting to closing. And doing that up front is always better than chasing the market later.

Buyers, You’ve Got Room To Negotiate Again

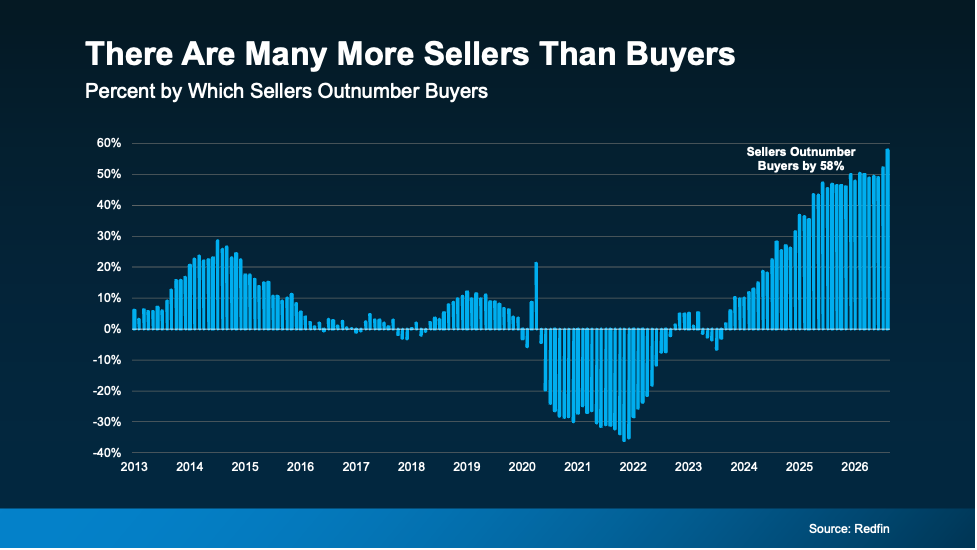
At the same time, Redfin data shows sellers now outnumber buyers by about 58%, the widest gap on record (see chart below):

a graph of sales 

That changes the power dynamics of the market – and impacts how homeowners should price their house. Nationally, about 7 in 10 markets now favor buyers or are trending that way.

  • For sellers, that means standing out matters as much as pricing. With more homes to choose from, buyers are comparing you directly against the competition. So, a little flexibility, like covering closing costs or being open on timing, can be what gets your house picked over another.

  • For buyers, it means more room to ask for a lower price, help with closing costs, repairs after inspection, or some combination of all 3. That’s especially true for homes that have already sat for weeks, where sellers are often the most willing to talk.

Bottom Line

Price cuts are a normal part of today’s housing market, and both buyers and sellers can use them to their advantage. Connect with a local real estate agent to look at what’s actually happening with prices in your neighborhood, so you know exactly where you stand before you list or make an offer.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Your Florida condo might qualify for conventional financing, but only if it clears five specific hurdles. A condo is considered “warrantable” when it meets the conventional guidelines set by Fannie Mae and Freddie Mac. That matters because it’s what makes your unit eligible for a conventional mortgage, which usually means better terms and more buying power for you. Here’s what “warrantable” generally comes down to: No single entity, including the developer, owns more than 10% of the units in the project. At least 51% of the units are owner-occupied. Fewer than 15% of the units are behind on their association dues. There is no ongoing litigation involving the homeowner’s association (HOA). Co

Your Florida condo might qualify for conventional financing, but only if it clears five specific hurdles. A condo is considered “warrantable” when it meets the conventional guidelines set by Fannie Mae and Freddie Mac. That matters because it’s what makes your unit eligible for a conventional mortgage, which usually means better terms and more buying power for you. Here’s what “warrantable” generally comes down to: No single entity, including the developer, owns more than 10% of the units in the project. At least 51% of the units are owner-occupied. Fewer than 15% of the units are behind on their association dues. There is no ongoing litigation involving the homeowner’s association (HOA). Commercial space makes up no more than 25% of the total building square footage. If your development clears those, the financing side gets a lot friendlier. Warrantable condo highlights include a minimum credit score of 620, down payments as low as 3%, and debt-to-income ratios under 50%. Not sure where your condo development stands? We finance warrantable, non-warrantable, and condotel properties, and our Mortgage Experts can check whether your building is currently approved for a conventional mortgage. Call us 7 days a week at 386-456-6380. ? original sound – Fidelity Home Group® – undefined

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, floridamortgagecalculator

You qualify. The building might not. Here is what most condo buyers never see coming. Most condo buyers walk in confident. Credit is solid, income checks out, down payment is ready. What catches them off guard is learning the building itself has to qualify too. Condos carry a financing layer most borrowers never see coming: the association’s finances, the owner-occupancy ratio, the project’s legal structure. A buyer who qualifies perfectly on paper can still hit a hard stop. Condotels and non-warrantable condos follow entirely different financing rules. Loans up to $2 million exist for these property types, but only through lenders who carry the specialized products built for them. Working w

You qualify. The building might not. Here is what most condo buyers never see coming. Most condo buyers walk in confident. Credit is solid, income checks out, down payment is ready. What catches them off guard is learning the building itself has to qualify too. Condos carry a financing layer most borrowers never see coming: the association’s finances, the owner-occupancy ratio, the project’s legal structure. A buyer who qualifies perfectly on paper can still hit a hard stop. Condotels and non-warrantable condos follow entirely different financing rules. Loans up to $2 million exist for these property types, but only through lenders who carry the specialized products built for them. Working with a lender who handles both conventional and specialized condo products means the diagnosis happens early, before you are deep into a deal you cannot close. Buying a condo in Florida? Get the diagnosis before you get the surprise. Call us 7 days a week at 407-955-4575 to find out which financing lane your building sits in. ? original sound – Fidelity Home Group® – undefined

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, floridamortgagecalculator

Fidelity Home Group | Stated Income Mortgage

Fidelity Home Group | Stated Income Mortgage Unable to show income on your W2’s, Pay Stubs or Tax Returns? Not an issue, our Stated Income Mortgage Program is designed to use your credit history and reserves to offset your income. NMLS ID 1834853 #fidelityhomegroup #floridamortgage #floridamortgagerates #floridamortgagecompany #mortgagetips

#fidelityhomegroup, #floridamortgage, #floridamortgagerates