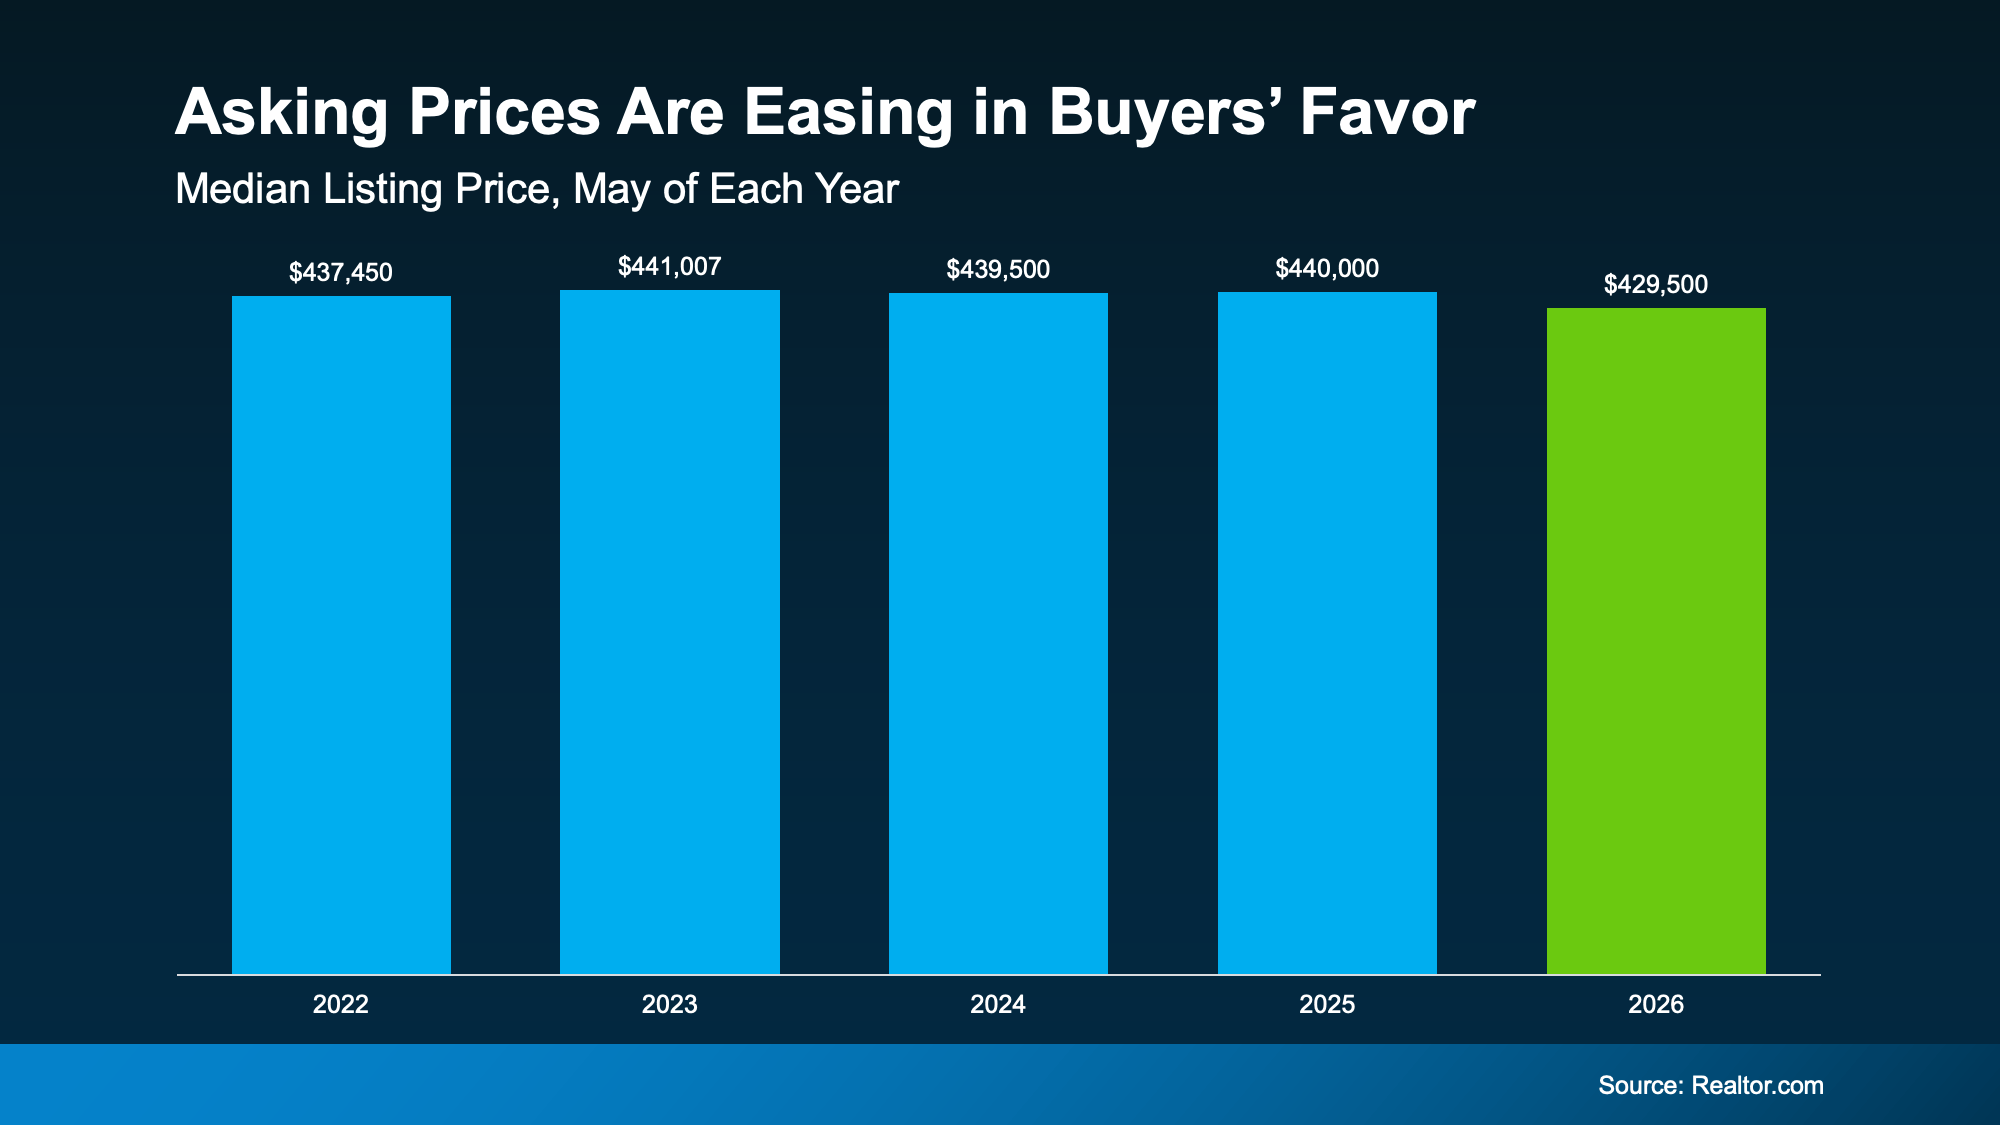
Available 7 Days/Week       MON - FRI  8am - 7pm       SAT - SUN  10am – 6pm
Call us (407) 955-4575
Apply Now

Category: Florida Mortgage Rates

Category Added in a WPeMatico Campaign

Start with our free home purchase qualifier or get a quick rate quote—no personal info needed. ? Here’s how an investor bought a Miami Beach condotel in 30 days. DSCR loans let you qualify based on rental income, perfect if you have business deductions. Minimum 660 credit score; down payments vary by condo type. Ready to invest smart? Get your rate today. ? Link in bio #DSCRloans #FloridaRealEstate #InvestmentProperty #CondotelFinancing #FidelityHomeGroup

Start with our free home purchase qualifier or get a quick rate quote—no personal info needed. ? Here’s how an investor bought a Miami Beach condotel in 30 days. DSCR loans let you qualify based on rental income, perfect if you have business deductions. Minimum 660 credit score; down payments vary by condo type. Ready to invest smart? Get your rate today. ? Link in bio #DSCRloans #FloridaRealEstate #InvestmentProperty #CondotelFinancing #FidelityHomeGroup ? original sound – Fidelity Home Group® – undefined

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, floridamortgagecalculator

Wondering if you qualify for a home purchase? Get your approval started quickly—no need to share personal info upfront. We help buyers and investors, including those with non-traditional income or interested in non-warrantable condos, find the right mortgage options. Start your homebuying journey with our easy qualifier tool today. ? Link in bio #HomeBuyers #InvestmentProperty #MortgageHelp

Wondering if you qualify for a home purchase? Get your approval started quickly—no need to share personal info upfront. We help buyers and investors, including those with non-traditional income or interested in non-warrantable condos, find the right mortgage options. Start your homebuying journey with our easy qualifier tool today. ? Link in bio #HomeBuyers #InvestmentProperty #MortgageHelp ? original sound – Fidelity Home Group® – undefined

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, floridamortgagecalculator

Try our home purchase qualifier or get a rate quote — see how investors overcome non-warrantable condo hurdles and no income docs scenarios swiftly. Ready for your next smart move? Let’s crunch the numbers. ? Link in bio #OrlandoRealEstate #MortgageSolutions #InvestmentProperties #CondoLoans #SmartHomebuying

Try our home purchase qualifier or get a rate quote — see how investors overcome non-warrantable condo hurdles and no income docs scenarios swiftly. Ready for your next smart move? Let’s crunch the numbers. ? Link in bio #OrlandoRealEstate #MortgageSolutions #InvestmentProperties #CondoLoans #SmartHomebuying ? original sound – Fidelity Home Group®

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, floridamortgagecalculator

Thinking about financing your next income property? The Short-Term Rental Loan program offers up to $6 million loans with options designed for flexibility. You can qualify with a minimum 680 FICO and use 12 or 24 months of bank statements instead of W-2s or tax returns. Loan types include adjustable-rate and 30-year fixed for purchases and refinances, including cash out and debt consolidation. Eligible properties range from single-family homes to non-warrantable condos and condotels, as long as condo units have kitchens and HOAs don’t restrict rental days or have ongoing litigation. Loans can close in the name of an LLC or corporation. Whether you’re buying a duplex or a quadplex, this progr

Thinking about financing your next income property? The Short-Term Rental Loan program offers up to $6 million loans with options designed for flexibility. You can qualify with a minimum 680 FICO and use 12 or 24 months of bank statements instead of W-2s or tax returns. Loan types include adjustable-rate and 30-year fixed for purchases and refinances, including cash out and debt consolidation. Eligible properties range from single-family homes to non-warrantable condos and condotels, as long as condo units have kitchens and HOAs don’t restrict rental days or have ongoing litigation. Loans can close in the name of an LLC or corporation. Whether you’re buying a duplex or a quadplex, this program could help you get started. Get a mortgage rate quote — no personal info. Use our DSCR pogram to use the rental income as your income! ? Link in bio #InvestmentProperty #ShortTermRental #RealEstateLoans #NonWarrantableCondo #FidelityHomeGroup ? original sound – Fidelity Home Group® – undefined

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, floridamortgagecalculator

When your investment property income resets the mortgage dance.

Get a rate quote — no personal info. Orlando DSCR: 1.oo — property income covers mortgage 1.00x; may qualify for investor DSCR programs. When your investment property’s cash flow resets the mortgage game, sometimes you just have to dance back to where you started. Comment your city — we’ll post its DSCR stat within 24 hours. ? Link in profile #RealEstateInvesting #DSCR #MortgageRates #InvestmentProperty #Orlando

#fidelityhomegroup, #floridamortgage, #floridamortgagerates

Bridge Loans help you buy fast!

Get a rate quote — no personal info Thinking about your next property? Bridge loans can help you act fast without waiting to sell your current home. They let you use your existing home’s equity as a down payment for the new one. Here’s what you need to know: – Up to 75% LTV for primary homes, 60% for investment properties – No monthly payments, just one balloon payment within 6-12 months – Interest-only with fixed rates and no prepayment penalties – Minimum credit score 680 with a debt-to-income max of 50% This short-term financing covers the gap so you can make a non-contingent offer and move quickly. ? Link in profile #BridgeLoans #InvestmentProperty #RealEstateFinance #BridgeLoanFlorida #FidelityHomeGroup

#fidelityhomegroup, #floridamortgage, #floridamortgagerates

Veterans Mortgage Benefits

Get a rate quote — no personal info ? Thinking about buying a home with your VA benefits? Fidelity Home Group is here to help you make it happen with our Veterans Mortgage Programs. Enjoy amazing benefits like zero down payment, no private mortgage insurance, and lower monthly payments. Plus, the approval process is simplified just for veterans and active duty military. ??? Ready to take the next step? You don’t have to navigate it alone — our experts guide you every step of the way! https://www.fidelityhomegroup.com/va-mortgages/ ? Link in profile #VAMortgage #VeteransBenefits #FloridaHomeBuyers #FidelityHomeGroup #HomeLoanHelp

#fidelityhomegroup, #floridamortgage, #floridamortgagerates

Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know.

Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know. Simplifying The Market

A few years ago, sellers could get away with saying “no” to just about everything.

No repairs.

No concessions.

No negotiation.

If buyers wanted the house, they pretty much had to take it on the seller’s terms. But now that inventory’s grown, negotiations are becoming a normal part of the process again.

That’s why one of the most important things sellers need to understand right now is this:

The goal isn’t to “win” every negotiation.

Sometimes, it’s worth meeting buyers where they are to get a deal done, fast. One example? Helping with a buyer’s closing costs.

Let’s break that down, so you know what to expect if it comes up in your sale.

What Are Buyer Closing Costs?

Closing costs are the extra expenses buyers pay on top of their down payment when they purchase a home. Freddie Mac gives some examples:

  • Loan origination fees

  • Appraisal and inspection costs

  • Title and attorney fees

  • Survey fees and more

Typically, buyer closing costs range from about 2% to 5% of the home’s purchase price. So, on the typical $400,000 home, that could mean anywhere from $8,000 to $20,000 out of pocket.

And in today’s affordability-challenged market, that upfront cash can be a major hurdle for some buyers – even if they can comfortably afford the monthly mortgage payment itself. 

That’s why more people are asking sellers for help.

And More Sellers Are Saying “Yes”

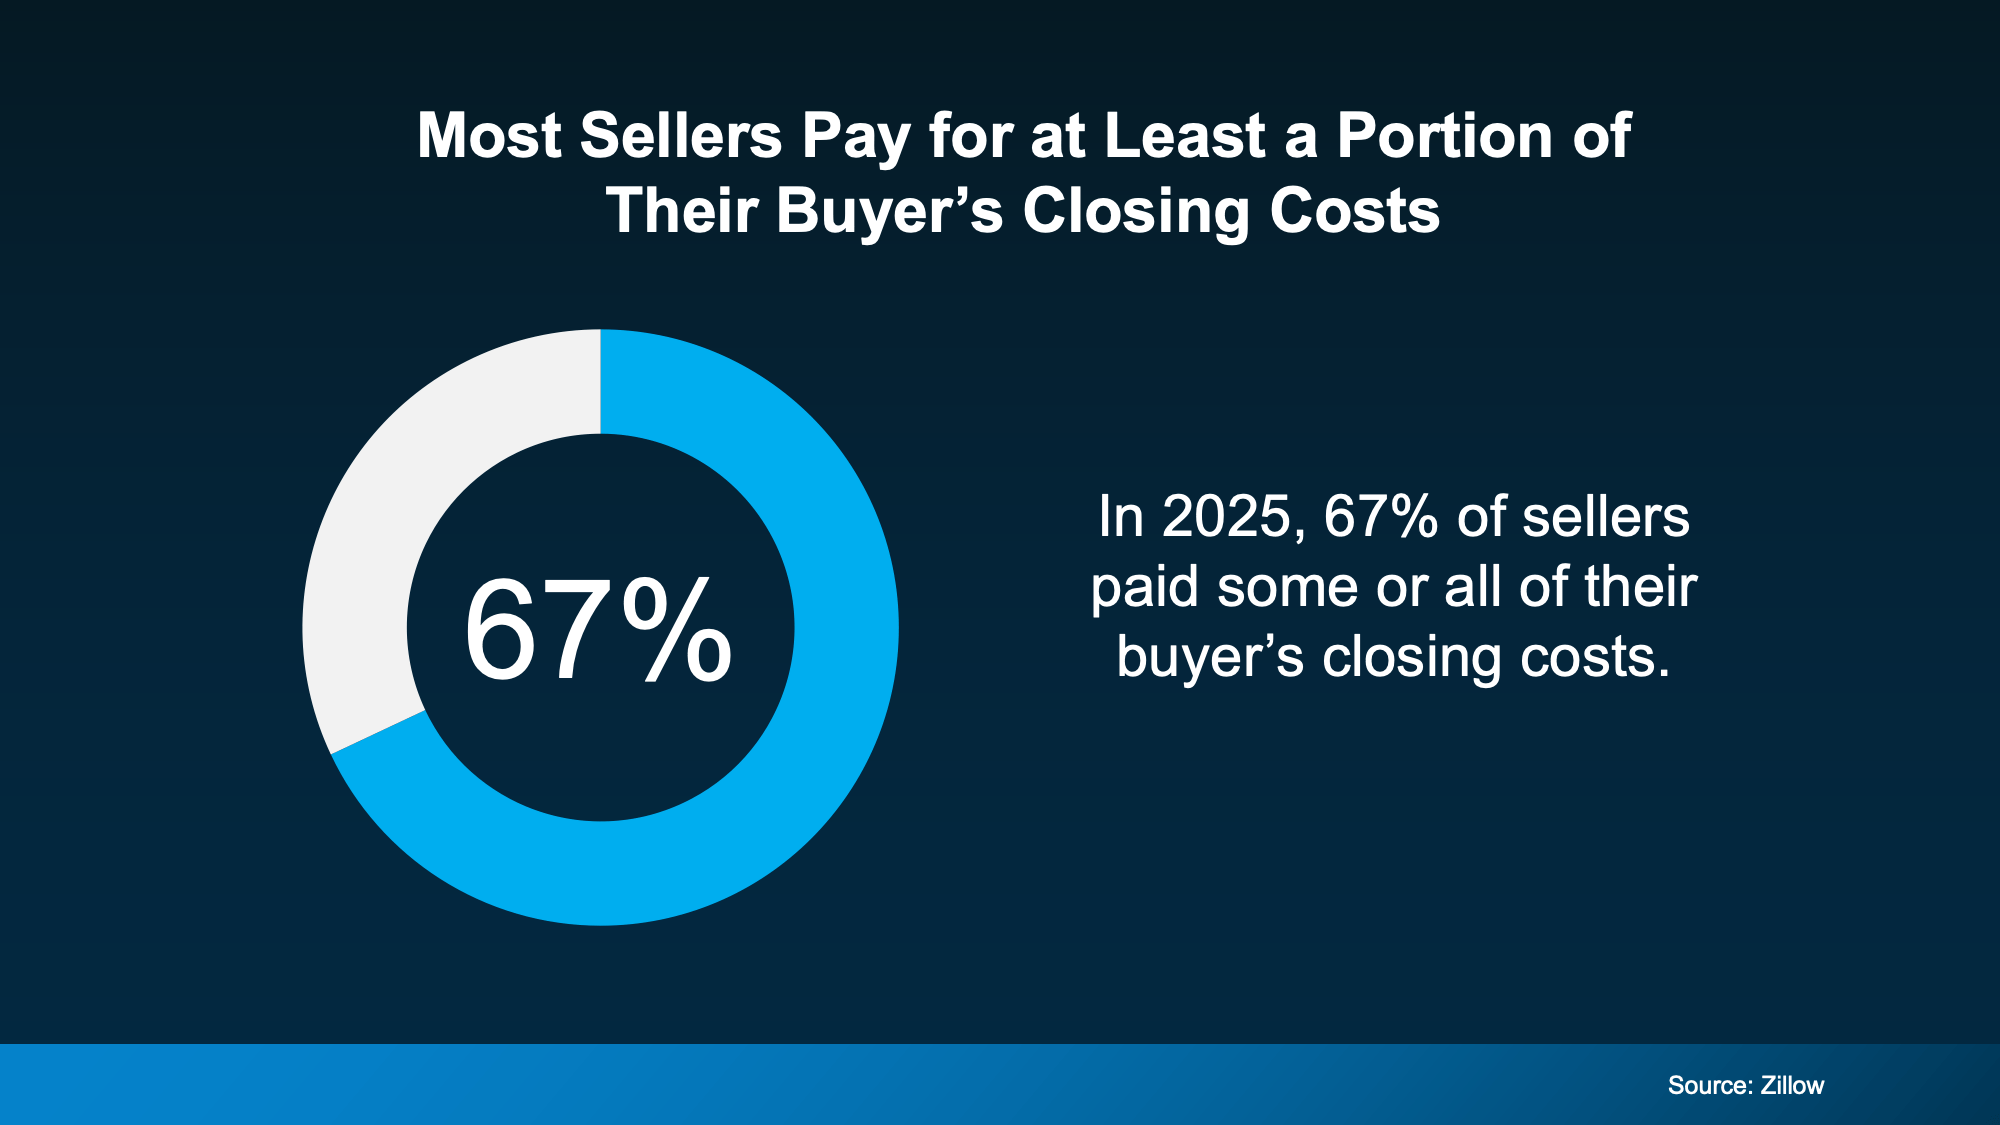
According to the latest data from Zillow, 67% of sellers reported paying some or all of the buyer’s closing costs in 2025 (see chart below):

a blue circle with white text

Now, that doesn’t mean every seller is doing it. And it definitely doesn’t mean every seller should. But it does show how common concessions have become as the market has shifted. And that’s important for you to know.

When Paying Closing Costs May Make Sense

This is where many sellers get stuck. They hear “help with closing costs” and immediately think: “Why should I pay for their expenses?”

But that’s not always the right way to look at it. You’ve got to consider who has the leverage in today’s market.

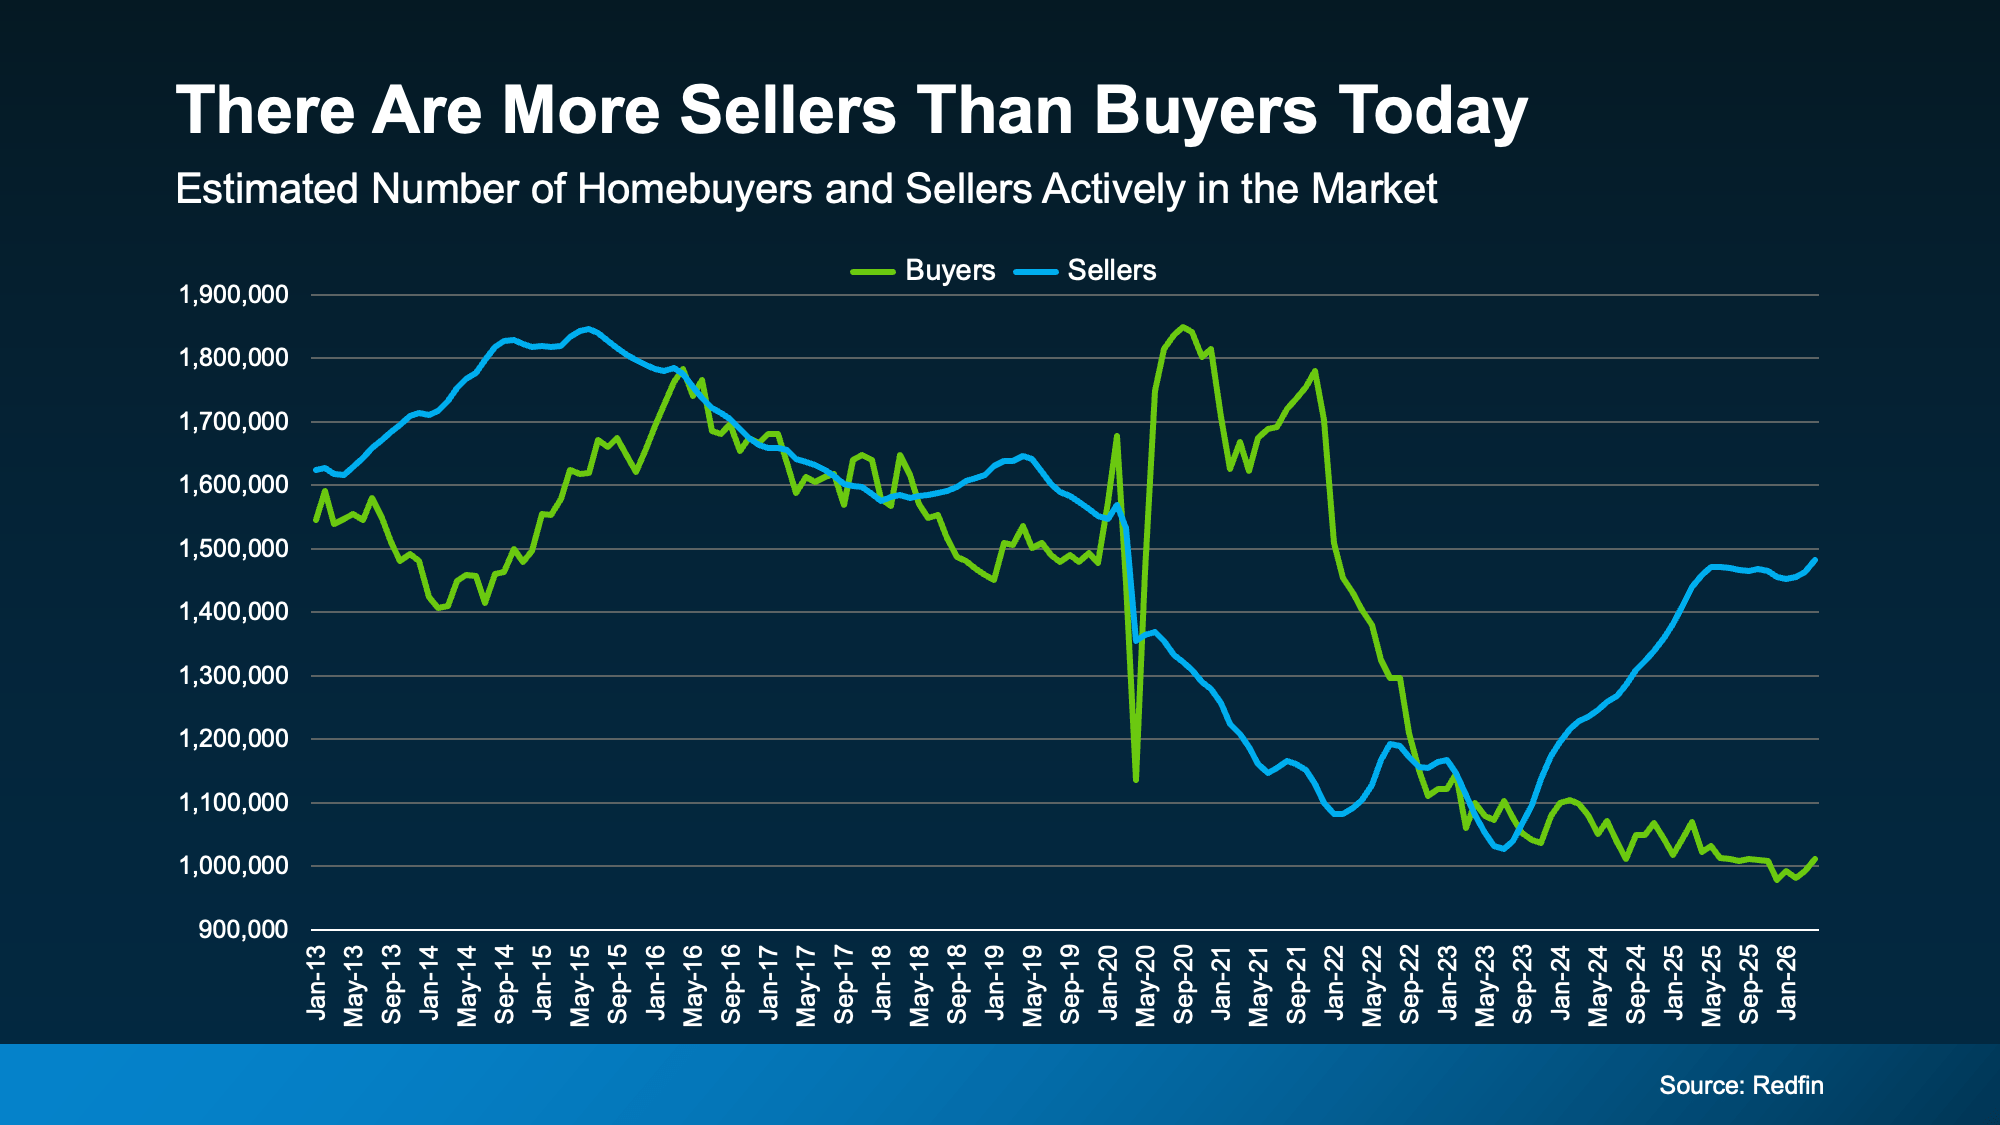
Redfin data shows there are more sellers than buyers active today. And that shifts the market dynamics (see graph below):

a graph of sales and buyers

That doesn’t mean every market favors buyers. Far from it. In some areas, homes are still selling quickly and sellers have plenty of leverage. But in others, buyers have more room to negotiate than they’ve had in years.

That’s why local market conditions matter so much when you make your decision.

For example, helping with closing costs may be worth considering if:

  • There are a lot of homes for sale in your area

  • Your house has been sitting on the market longer than expected

  • You’ve had showings, but no offers

  • You’re motivated to move quickly

  • Or you’re trying to keep a deal together during negotiations

After all, if it’s the thing that helps bring a serious buyer across the finish line, it could be well worth it.

Other Concessions You Could Offer Instead

Just remember, being flexible doesn’t mean saying “yes” to every request.  It means understanding which compromises actually help you accomplish your goals. Because there are always alternatives.

Redfin suggests considering other concessions if you’re not interested in helping with closing costs, like:

  • A home warranty

  • Repair credits

  • Flexible closing dates, or

  • Leave behind appliances or furniture

The right answer depends on what buyers in your market are asking for and what matters most to you. That’s exactly why working with an experienced local agent is so important.

Bottom Line

The sellers having the most success today are the ones who understand the market has changed and are adapting to meet it where it is.

Sometimes that means negotiating on closing costs. Sometimes it means offering something else. The key is knowing which concessions are worth it for your local market.

If you’re wondering what’s normal in your area, what’s worth negotiating, and where it makes sense to stand firm, connect with an agent.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida

Two Big Reasons To Move This Summer

Two Big Reasons To Move This Summer Simplifying The Market

A lot of people who want to move are telling themselves the same thing: “Maybe I’ll just wait until later this year once things calm down.” 

While waiting sounds like a good plan, there’s something worth knowing before you decide. Rates aren’t expected to change much, so if that’s the #1 reason you’re waiting, it may not pay off. And there may be other things you miss out on in the meantime. 

Historically, Summer is one of the strongest seasons of the year for both buyers and sellers. And if you delay your move until Fall or Winter, some of those opportunities may already be fading.

Buyers: Fresh Inventory Is Your Real Summer Advantage

One of the biggest frustrations buyers have faced over the past few years has been a lack of affordable options. Maybe you’ve run into that yourself:

  • You find a house you like, but it’s out of your budget.

  • You find something in your budget, but you don’t like it.

  • Or worse, nothing interesting hits the market for weeks.

Historically, Summer helps with that.

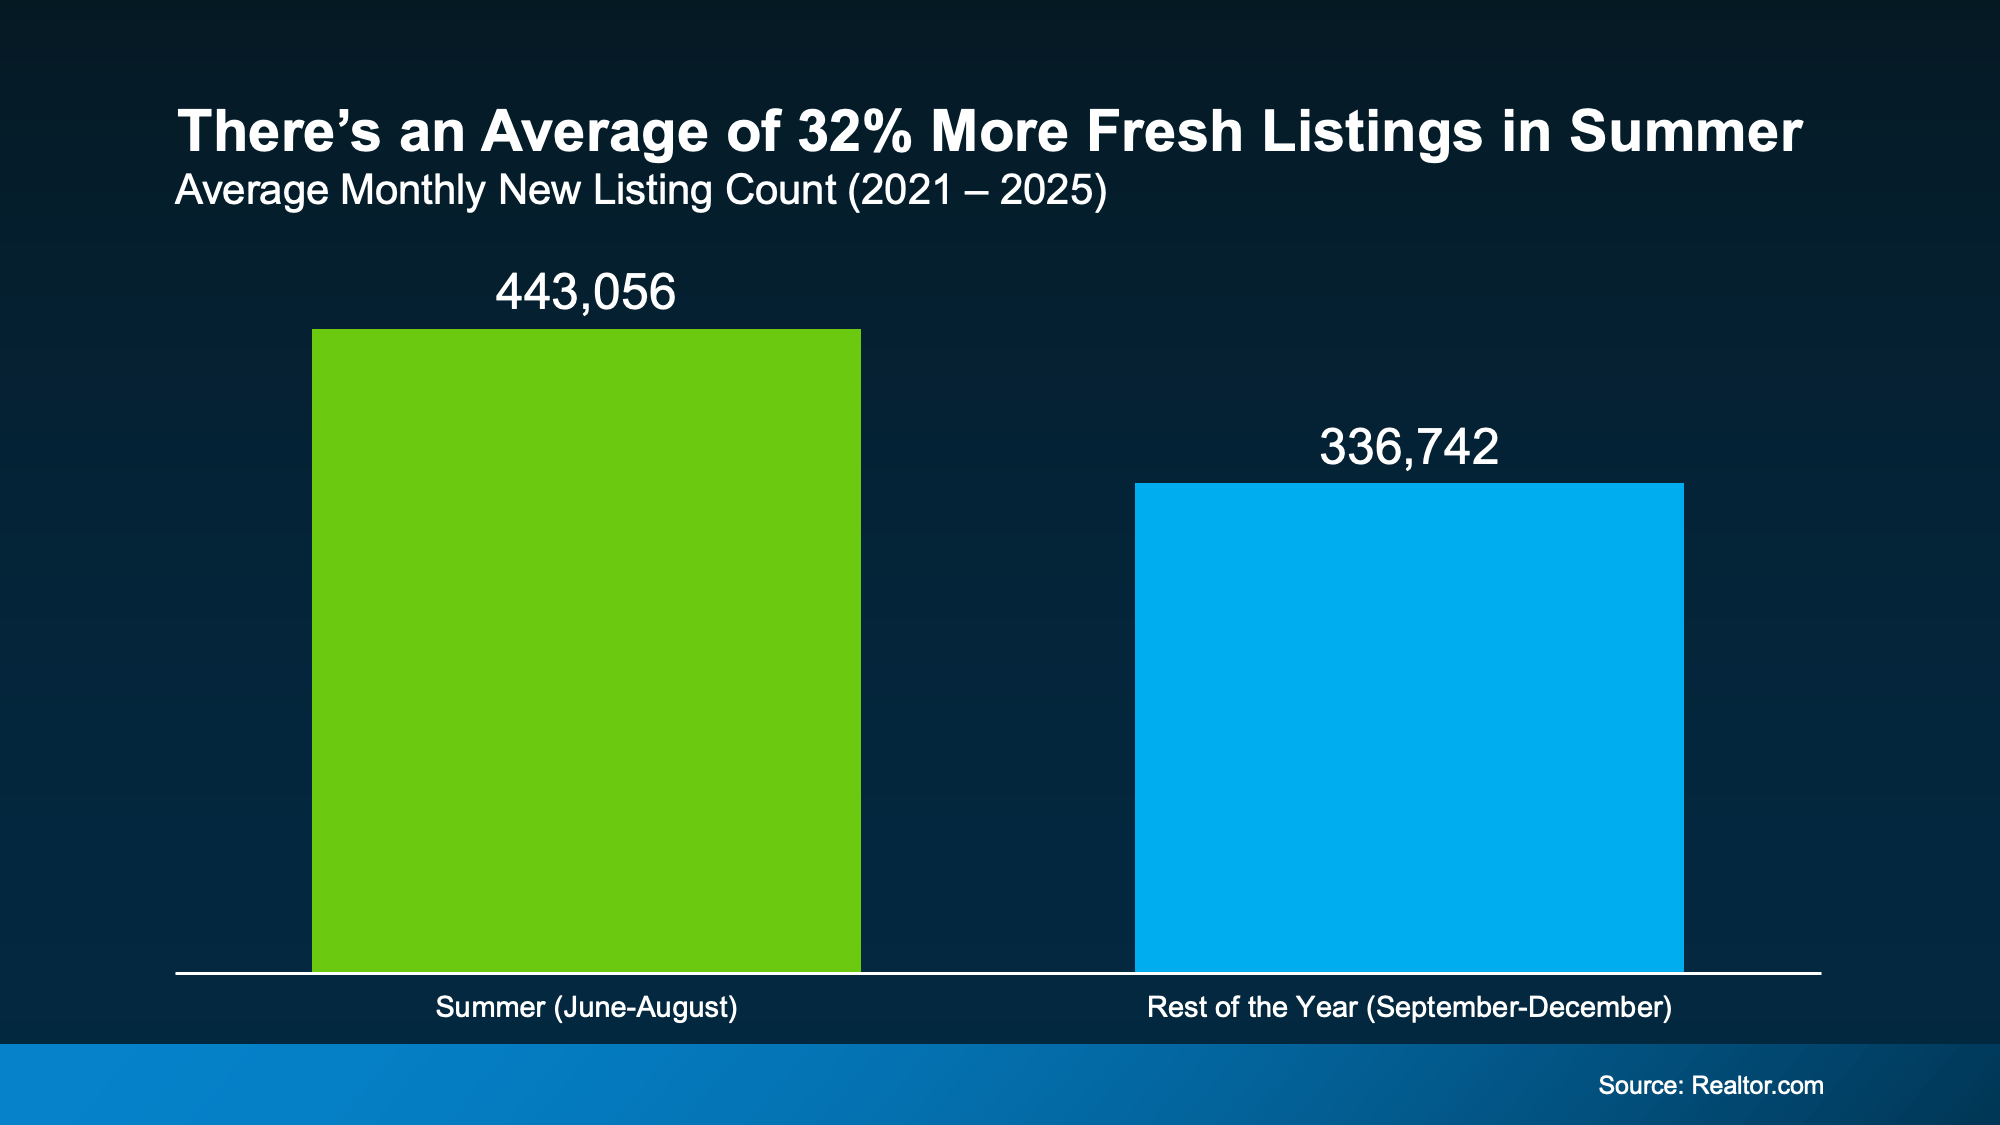
Looking at data from the last few years, Summer months consistently bring more sellers into the market than later in the year. And that gives buyers a real window of fresh choices.

According to Realtor.com, any given Summer month typically sees about 32% more fresh options than the average month from September-December.
a graph showing a number of prices

With more newly listed homes, there’s a better chance of finding one you like where the numbers actually work.

Because all it really takes is one home to completely change your search. And if you’ve got more popping onto the market to choose from, maybe one of those is exactly what you need. 

But keep in mind, this seasonal window isn’t open forever. Fresh inventory tends to slow down once Summer ends.

Many homeowners who planned to sell this year have already listed by then. Families who wanted to move before school starts have often already gotten it done, or at least, set it into motion. So, new listing activity usually cools as we head into Fall and Winter.

Of course, every year is different. But if finding the right home at the right price has been your biggest challenge, waiting until later in the year may not necessarily give you more options. In fact, recent history suggests it may do just the opposite.

Sellers: Homes Usually Sell for More in the Summer

If you’re thinking of selling, you may be considering holding off because you’ve seen headlines about lower asking prices, price cuts, and softer conditions in some markets. But those headlines don’t tell the whole story or convey just how much it varies by area.

Here’s what you really need to know. Even though the market’s becoming more balanced and some pockets are experiencing price declines, that doesn’t mean you’ve missed your chance to sell. 

Seasonality can still work in your favor no matter where you are. And this Summer could still give you the chance to sell for a good price.

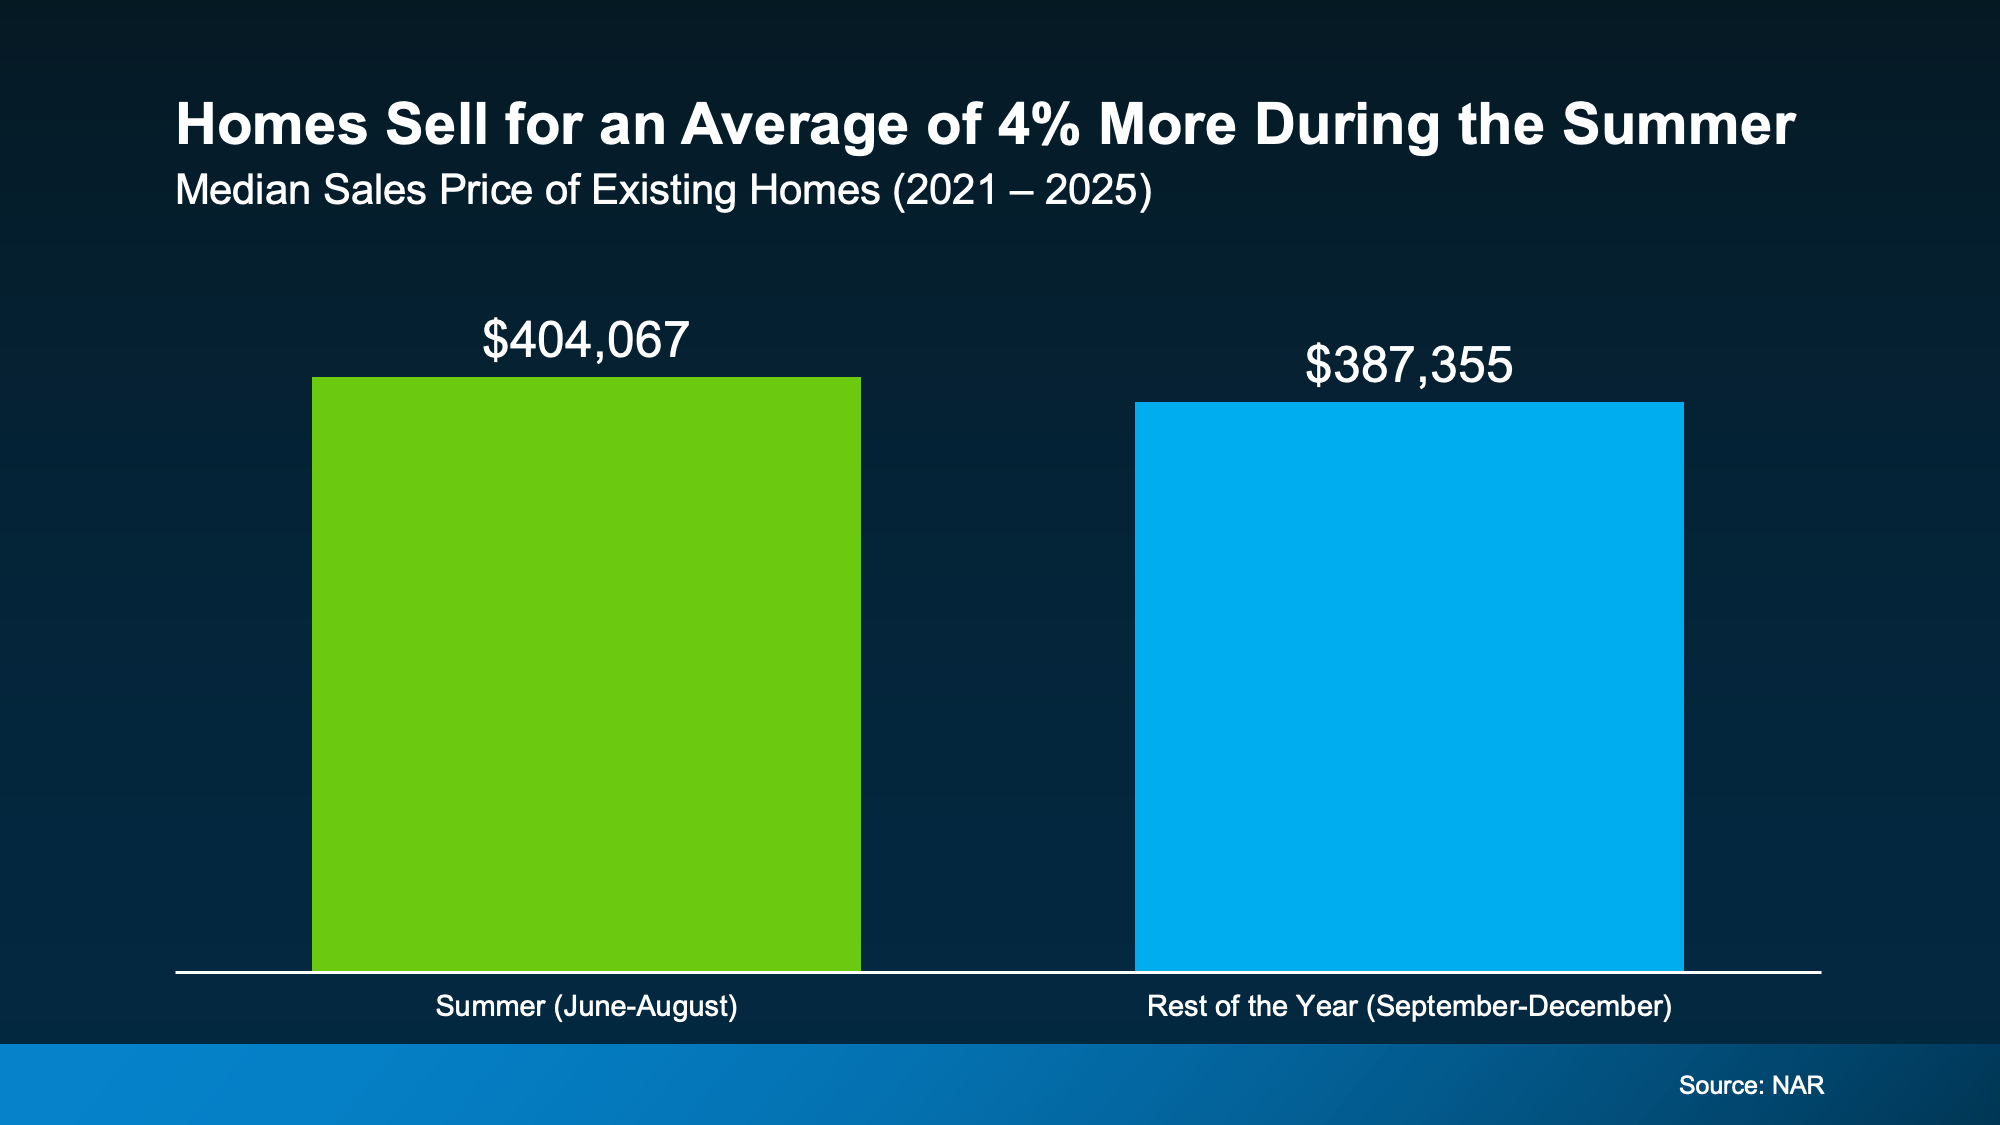
According to the National Association of Realtors (NAR), homes sold during a Summer month usually sell for about 4% more than homes sold during the typical month from September-December:
a graph of a sales report 

Why? Summer buyers are usually operating on a set timeframe. They’re trying to move before the next school year or when they have more PTO and warmer weather to tour houses. That urgency can translate into better offers.

Now, that doesn’t mean you should price your house 4% higher this Summer. That would actually be a mistake in today’s market.

It just means if you’re looking to get as much for your house as you reasonably can, a Summer move could be a smarter play than waiting until later this year. 

Because based on typical seasonality, you may get more for your house than you would if you waited until the Fall or Winter (when there are typically fewer buyers active).

And if you’re considering a move anyway, that’s worth factoring in.

Bottom Line

Could waiting until later this year work out? Sure. But it’s important to understand what you may gain by moving now too – that way you have the full picture before you decide.

If a 2026 move is on your radar, talk to an agent about what matters most to you. Depending on your priorities, Summer could be your moment.
#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida

Lower Asking Prices Are a Win for Today’s Buyers

Lower Asking Prices Are a Win for Today’s Buyers Simplifying The Market

If affordability has been the biggest thing standing between you and a home, there’s a little good news. 

Asking prices have started to come down.

The typical seller listed their house for a median of $429,500 in May. That’s 2.4% lower than a year ago, according to Realtor.com. On its own, that won’t transform what you can afford, but in today’s market every little bit helps and it signals a broader shift taking place.

Buyers Are Finally Catching a Break

Check out this data from Realtor.com and you can see this is the first May in years where buyers have caught any sort of break price-wise.

Each May from 2022-2025, things held pretty steady. But this year? You can see that more noticeable shift in your favor (see graph below):

a graph of sales in different colors

While the dip from $440,000 to $429,500 isn’t a big one, it gives you more breathing room. And that’s not a small thing when affordability has been this tough.

Now, lower asking prices don’t mean every home is suddenly within your range. But they do show buyers are gaining a little ground.

And in today’s market, a little ground can go a long way. 

What That Means for the Housing Market

And just in case this crossed your mind, this is good news for your move, not bad news for the market as a whole.

The subtle dip from last May to this one shows prices are easing, but they’re not dropping off a cliff. What this is actually a sign of is that the market’s rebalancing now that the number of homes for sale has grown.

Buyers have a bit more power again, and sellers know they can’t name just any price and expect their house to sell. They either meet the market where it is, or face a price cut later. And in general, sellers would rather avoid a price cut. As the New York Post explains:

“Rather than swinging for the fences with pandemic-era price tags, sellers are increasingly coming to terms with a new reality. The share of listings featuring price cuts actually fell to 17.5% in May, suggesting homeowners are doing their homework before putting up a “For Sale” sign instead of chasing unrealistic numbers and cutting later.“

This signals a broader change in the market.

Seller expectations have been skewed a little high since the pandemic buying frenzy – you’ve probably felt that firsthand. But now, things are starting to normalize. It could mean less back-and-forth to land on a fair number. And homes should be priced a bit more realistically from the start.

Bottom Line

If affordability has been your top concern, the recent dip in prices is an opening. Connect with a local real estate agent to see what that looks like in your area.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida