Available 7 Days/Week       MON - FRI  8am - 7pm       SAT - SUN  10am – 6pm
Call us (407) 955-4575
Apply Now

Category: Rent vs. Buy

Auto Added by WPeMatico

Want a More Affordable Home? Don’t Overlook Condos.
Want a More Affordable Home? Don’t Overlook Condos. Simplifying The Market

When you picture buying your first home, chances are you’re imagining a traditional single-family house with its own yard, maybe a garage, and little extra room to grow. But with affordability still tight, getting everything on that list right away may come with a higher price tag than you’re comfortable with right now.

So, if you’re running the numbers and buying a house like that feels like a stretch, there may be another way in. A condo.

Because in a lot of markets, condos come with a significantly lower price tag. And that could make them a smart way to get your foot in the door.

Condos Can Cost Less Than You Think

According to a recent study by Zillow: 

“Condos are the most commonly affordable home type in virtually every metro. At the starter level, the savings can be pretty significant. Nationally, starter condos average $197,468 — that’s about 6% less than the typical starter home.”

And depending on where you live, the difference can be much bigger. 

Zillow identified metro areas where typical starter condos are priced significantly below the estimated home price a median-income household could afford. Here are the top 10 according to that research (see chart below).

In Houston, the gap is at its widest. There, a typical starter condo was valued at about $85,600 – 72% below the price considered affordable based on the area’s median household income.
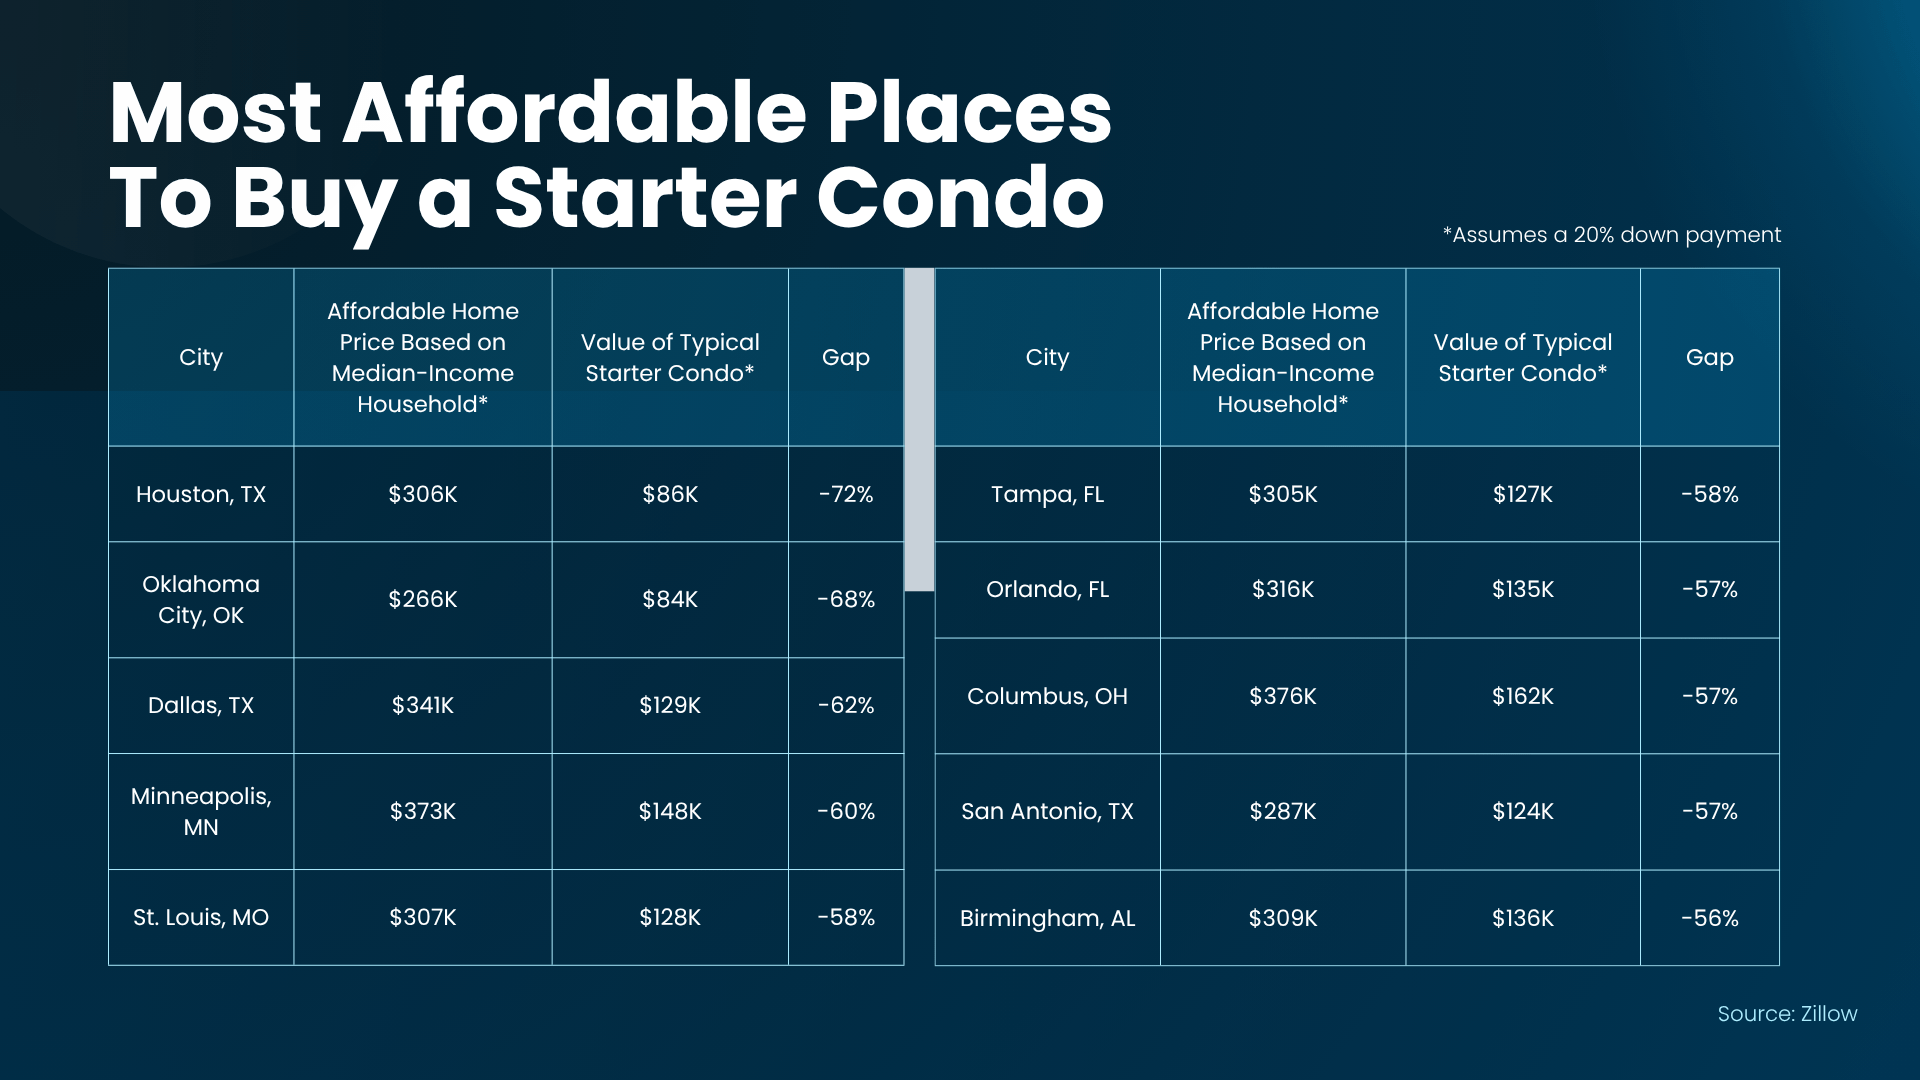
a blue and white chart with white text 

Of course, every market is different. But the bigger point is this: if you’ve only been searching for traditional single-family houses, you may be overlooking some of the more affordable options on the market.

And even if your city didn’t make this list, that’s okay. The trend holds true in many places across the country. Here’s why.

A Condo Could Give You a Different Way In

Part of the reason condos can cost less is pretty straightforward. They’re typically smaller. And less square footage can mean a lower purchase price.

So, if you can make do with a bit less space or you’re coming from a smaller apartment now, this can be a great way in. Plus, on the upside, you won’t have to buy a ton of furniture to fill out a bigger house. You can get a potentially lower price up front and spend less once you move in because you’ll need less new stuff to fill that empty space.

And more buyers are making that trade off on space to offset the current affordability challenges. Ali Wolf, Chief Economist for New Home Source, explains:

“In addition to favoring smaller floor plans, more consumers are showing a willingness to live in an attached home. This shift is not driven by a preference for shared walls, but by a pursuit of value.”

That’s really the heart of it. Looking at condos isn’t necessarily about wanting less. It’s about finding another way to make your move happen with the budget you have.

Don’t Rule Out an Option That Could Work

If you’ve been struggling to find a house you like at a price you can comfortably afford, talk to your agent about adding condos to your search.

You may find something in a neighborhood you thought was outside your budget. You could get access to amenities you wouldn’t otherwise have. And you may be able to become a homeowner sooner rather than waiting for the numbers on a single-family house to work.

While there are trade-offs like shared walls, less outdoor space, and an HOA fee to factor into your monthly budget, maybe that’s worth it if you finally get your own set of keys.

Plus, a lot of the times, a condo community comes with great amenities like pools, gyms, and the condo association handles at least some of the maintenance. Which is closer to what you’re used to from your apartment – it could make the transition to homeowner not just more affordable, but that much easier too.

Bottom Line

The first home you buy doesn’t have to be a single-family house. If affordability has been holding you back, talk to a local agent about expanding your search and see whether a condo could fit the price point you’re looking for.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
The Biggest Credit Hurdle for Renters Who Want To Buy

The Biggest Credit Hurdle for Renters Who Want To Buy Simplifying The Market

What’s the biggest payment you make every month? If you’re a renter, it’s probably your rent. 

But did you know that you can pay your rent on time, every time, for years, and it may never show up in your credit history? It’s pretty frustrating, especially if you’d like to buy a home someday and you’re trying to build your credit.

The good thing is that’s changing right now. Here’s what you need to know and why it could open a door you thought was closed.

The Problem for Would-Be Buyers

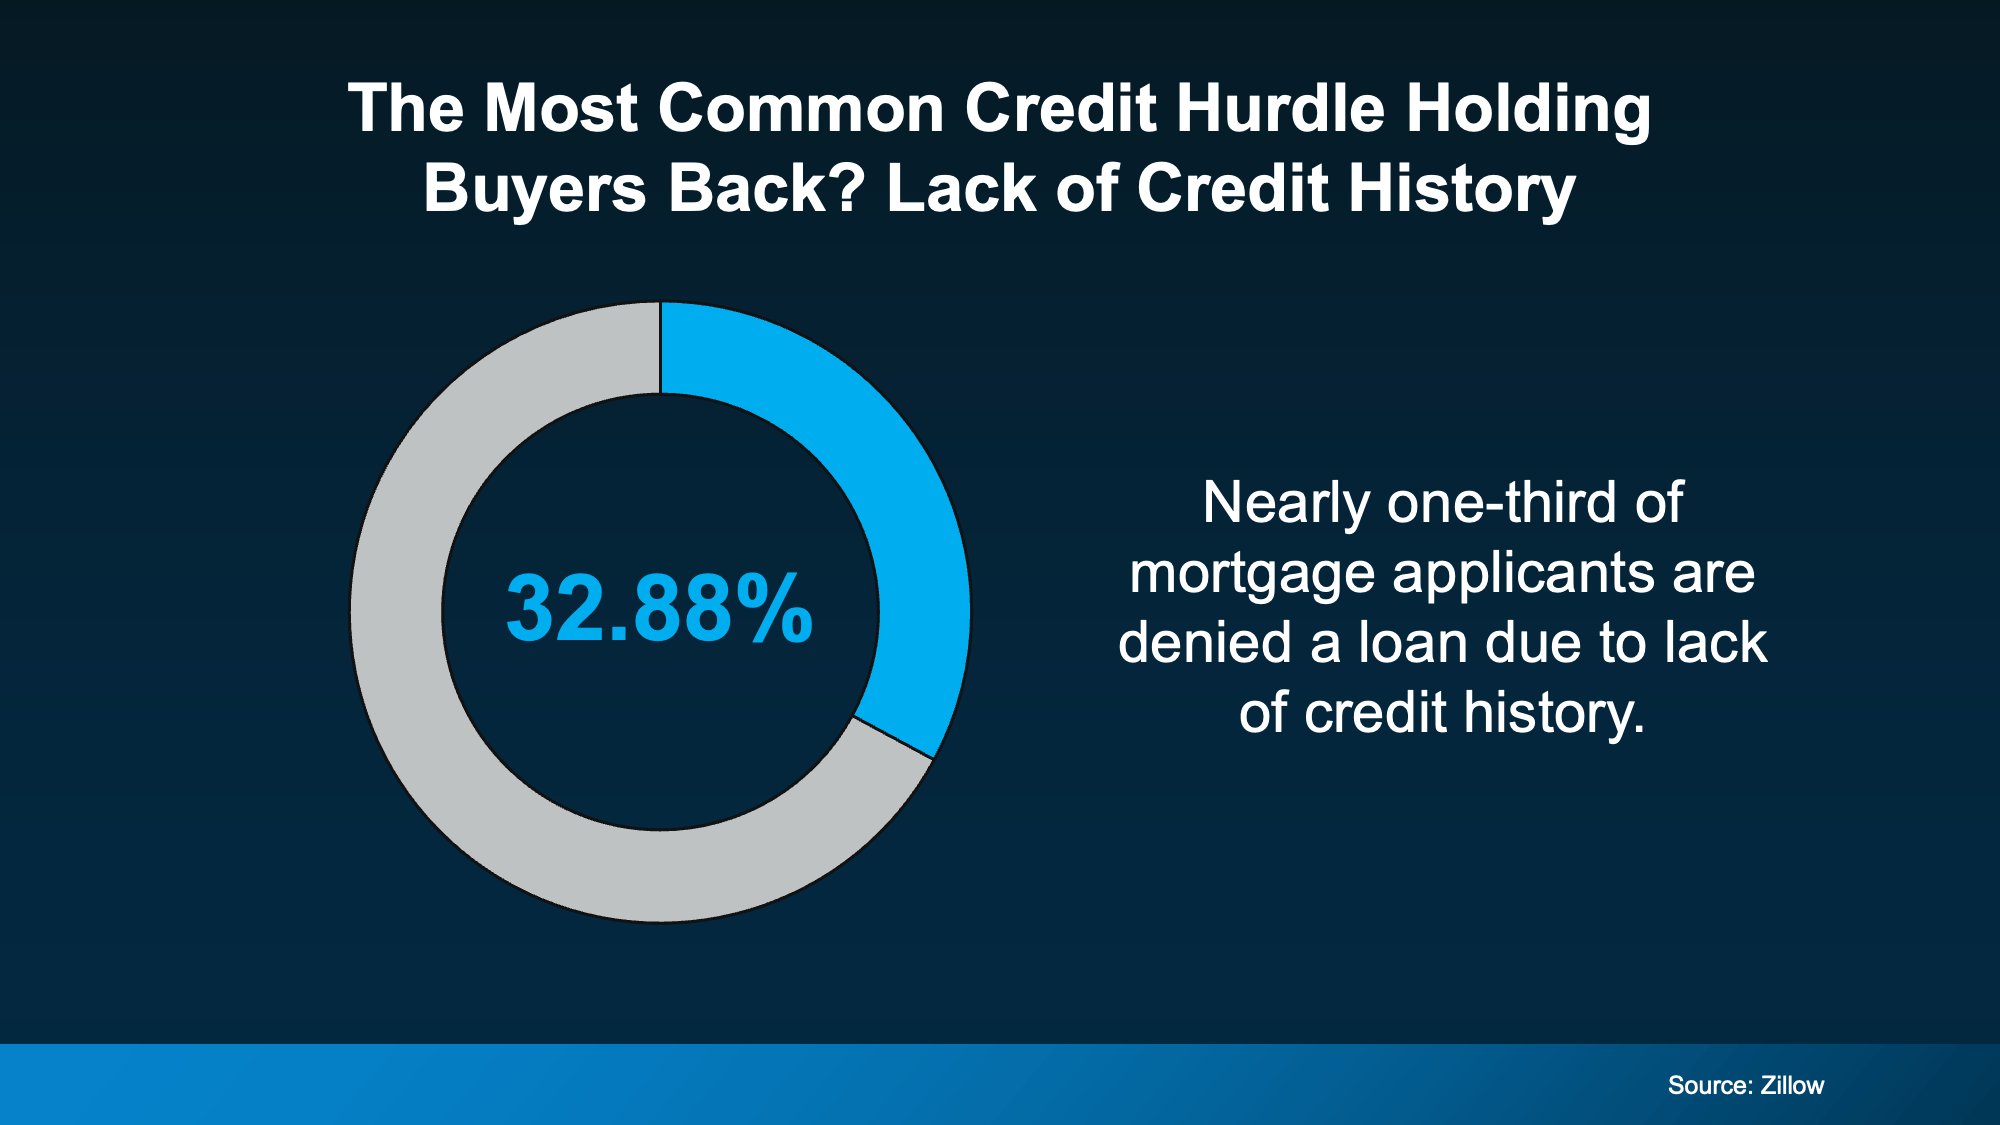
You’re not the only one frustrated. According to Zillow, nearly a third of applicants (32.88%) get denied a mortgage due to insufficient credit history – not missed payments or too much debt. Just not enough credit history for a lender to say “yes.”

It’s the most common hurdle would-be buyers have. As Zillow explains:

“Nearly one-third of mortgage applicants are denied a loan because of insufficient credit history, making it the most common reason for a denial.”

a blue and grey pie chart

But there’s finally a way in now that how credit gets measured is changing.

The Good News: Credit Is Getting Broader

As Michael Sherman, General Manager and Senior VP at Zillow Rentals, explains:

“Affordability is the headline in housing right now, and access to financing is a very important part of the story. Credit history is a barrier standing in the way of too many potential buyers. Rent reporting is a direct way to address that.”

Here’s what Sherman is talking about. New credit models are emerging that take on-time rent and some utility payments into consideration to help renters get credit for the bills they already pay.

VantageScore is one company with a new credit model that has been approved for use by the Federal Housing Finance Agency (FHFA). And that roll out could have a big impact on renters like you.

A recent study by VantageScore found that nearly 4 million U.S. renters could finally become eligible for a mortgage if their on-time rent payments were counted as part of their credit history. Now, this isn’t a guarantee that it will suddenly count for every would-be buyer, but it does crack open the door.

Here’s the catch though, you still have to walk through it.

Counting Rental Payment History Is Not Automatic

There are more options available to build credit, but you have to be proactive. Your rent won’t necessarily count unless you make sure it does. And the sooner you take credit for your payments, the better.

Here’s how to get started based on a few tips from Experian, the Consumer Financial Protection Bureau (CFPB), and FICO:

  • Ask your landlord or property manager if your rent is being reported. If it’s not, opt in. 

  • If your landlord doesn’t offer rent reporting, there are services available. Be sure to check fees and which bureaus they provide your data to.

  • Check your credit reports for errors. Mistakes happen and fixing them is one of the quickest ways to strengthen your profile. The CFPB offers step-by-step instructions on how to fix errors on your report.

  • Follow basic, important credit rules. Pay your bills on time, keep your card balances low, and don’t apply for a bunch of new credit at once.

  • Don’t close any accounts – even if you have paid them off and don’t use them often.

  • Diversify your profile by getting a secured credit card or becoming an authorized user on someone else’s account to help you build history beyond rent.

These steps take a little time and effort, but it could be worth it if it starts building up your credit history. 

Just remember, not every lender uses the same scoring model and there are more changes on the horizon. So, the sooner you get credit for the work you do, the better. 

Even if you’re not sure when you might be ready to buy a home, talking to a lender is a good place to start. A professional loan officer will help you make a plan and help you figure out a timeline to get ready to officially apply and buy.

Bottom Line

The credit landscape is changing, but action is required on your part. You have to take credit for what you do. And the sooner you get started, the better.

Ready to see where you stand? A quick conversation with a loan officer costs you nothing and could show you you’re closer to owning a home than you think.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Why Most People Are Still Glad They Bought a Home

Why Most People Are Still Glad They Bought a Home Simplifying The Market

With everything going on, it’s understandable if you’re wondering if you’d regret buying right now. 

Everyday expenses cost more. Mortgage rates are higher than you’d like. And when the economy feels uncertain, taking on a mortgage can feel like a much bigger leap. But here’s some perspective that may help…

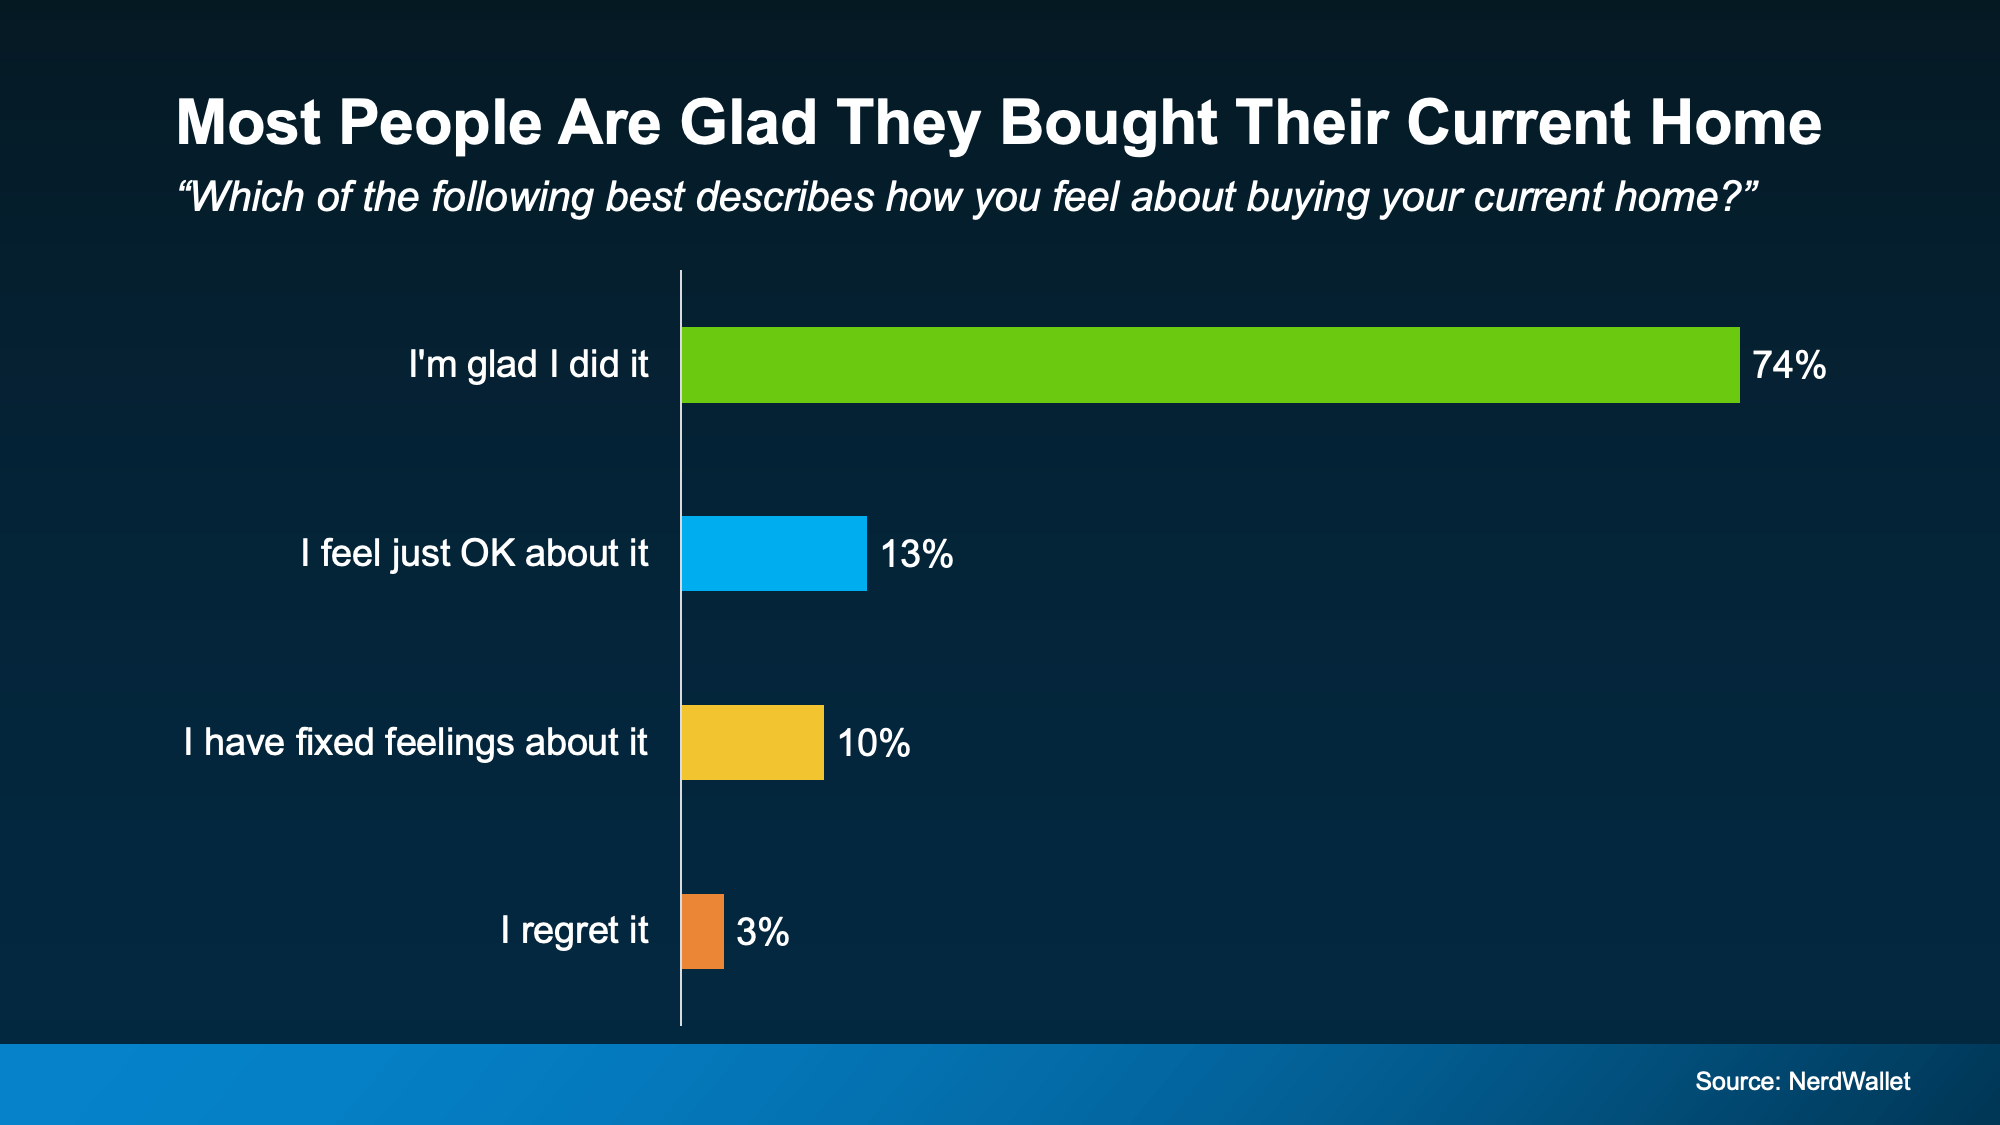
Most people who already made that leap would do it again.

According to a recent survey from NerdWallet, the vast majority of recent buyers (74%) were glad they bought their current home. Only a very small 3% of people regret it:

a graph with text on it

And here’s a big reason why so many people feel it was worth it, even now.

Homeownership Is a Long-Term Play

When you’re deciding whether to buy, it’s easy to focus on what’s happening right now. What’s today’s mortgage rate? Are prices going up or down? Those things matter. But don’t get so caught up in buying in the perfect moment that you miss the bigger picture.

A home isn’t typically something you buy for just a year or two. It’s a longer-term play. And when you zoom out, it all starts to fall into perspective – especially if you look at home prices and equity.

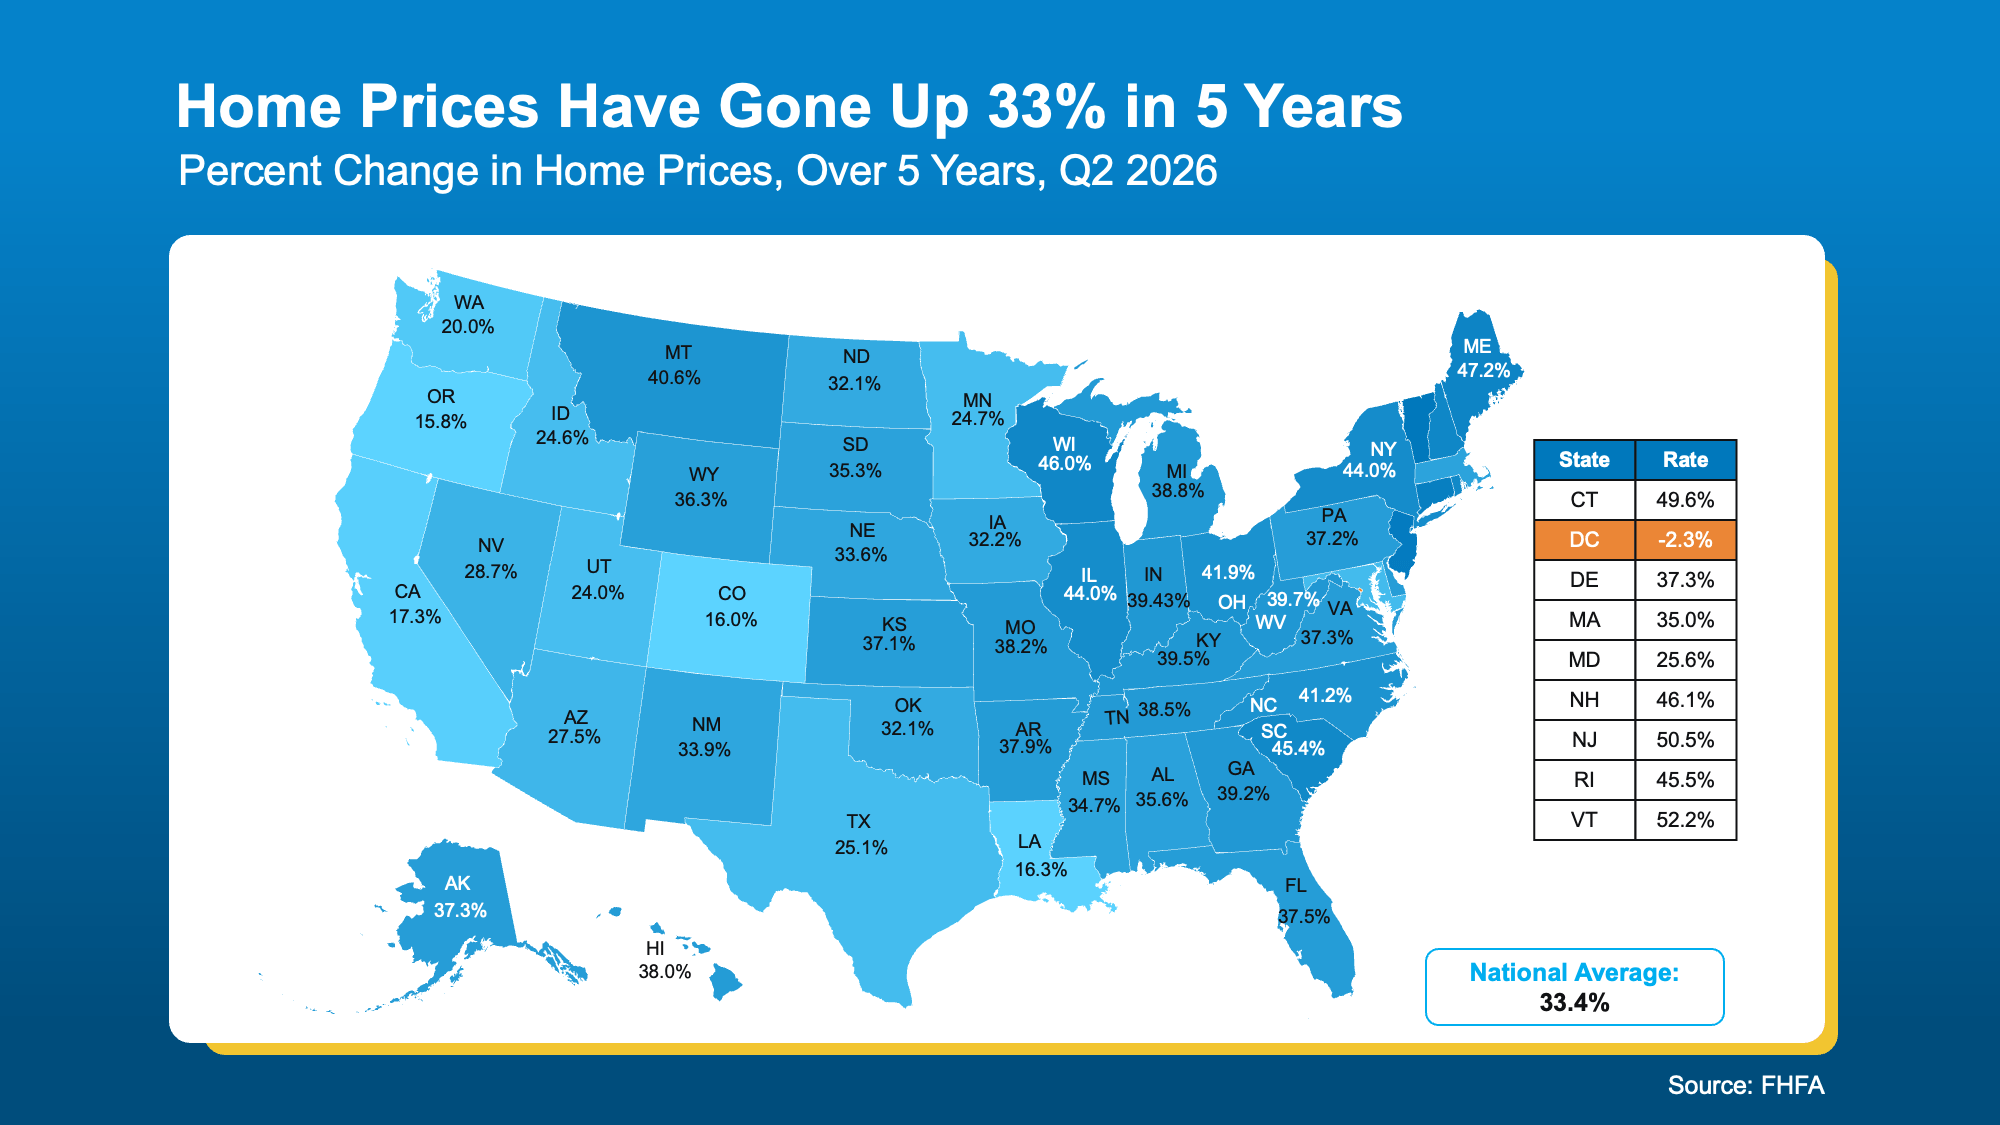
According to data from the Federal Housing Finance Agency (FHFA), home prices nationally have risen 33.4% over just the past five years (see map below):

a map of the united states

And that appreciation has helped current homeowners build some serious wealth. Research from Bankrate shows homeowners gained an average of nearly $150,000 in wealth over the past five years as equity steadily rose across 90% of major metro areas.

That’s one of the biggest benefits of homeownership. As you pay down your mortgage and your home appreciates over time, your ownership stake – your equity – can grow.

Now, Zoom Out Even Further

The five-year numbers are impressive. But the numbers get even more dramatic when you look at decades instead of individual market cycles.

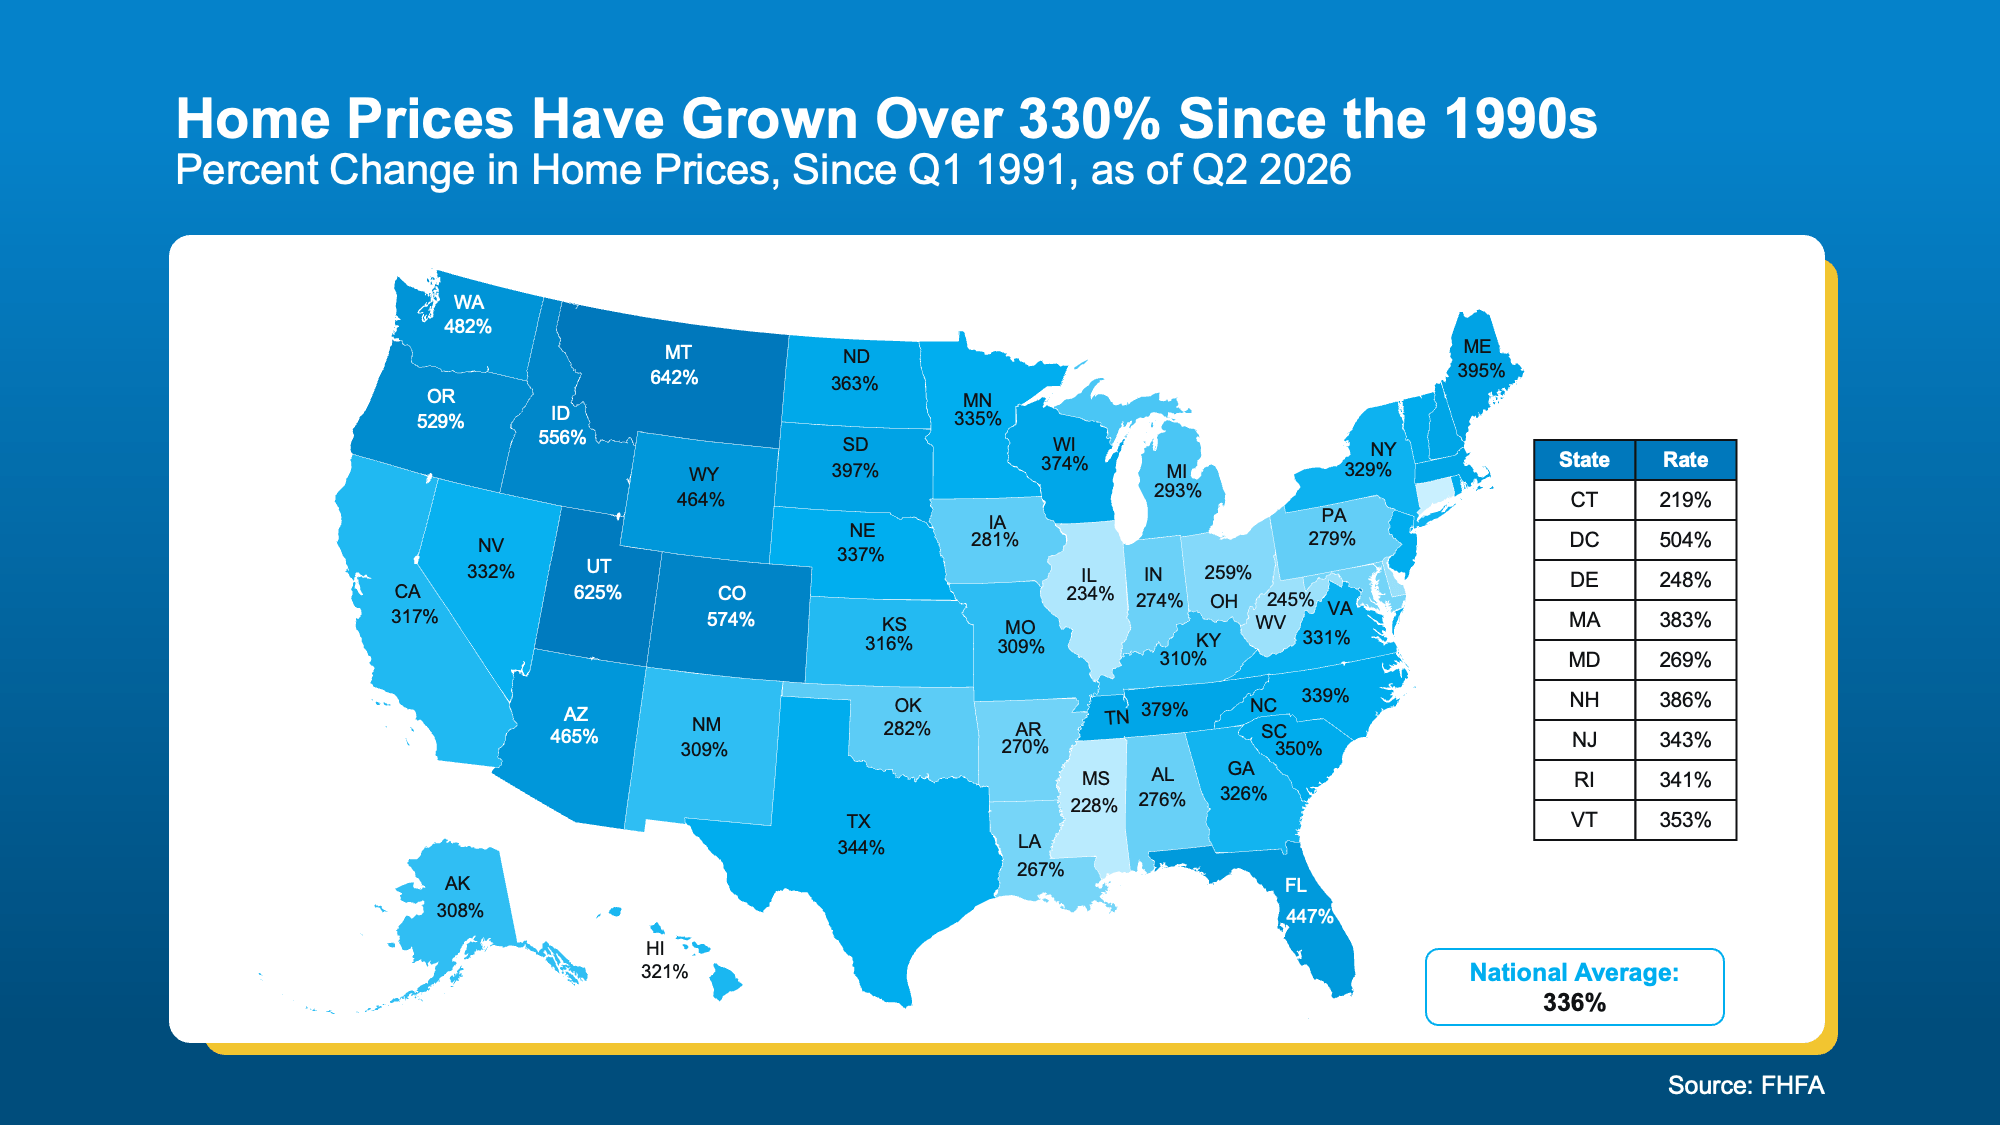
FHFA data shows home prices nationally have risen 336% since 1991. Sit with that for a second. Three hundred percent (see map below):

a map of the united states with numbers and a number of states 

That doesn’t mean prices go up every single year. And it doesn’t mean buying is automatically the right decision for everyone today. You should only buy when the numbers (and the payment) work for you.

What it does show is why trying to perfectly time the market can make you miss the bigger picture. 

Over time, homeowners gain a lot of equity. And that equity can eventually become a powerful financial resource. As Freddie Mac explains: 

“Your home’s equity is part of your total wealth as a homeowner. If you decide to sell your home, the equity you have built over time will come back to you in the sale. . .

If it’s time to upsize or downsize, you can use that cash for the down payment on your next home.”

Basically, if you can afford to do it, buying a home now could set you up for future moves.

And just in case you’re someone who’s worried about what happens if prices do fall, after you buy, remember: you’re not buying for one year.

Prices can dip. They have before. But historically, they’ve risen far more over the long run. And the longer you own your home, the more time you have to ride out those ups and downs and keep building equity.

Bottom Line

Don’t let today’s uncertainty make you lose sight of what homeownership can do over time. Most homeowners say they’d make the same choice again. And decades of home-price growth help explain why.

If you’re wondering whether buying makes sense for you right now, connect with an agent to look at the numbers together – and what owning a home could mean for you in the years ahead.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
14 Years Running: Why Real Estate Is Still America’s Favorite Investment

14 Years Running: Why Real Estate Is Still America’s Favorite Investment Simplifying The Market

Quick gut reaction. Which investment do Americans trust more than stocks, gold, savings accounts, and bonds? The answer hasn’t changed in 14 years. 

It’s real estate. And this year, that answer comes with even more conviction behind it. New data shows people aren’t just saying homeownership is a smart move, they’re feeling better about it than they have in years. Let’s dig into why.

Real Estate Takes the Top Spot – Again

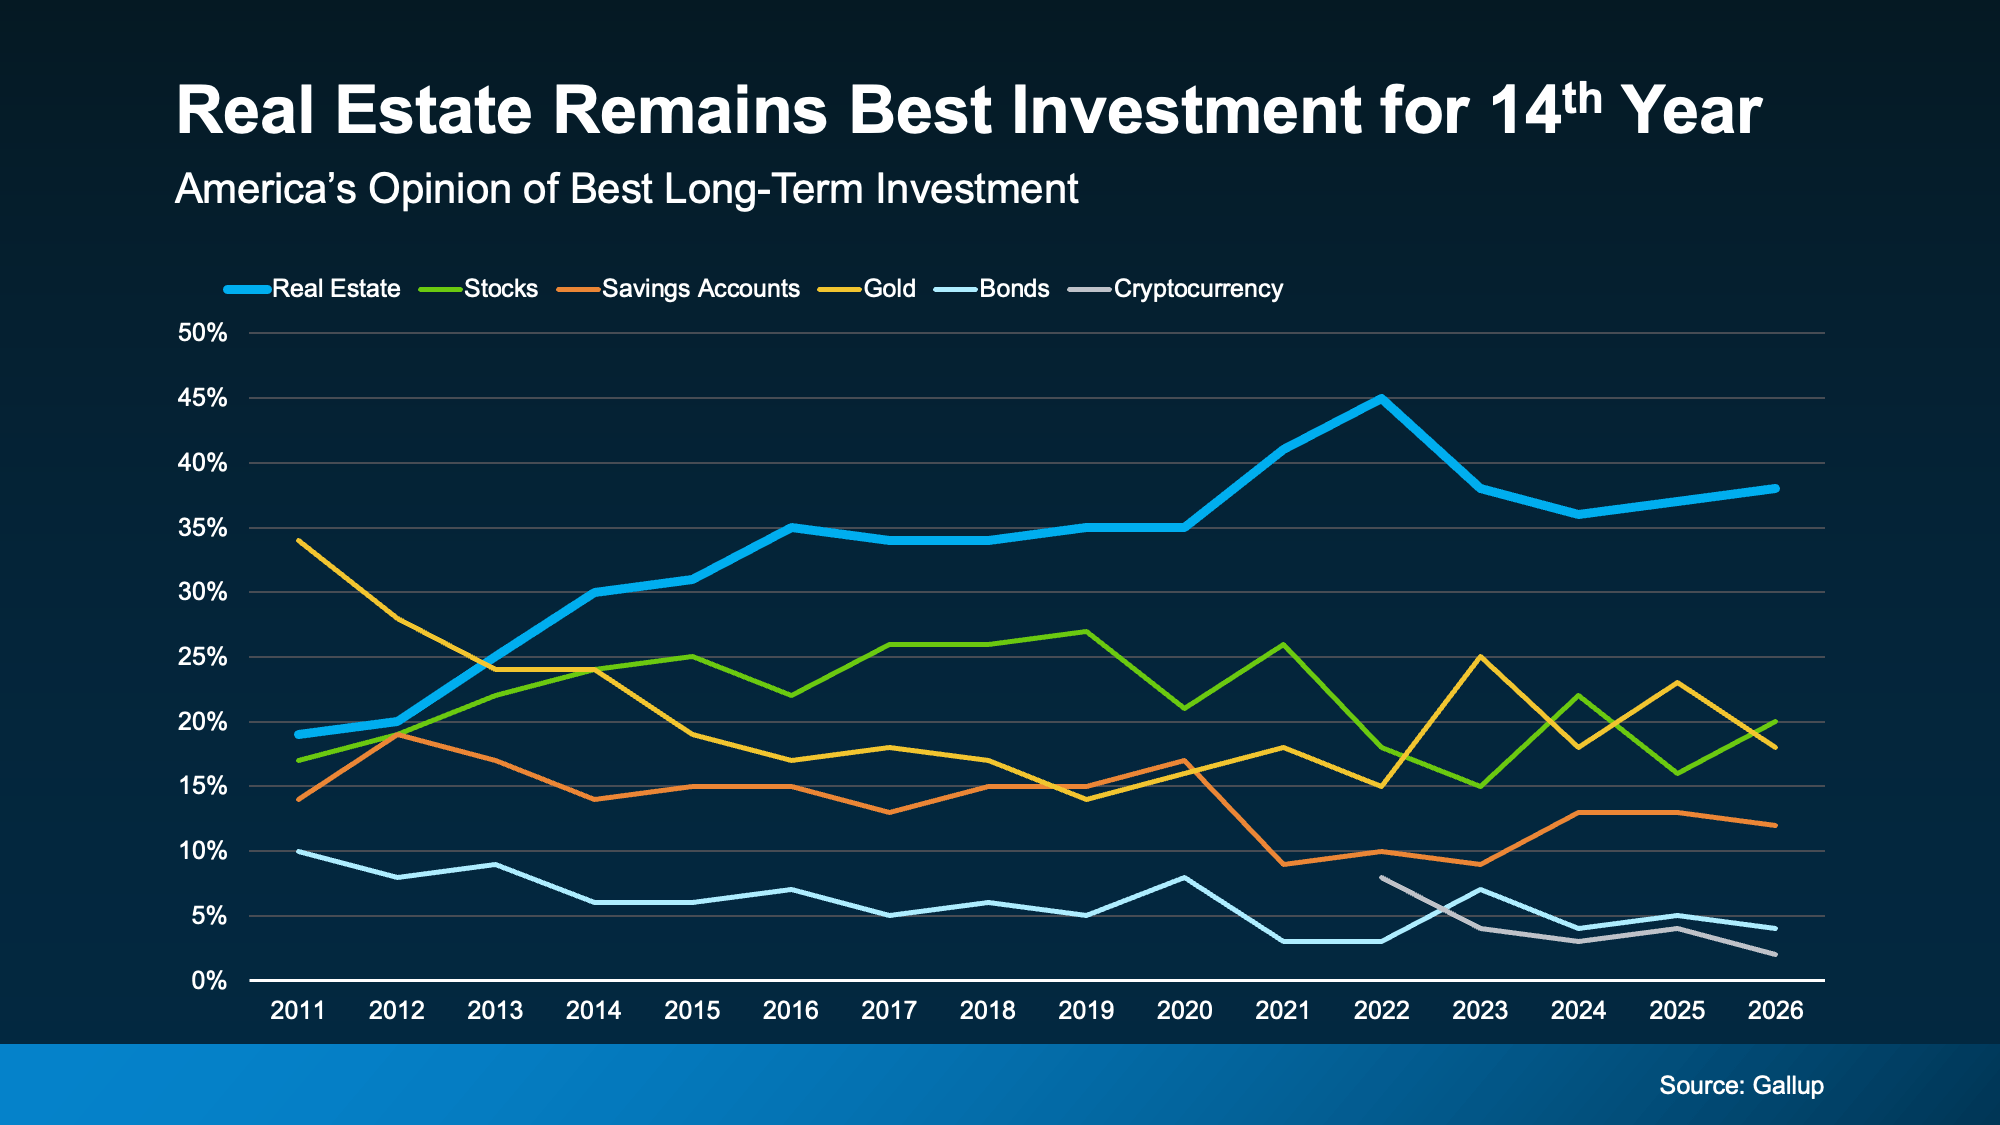
Every year, Gallup asks Americans to name the best long-term investment. And for the 14th year in a row, real estate came out on top (see graph below):

a graph of different colored lines

That’s not a fluke or a hot streak. That’s 14 straight years of beating out stocks, gold, and everything else.

Think about everything that’s happened in that stretch – rising rates, market swings, election years, you name it. Through all of it, Americans kept picking real estate. That kind of staying power says something about how people view homeownership – and it makes sense. Historically, it’s one of the best ways to build wealth in this country.

As Michelle Egan, Head of Credit Solutions, Impact Finance at JPMorgan Chase, explains:

“Owning a home has long been considered one of the most reliable ways to build wealth. Beyond providing shelter, a home is a valuable asset that can appreciate over time, build equity, and serve as a financial resource for generations.”

Now, you may have seen chatter online saying home prices are falling and wondered if that changes the math. It really shouldn’t. Nationally, home prices are still rising – just at a slower pace than a few years ago.

Yes, some local markets are seeing slight dips, but those dips are small compared to how much home values have grown over the past 5 years. Generally speaking, home prices almost always rise. As long as you plan to live there for a good length of time, you should still have the chance to build equity.

More People Say Buying Beats Renting

And while it’s true homeownership has been seen as a worthwhile pursuit for years now, something interesting is happening. It may actually be gaining a bit more popularity again.

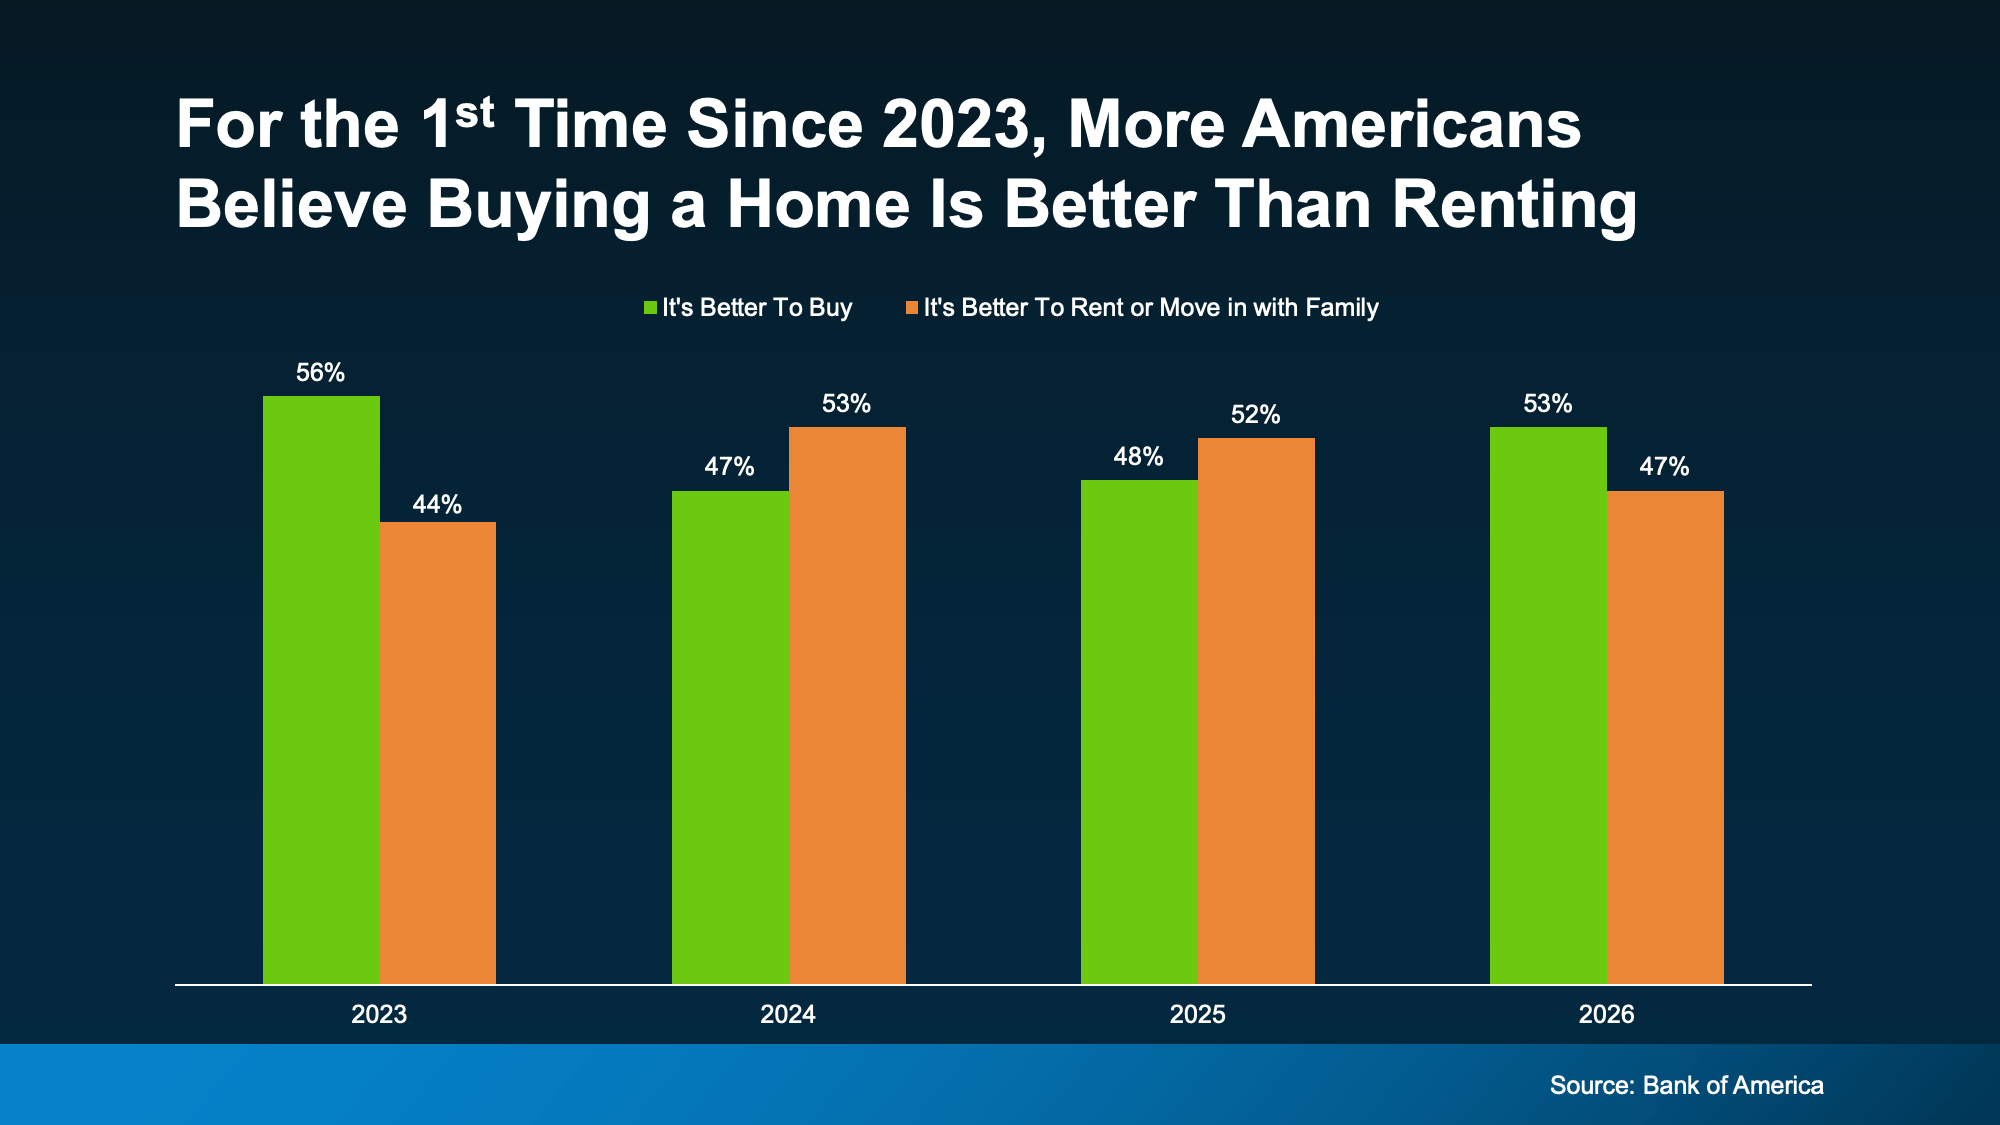
According to Bank of America‘s latest Homebuyer Insights Report, 53% of people now say it’s better to buy a home than to rent or move in with family. That’s the first time buying has taken the lead since 2023 (see graph below):

a graph of a number of green and orange bars

In that same report, here are a few other signals that confidence in homeownership is on the rise:

  • 90% of people say a home is a valuable investment, up from 79% just last year.

  • And 94% say owning a home provides stability, up from 83% the year prior.

Those are relatively big jumps in a short amount of time. And here’s what may be driving it.

It’s About More Than Money

Sure, affordability is still tight and some markets are still hard to break into, but that hasn’t changed what people feel about homeownership as a goal. And the reason why is simple – it’s not just a financial decision. It’s a lifestyle choice.

A home pays you back in ways stocks never could. As Sheharyar Bokhari, Principal Economist at Redfin, says:

“For many homeowners, a home is more than a place to sleep and store belongings—it’s a reflection of who they are. Homeownership can help people put down roots, build relationships and create a space that feels uniquely their own.”

You can’t get that from a brokerage account. A home is the one investment that grows your wealth and gives you a place to build your life. And that means something.

Bottom Line

For 14 years straight, Americans have called real estate the best long-term investment, and confidence in owning a home is on the rise. If you’ve been weighing whether buying is worth it, connect with a local real estate agent and talk through what that first step could look like for you.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Rent or Buy? The Real Tradeoff Most People Don’t Talk About

Rent or Buy? The Real Tradeoff Most People Don’t Talk About Simplifying The Market

You’ve probably asked yourself lately: Is it even worth trying to buy a home right now? It’s a question a lot of people are asking.

With today’s home prices and mortgage rates, renting can feel like the easier path. In some cases, it might even seem like the only realistic option right now. And if that’s where you are, there’s nothing wrong with that.

But if you’re weighing the decision, there’s one part of the conversation that doesn’t get talked about enough.

It’s what each choice does for your future.

What Renting Really Gets You (And What It Doesn’t)

Depending on your situation, renting does have some advantages:

  • Lower upfront costs.
  • Less responsibility.
  • More flexibility to move when you want.

But even with those benefits, a Bank of America survey found 70% of aspiring homeowners worry about what long-term renting means for their future. And that concern comes down to one thing: you’re not building anything for your future. As Yahoo Finance explains:

“Paying rent doesn’t build equity. You get a place to live, but no ownership stake, no price appreciation, and no asset to leverage for future borrowing or investment.”

So, while renting may feel easier, the flexibility you get comes at a cost.

How Homeownership Builds Your Wealth Over Time

On the other hand, owning a home is one of the most consistent ways people build wealth over time. Why? When you’re a homeowner, you gain something called equity. That’s the difference between what your home is worth and what you owe.

That equity grows with every monthly payment you make. It also gets a boost as home values go up through the years – and it adds up quicker than you may think.

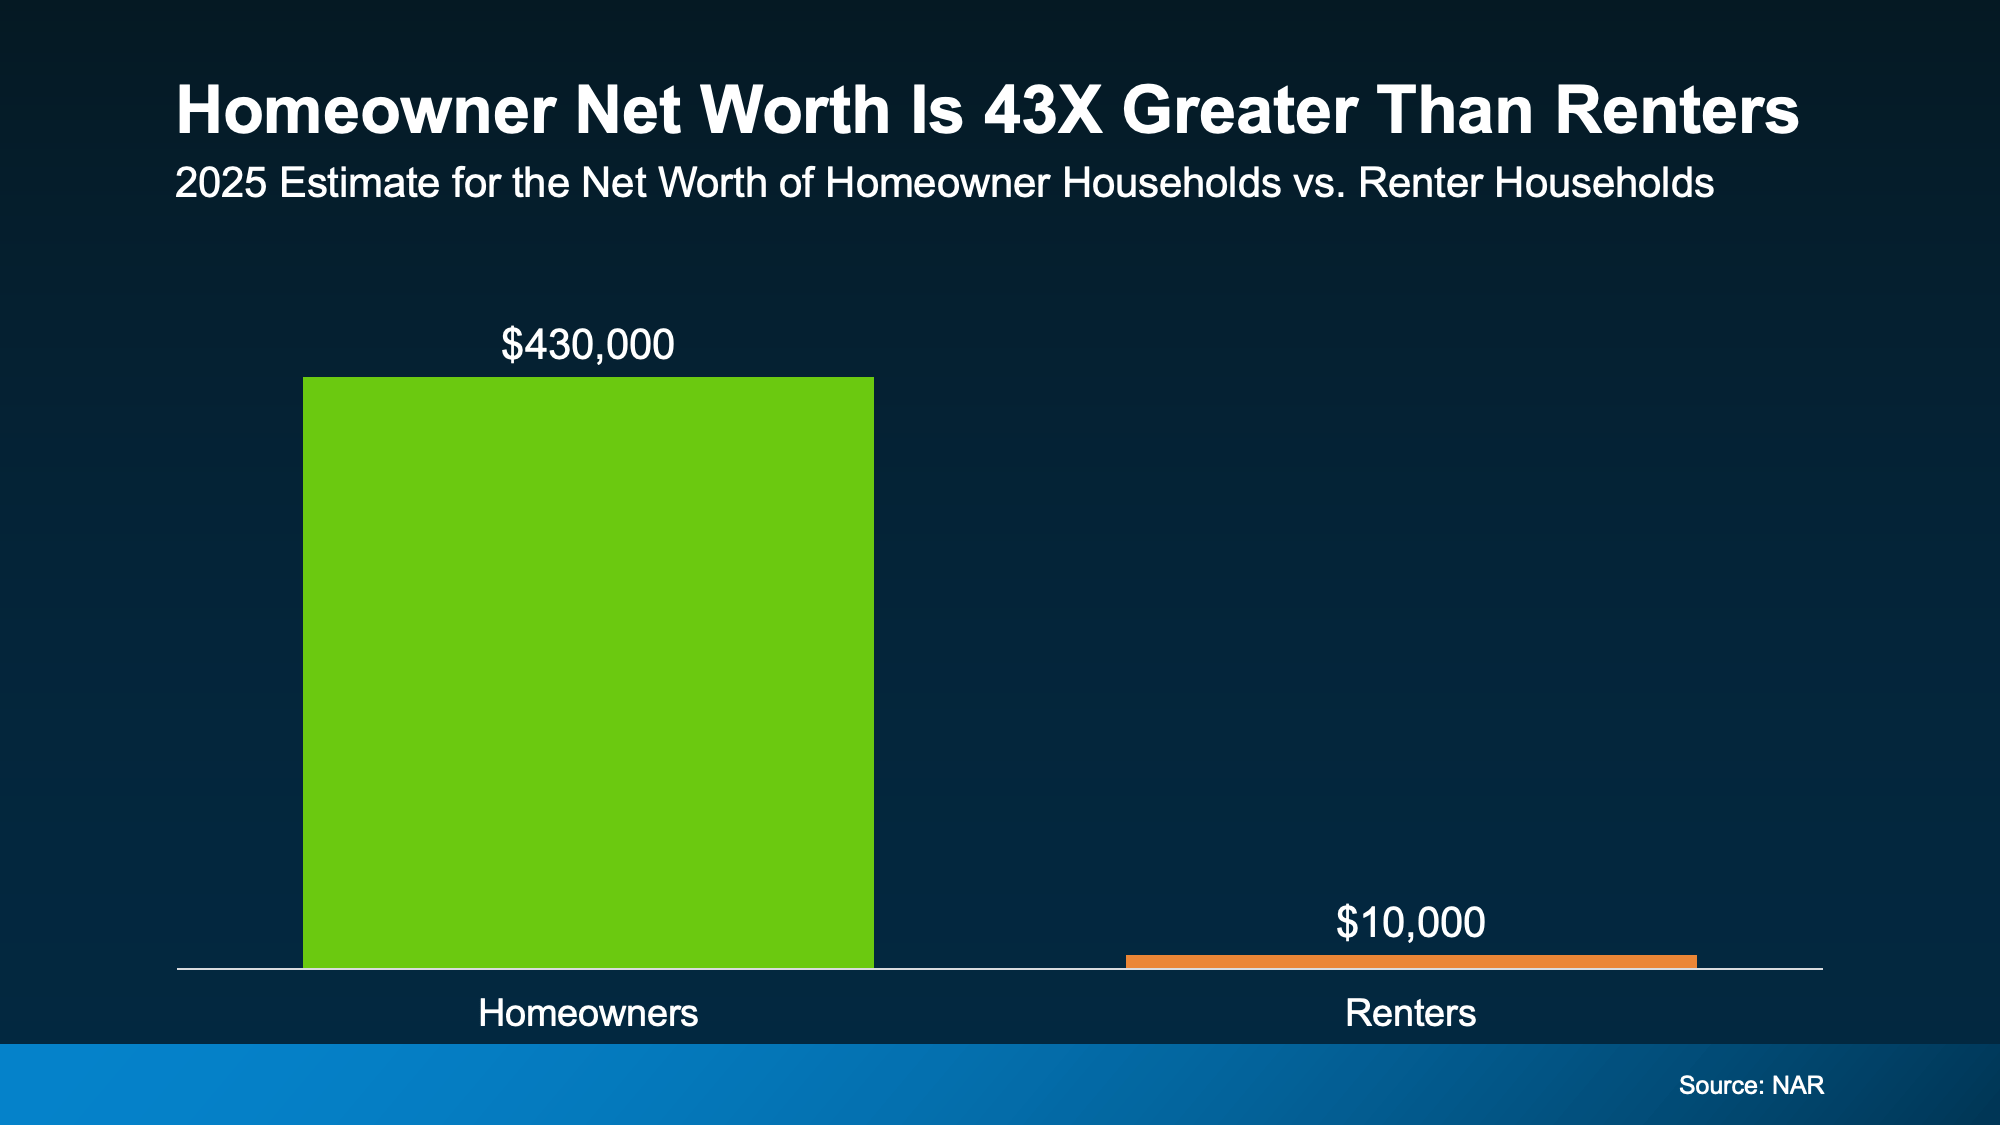
Today, the National Association of Realtors (NAR) says the average homeowner’s net worth is 43X greater than that of a renter:

a graph of a number of peopleThe dollars in the visual don’t lie. On average, here’s how net worth compares:

  • Homeowners: $430k
  • Renters: $10k

And it’s not because homeowners make wildly different decisions day to day. It’s because over time, one path builds something, and the other doesn’t.

So sure, buying comes with some upfront costs and more responsibility. But it’s basically a savings account you can live in.

The Gap Is Growing Over Time

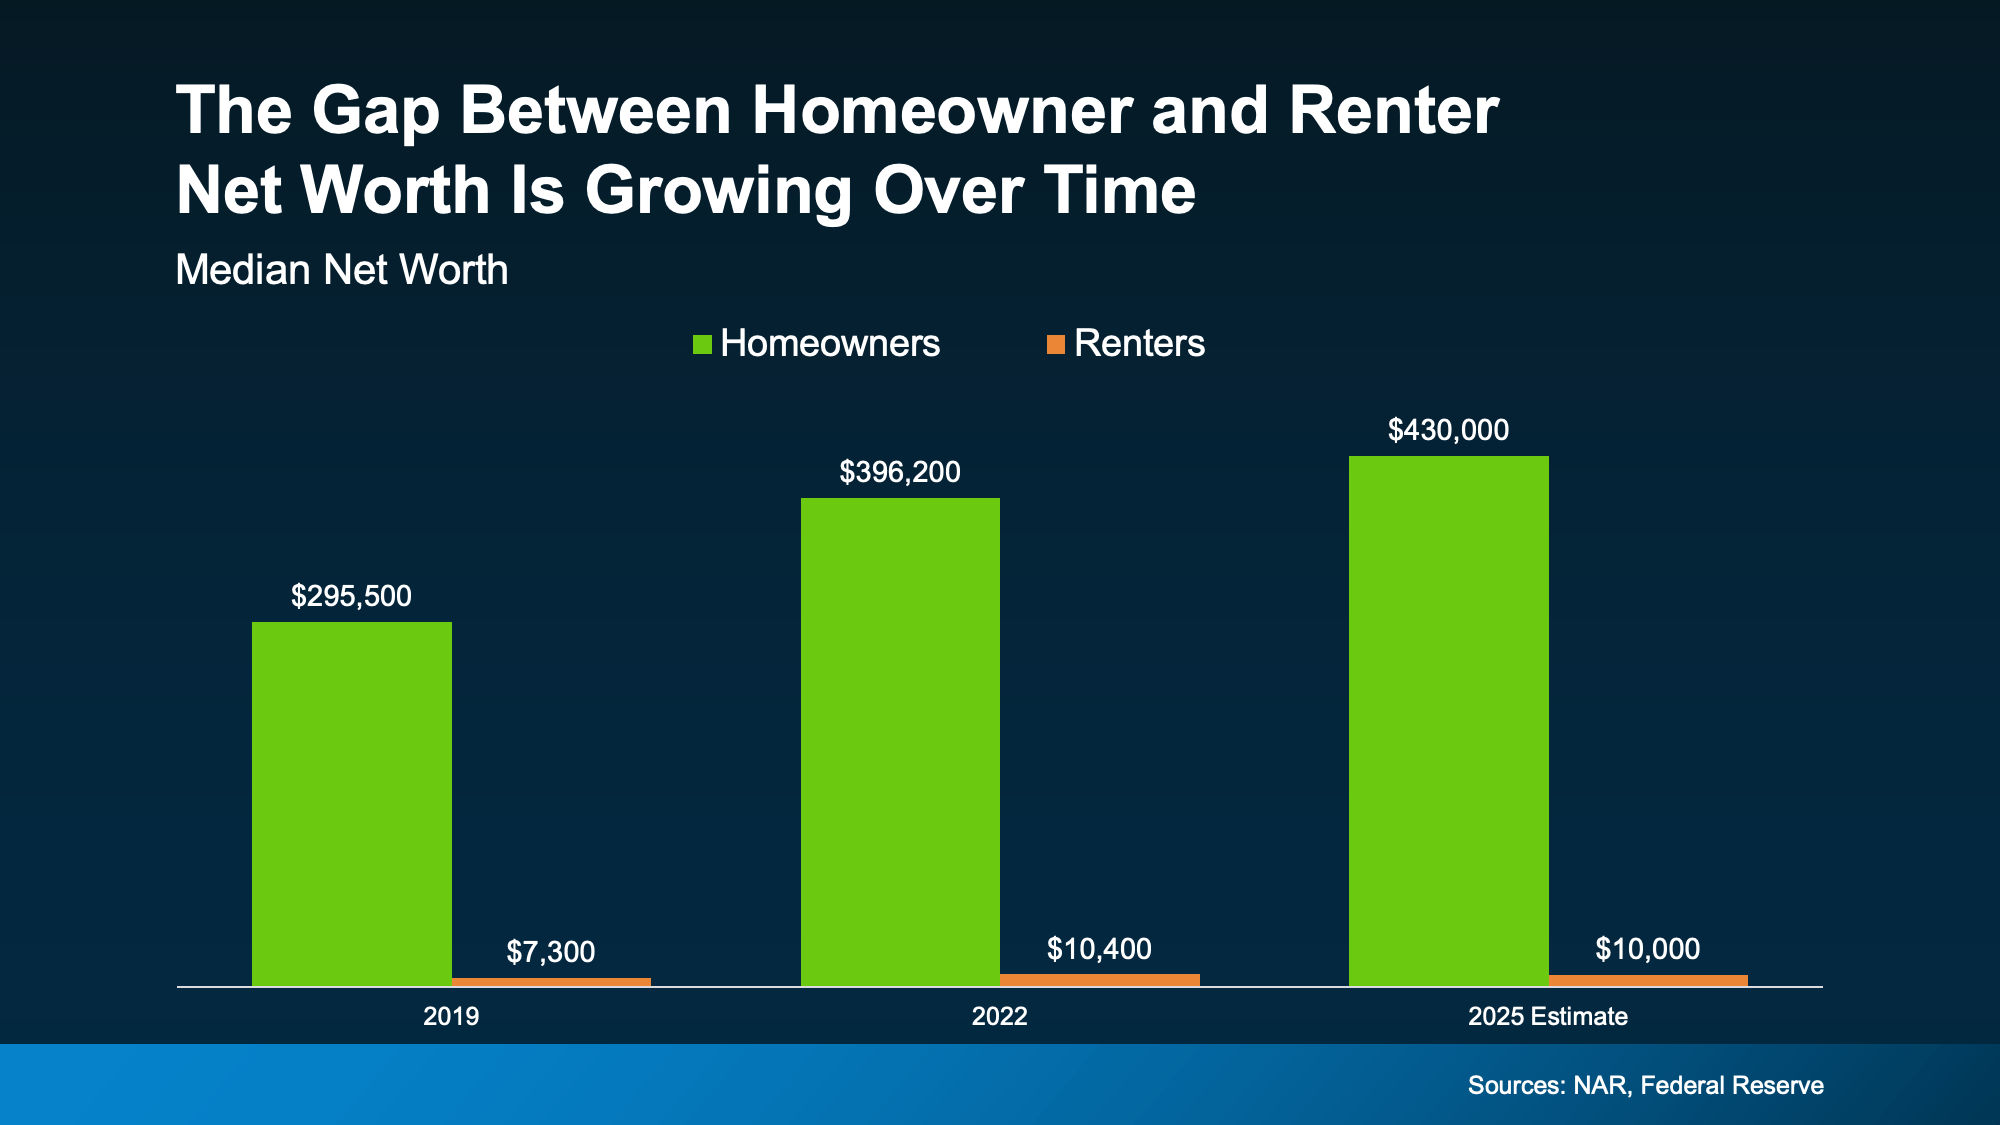
And here’s something else interesting. That net worth gap between renters and homeowners has been widening over time, not shrinking.

If you look back at the reports on net worth through the years, you can see the gap is growing as homeowners gain wealth and renters stay stuck in the rental trap (see graph below):

a graph of green and blue barsEven in 2025, when home prices were moderating, homeowners still gained even more ground. And that tells you something important:

When you can afford it and you’re ready for the responsibility, history shows buying is usually worth it in the long run. Because either way, you’re paying for someone’s mortgage and building someone’s net worth.

When you rent, it’s your landlord’s mortgage – not yours. But when you buy? Your monthly payments help build equity.

The question is: whose do you want to pay? Yours or theirs?

So, Should You Buy a Home Now?

The short answer is, it depends on your situation.

While the long-term benefits of buying are clear, that doesn’t mean the timing is right for everyone right now. And that’s okay. You should only buy a home once you’re ready and the numbers work for you.

But whether you’re looking to buy now or planning for the future, the first step is the same. You should have a quick conversation with a local real estate agent about your goals, timeline, and budget.

They can help you run the numbers and see what’s realistic. You may find buying is closer than you thought. And if not, you’ll at least know exactly what it will take to get there.

Because the sooner you have a plan, the sooner you can decide when it makes sense, instead of wondering if it ever will.

Bottom Line

Renting may feel more do-able today. But over time, it could cost you.

If you want to ditch renting and start building something for your future, it starts with a simple conversation. Connect with a real estate agent to talk about your specific goals, and explore your options – so you’re ready when the time is right for you.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Renting vs. Buying: The Numbers Might Surprise You

Renting vs. Buying: The Numbers Might Surprise You Simplifying The Market

Renting can feel like the easier choice right now. There’s no big down payment. No dealing with surprise repairs. And no long-term commitment.

But then your rent goes up again. And again. And suddenly the thing that seemed flexible starts looking… expensive, especially considering you’re not building any equity. And once that happens, it’s easy to feel a little trapped in the cycle.

That’s because there’s so much chatter today about how buying a home isn’t affordable. But the truth is, the math may work out better than you’d expect based on what’s changed recently.

Buying Is More Affordable Than Renting in Many Areas 

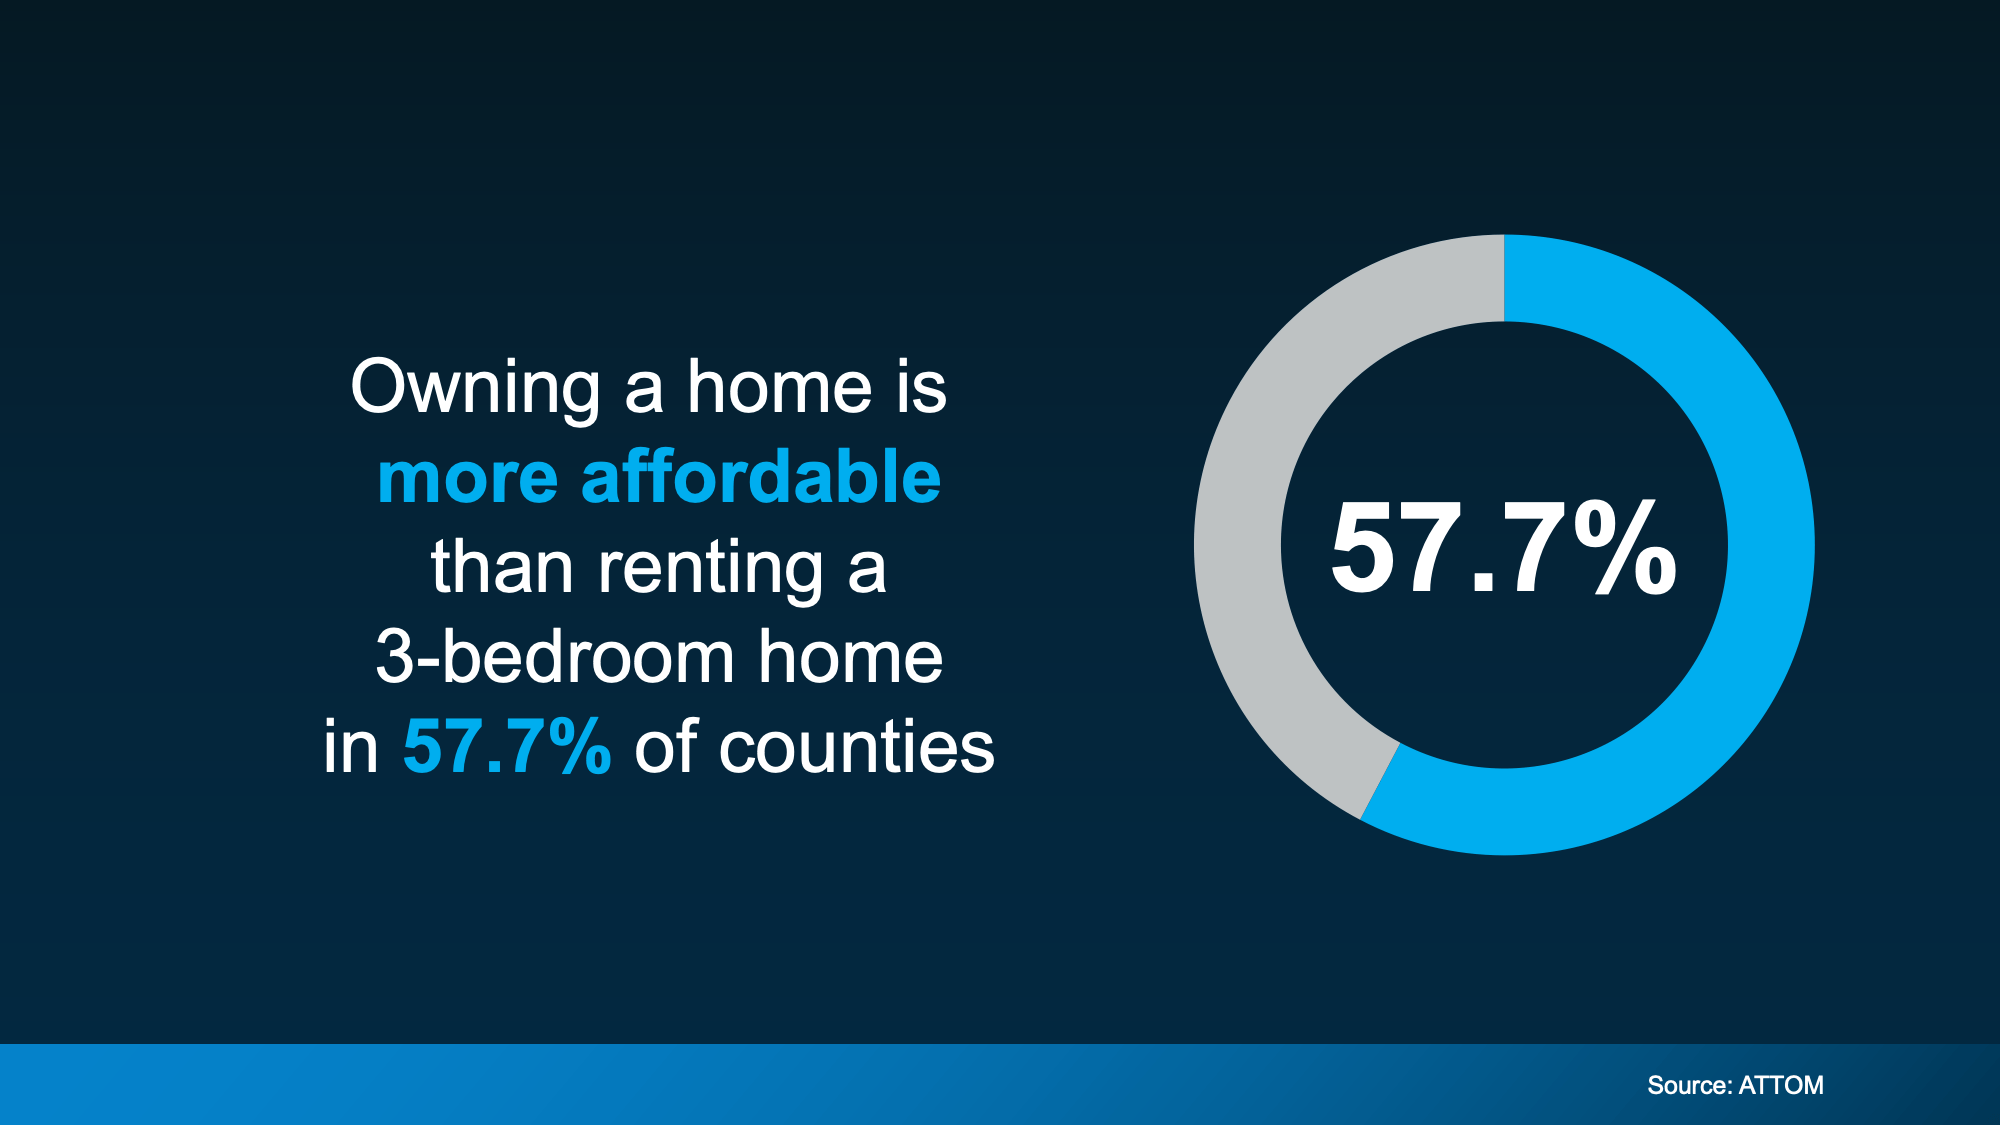
In a lot of places today, owning a home actually costs less each month than renting a 3-bedroom home. And recent data from ATTOM shows that’s true in nearly 58% of counties across the U.S. (see chart below).

And that’s after you factor in things like insurance and typical maintenance costs. 

a blue and grey circle with white textIn other words, even though it may feel like a bit of a shock, the numbers show rent often stretches monthly budgets more than owning does. That’s thanks to slower home price growth, more homes for sale, and monthly mortgage payments starting to ease as rates come down.

Affordability Still Varies by Region

Now, even though nationally the balance has shifted, that doesn’t mean buying is more affordable in every market or for every renter.

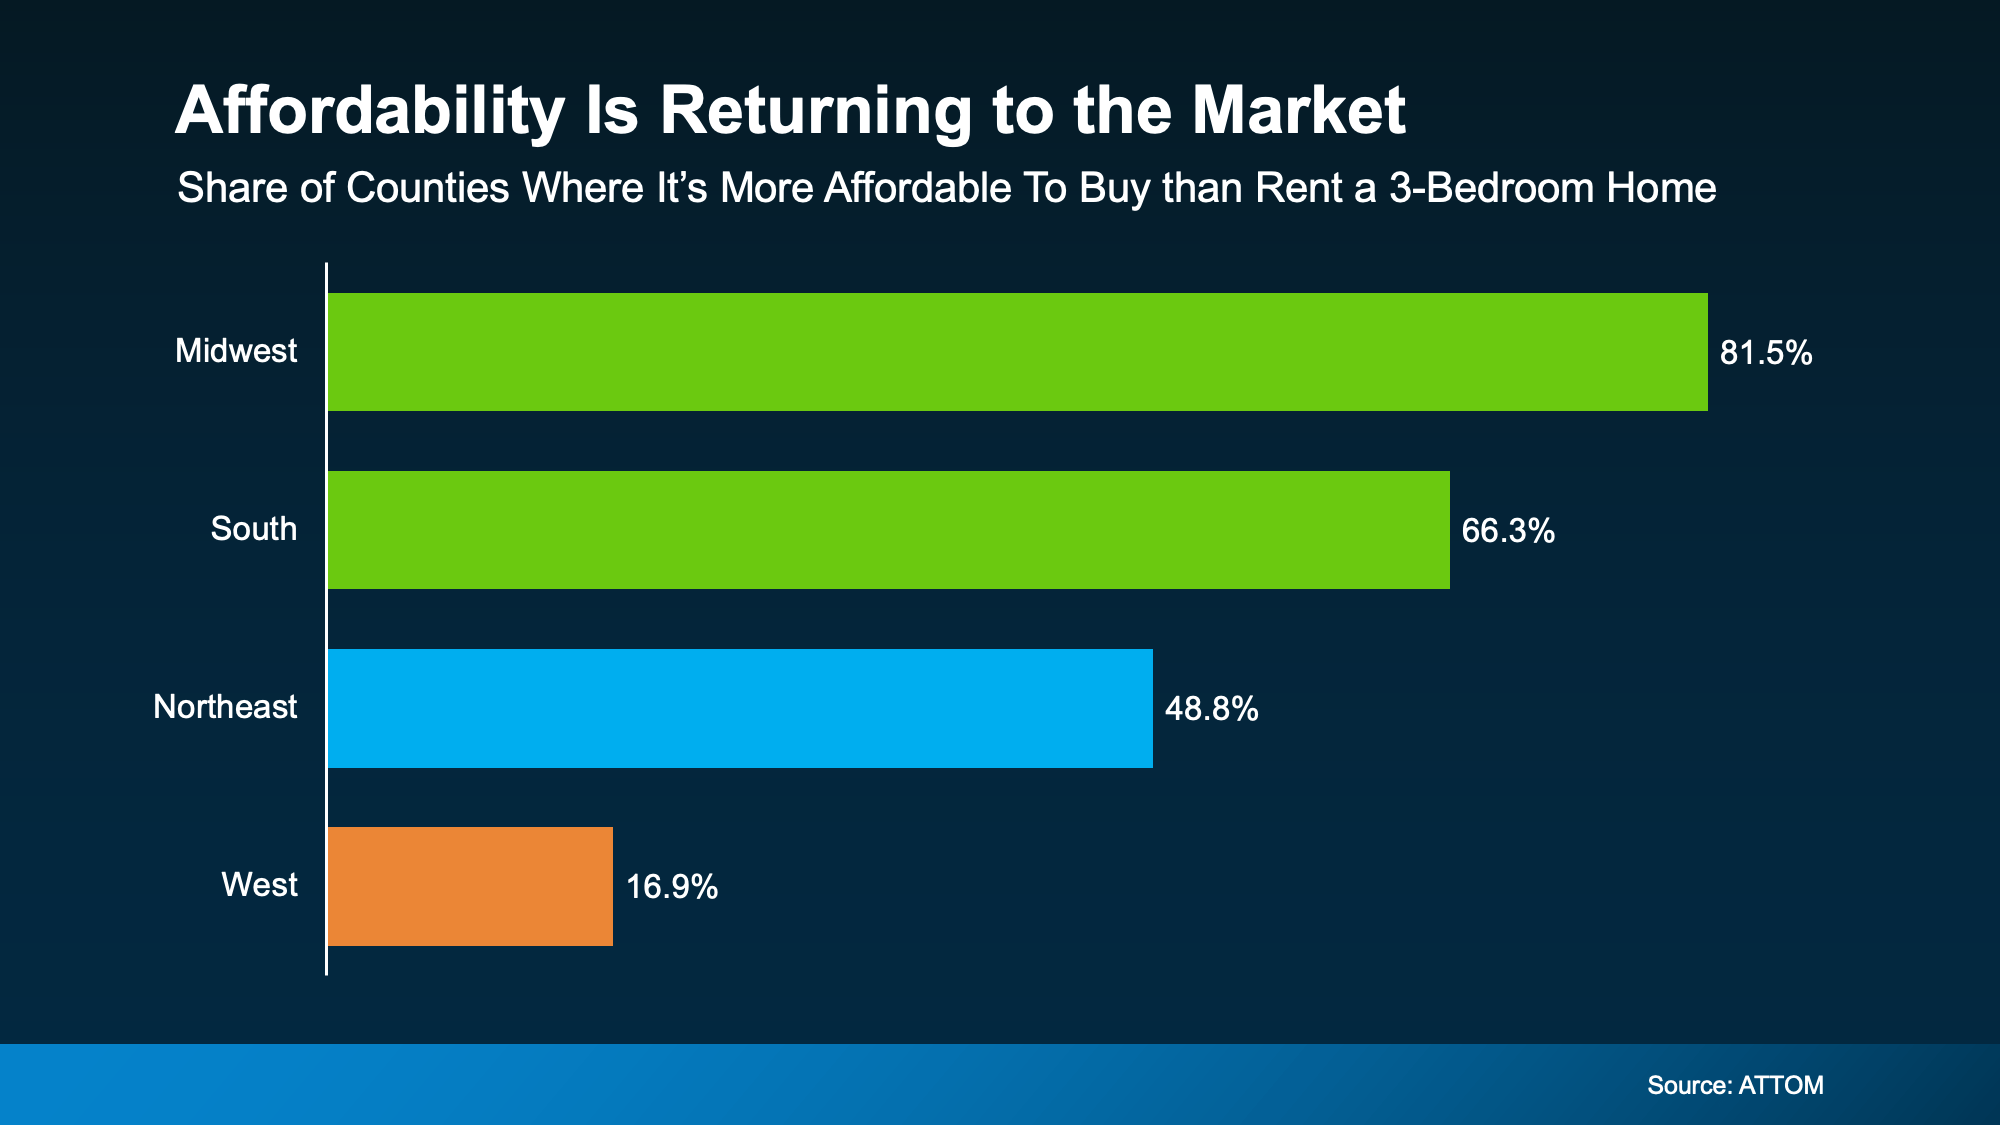
While buying is more affordable than renting in nearly 58% of counties nationwide, that share looks different depending on your region (see graph below):

a graph of a market

The biggest improvement is happening in the Midwest and South. But if you’re living in the West, things could still feel tight.

The takeaway? How affordable buying is really depends on where you live. And the only way to know how this plays out where you live is to look at the numbers locally.

So, What’s Still Holding Buyers Back? 

Maybe you’re nodding along so far but thinking, “Okay, but I still can’t afford the upfront costs.” If that’s your reaction, you’re not the only one.

For many renters, the biggest hurdle isn’t the monthly payment alone. It’s the down payment, too.

But you’re not out of options. Here’s the part most people don’t hear enough about: there are thousands of down payment assistance programs available across the country, and many buyers qualify without realizing it.

And the average benefit? Roughly $18,000.

That kind of support can help cover part of your down payment or closing costs, which means you may not need to save nearly as much as you think to get started.

When you combine that with monthly payments that may work better than expected, especially as rates continue to ease and prices cool, buying may feel far more realistic than it looks at first glance.

Bottom Line

The point isn’t that everyone should rush out and buy a home tomorrow.

It’s that renting isn’t always the more affordable option people assume it is – and buying may be more realistic than it feels once you look at the full picture.

If you’re renting and feeling stuck in the “someday” loop, it might be worth a simple conversation with a local real estate agent or lender. Just a chance to see what’s possible and whether it makes sense for you.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
The Credit Score Myth That’s Holding Would-Be Buyers Back

The Credit Score Myth That’s Holding Would-Be Buyers Back Simplifying The Market

Would-be homebuyers aren’t sitting on the sidelines because they don’t want to buy. They’re sitting out because they think they can’t. And sometimes, it’s their credit score that’s holding them back.

According to a Bankrate survey, 2 out of every 5 (42%) Americans believe you need excellent credit to qualify for a mortgage. That may be why, when renters are asked why they don’t own yet, “my credit isn’t good enough” comes up often.

Maybe you’re in the same boat. You look at your score, see it’s not where you want it to be, and assume buying your first place just isn’t realistic right now.

But here’s what you need to know.

Even though a lot of people assume you need flawless credit to buy a house, that’s not necessarily the case.

You Don’t Need Perfect Credit To Buy a Home

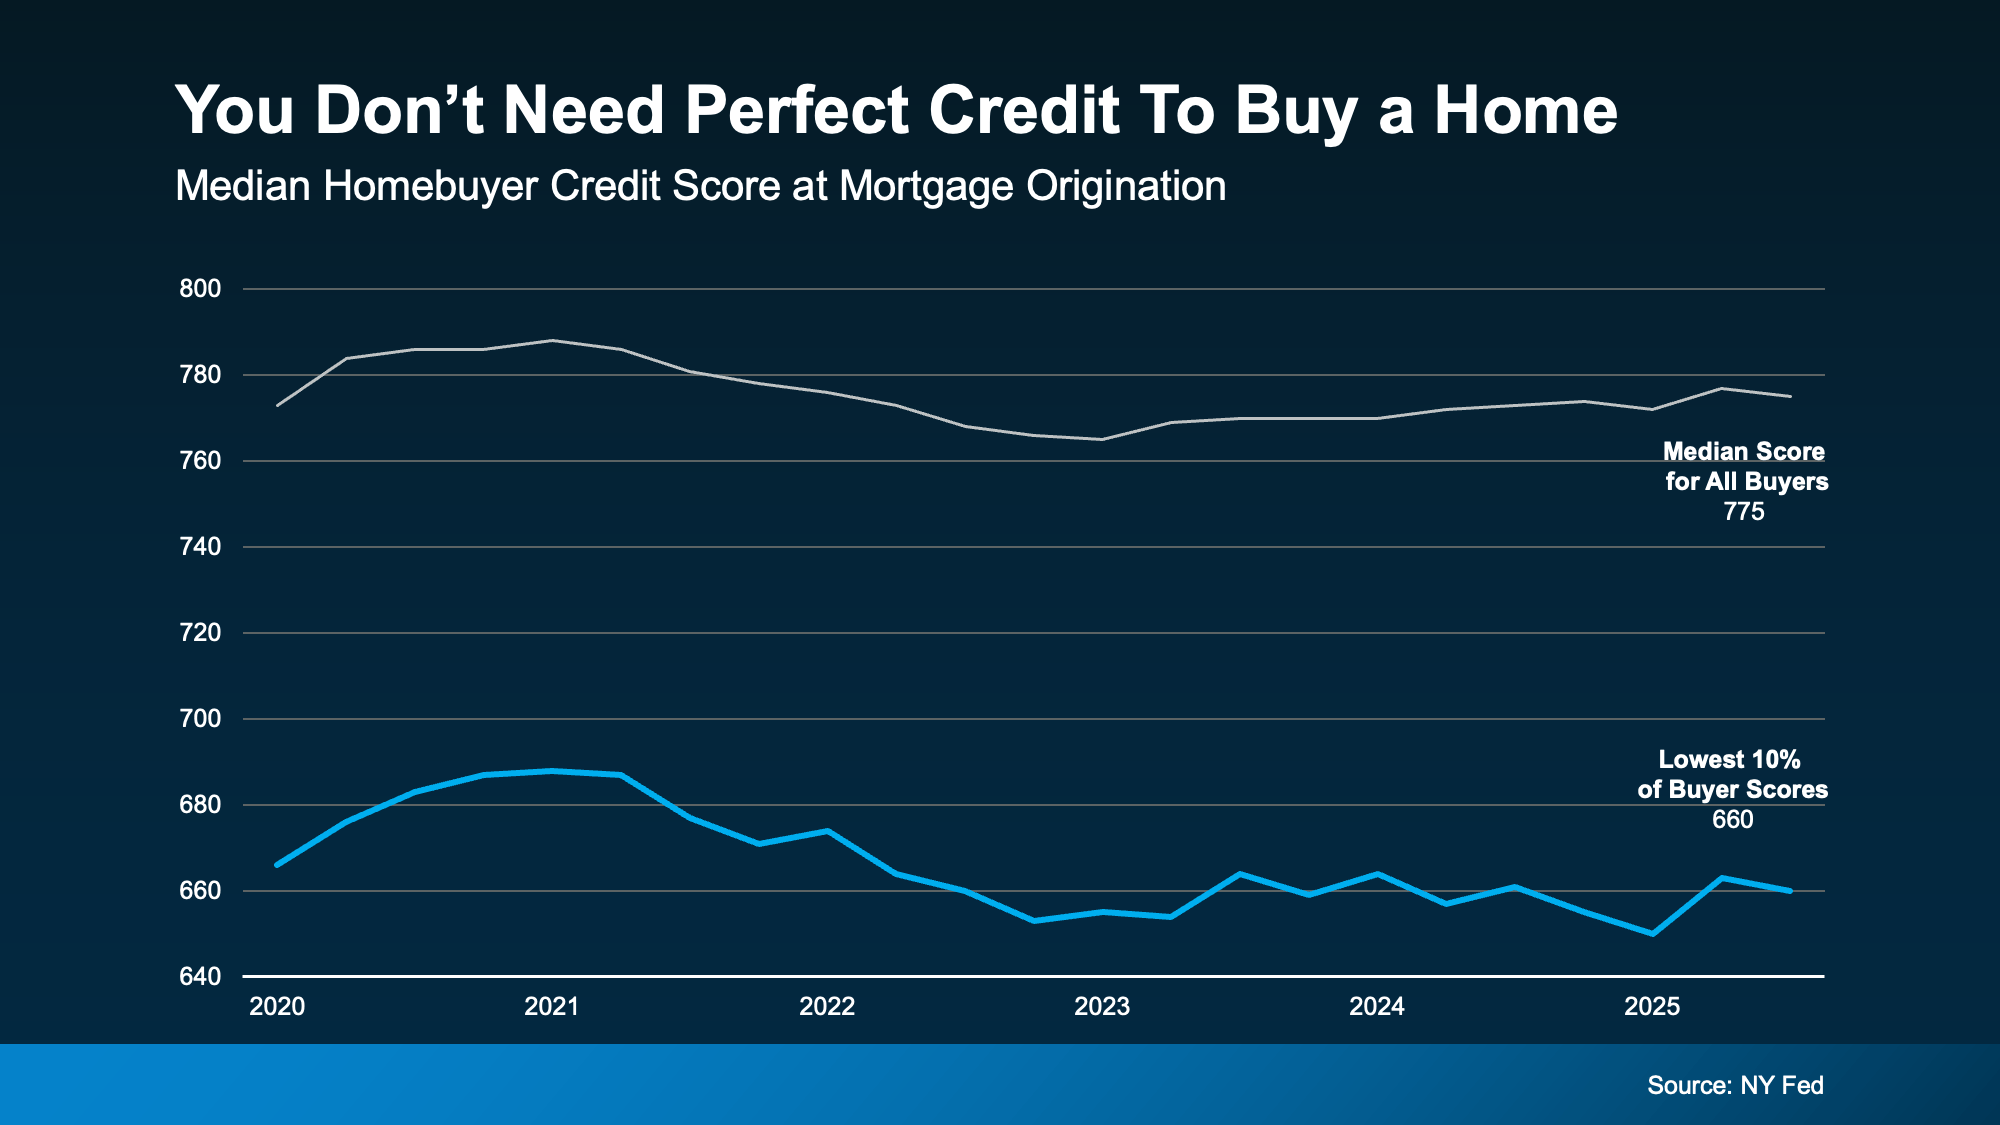
So, where’s this myth come from? Part of the confusion stems from the fact that the typical homebuyer today does have a fairly strong credit score. In fact, according to data from the NY Fed, the median credit score for all buyers is 775.

But that doesn’t mean you need a score that high to qualify.

Looking at recent homebuyers, a number were able to get a mortgage with scores below that threshold. Data shows 10% of scores were around 660. Which means some were higher than that and some were lower, but the median in that lowest 10th percentile was around that range (see graph below):

a graph showing a line graphSo, even if your score isn’t as high as you want, that doesn’t automatically close the door. FICO explains there is no universal credit score you absolutely have to have when buying a home:

“While many lenders use credit scores like FICO Scores to help them make lending decisions, each lender has its own strategy, including the level of risk it finds acceptable. There is no single ‘cutoff score’ used by all lenders, and there are many additional factors that lenders may use . . .”

The best thing to do is to talk to a trusted lender to see what’s possible for you. Because a portion of buyers are buying with scores in the 600s – and maybe that means you can too.

Bottom Line

Your credit score is important. But that doesn’t mean it has to be perfect.

If credit has been the reason you’ve been waiting to buy a home, it might be time to take another look at your options. If you want help understanding where you stand and what your next step could be, connect with a local lender.

You don’t need to have everything figured out to start the conversation.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Turning a House Into a Home: The Benefits You Can Actually Feel

Turning a House Into a Home: The Benefits You Can Actually Feel Simplifying The Market

There’s a lot of conversation about home prices, mortgage rates, and affordability right now – and those things are important. But if you’re thinking about buying a home, it’s worth remembering something the headlines rarely talk about: people don’t buy homes just for financial reasons. They buy them for their lives.

Because while homeownership can absolutely be a smart long-term financial move, it also comes with some emotional benefits spreadsheets just can’t capture. Maybe that’s why a 2025 survey from Fannie Mae notes:

“Consumers were twice as likely to mention lifestyle benefits (67%)—like security, customization, and outdoor space—than financial benefits (34%) when explaining why their homes have become more important in recent years.”

Here are a few reminders of what owning a home gives you that renting never will.

1. A Milestone You Get To Be Proud Of

Buying a home is a big deal. First home, fifth home – it doesn’t matter. It’s a moment you’ll remember. And when you finally get those keys and walk through the door, that feeling of “I did this” hits different. It’s not just a purchase. It’s an accomplishment.

2. A Place That Feels Like Your Reset Button

Life is busy. Having a place that’s truly yours where you can shut the door, take a breath, and settle into your own routine is something renters rarely talk about until they finally experience it. Home becomes the place you go to recharge, not just the place your mail is delivered.

3. Space That Fits the Way You Actually Live

Need a quiet corner for work calls? A backyard big enough for the dog that thinks it’s a person? A shorter drive to see the people who are most important to you? When you own, you get to choose a space that fits your life now and where it’s heading – and it just feels right.

4. Freedom To Make It 100% Yours

Want to paint the kitchen navy? Go for it. Thinking about a wall of floating shelves or a bold wallpaper moment? Do it. Need space for a home gym or a reading nook? Make it happen. Homeownership gives you the freedom to shape your space instead of asking for permission to change it.

Bottom Line

Buying a home isn’t only about dollars and data points – it’s about building a life you love.

So, if you’re thinking about a move in 2026, keep the emotional side in the conversation too. And when you’re ready to explore your options, reach out to a trusted local agent who can guide you through the process with clarity and confidence.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Why Buying a Home Still Pays Off in the Long Run

Why Buying a Home Still Pays Off in the Long Run Simplifying The Market

Renting can feel much less expensive and much simpler than buying a home, especially right now. No repairs, no property taxes, no worrying about mortgage rates – you just pay the bill and move on with your life.

But here’s the part people don’t talk about enough: renting doesn’t help you build your financial future. Meanwhile, homeowners grow their net worth just by owning a home.

So, if you’ve been wondering whether buying is still worth it, the long-term math is clearer than you might think.

Renting vs. Owning: How the Costs Really Compare

Let’s break down one of the key differences between renting and buying. When you rent, your payment goes to your landlord, and then it’s gone. When you own, part of your payment comes back to you in the form of equity (the wealth you build as the value of your home increases, and you pay down your home loan).

So, while renting may seem more affordable now, you have to remember it comes at a long-term cost: you’re not building your wealth. And it turns out, that’s a bigger miss than you may expect.

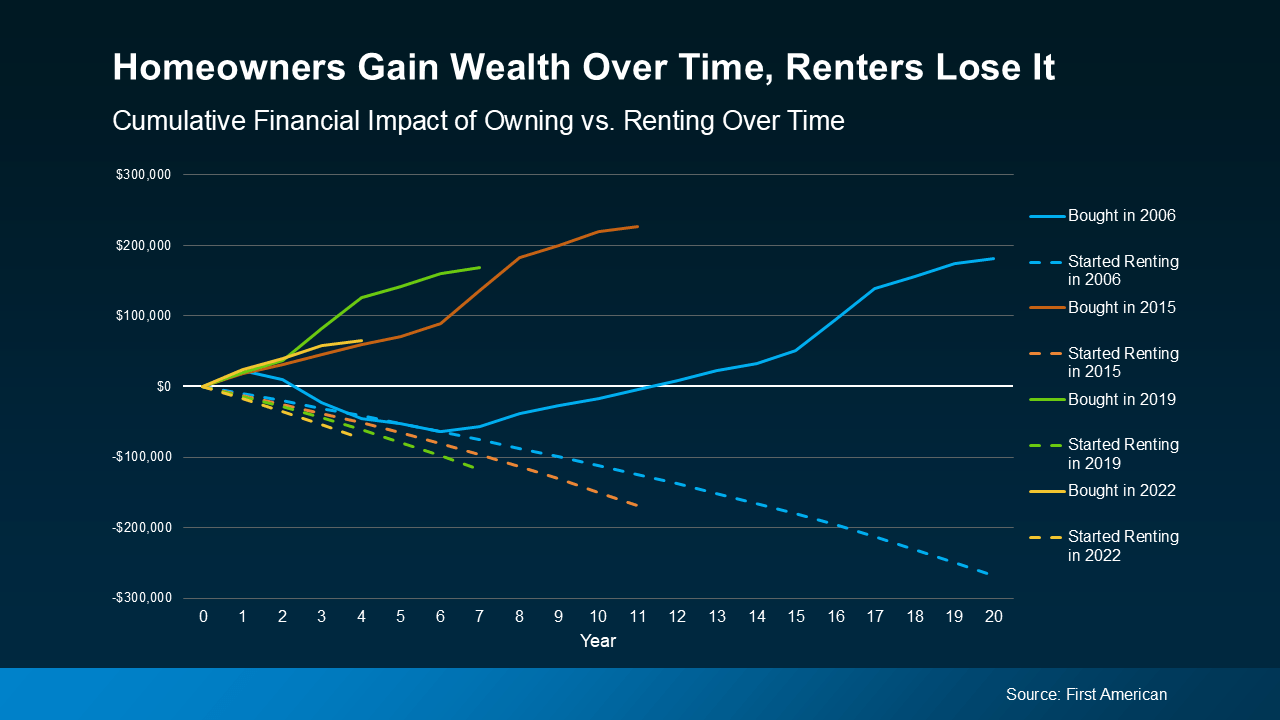
First American recently analyzed the long-term financial impact of renting versus owning a home. They compared mortgage payments, property tax, insurance, repairs, and maintenance against the equity gained through home price appreciation and paying down the mortgage. And they did that during several different time frames to see if it tells a consistent story:

  • 2006: the start of the housing bubble
  • 2015: 10 years ago
  • 2019: just before the pandemic (the last normal years in the market)
  • 2022: when mortgage rates jumped

In each time frame, two things were true: renters ended up losing money over time. And homeowners gained it.

Here’s some data so you can see this play out. Each color represents one of the key time frames. The solid lines show the buyer’s investment over time and how their net worth actually grew the longer they lived in their home. The dashed line represents the renter’s investment. In the end, they sank more and more cash into renting without gaining any financial benefit.

a graph of a graph showing the impact of owning vs renters lossThe takeaway is simple: time in a home builds wealth. Time renting doesn’t.

Basically, homeowners come out ahead. And the analysis shows that’s even after you factor in the other expenses that come with homeownership, like insurance, repairs, and property taxes. And that’s the case for every time frame First American looked into.

On the flip side, renters spent money on their rent, but didn’t gain any long-term financial benefit. That’s true no matter what window of time you look at in the study.

Now, that doesn’t mean buying always beats renting in the short term. But the longer you own, the wider the wealth gap becomes.

Affordability Is Starting To Improve

You might still be thinking, “Okay, but buying feels out of reach for me right now.” Fair.

The past few years haven’t been easy for buyers. But things are starting to shift. Mortgage rates have come down this year, home prices are softening, and incomes have been rising. And according to Zillow, typical monthly payments have gotten a little easier compared to this time last year. Not by a lot, but enough to make a difference.

No, buying isn’t suddenly easy. But it is easier than it was just a few months ago. And in the long run, history shows it’s worth it. 

Bottom Line

Renting may feel less expensive today, but owning is what builds real wealth over time. And with affordability starting to improve, the path to homeownership may be opening up more than you think.

If you’re curious what buying could look like for you, connect with a local real estate who can help you plan your next move, pressure-free.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
The Truth About Down Payments (It’s Not What You Think)

The Truth About Down Payments (It’s Not What You Think) Simplifying The Market

Buying a home is exciting… until you start thinking about the down payment. That’s when the worry can set in.

“I’ll never save enough.”

“I need a small fortune just to get started.”

“I guess I’ll just rent forever.”

Sound familiar? You’re not alone. And you’re definitely not out of luck.

Here’s the thing: a lot of what you’ve heard about down payments just isn’t true. And once you know the facts, you might realize you’re a lot closer to owning a home than you think.

Let’s break it all down and bust some big down payment myths while we’re at it.

Myth 1: “I need to come up with a big down payment.”

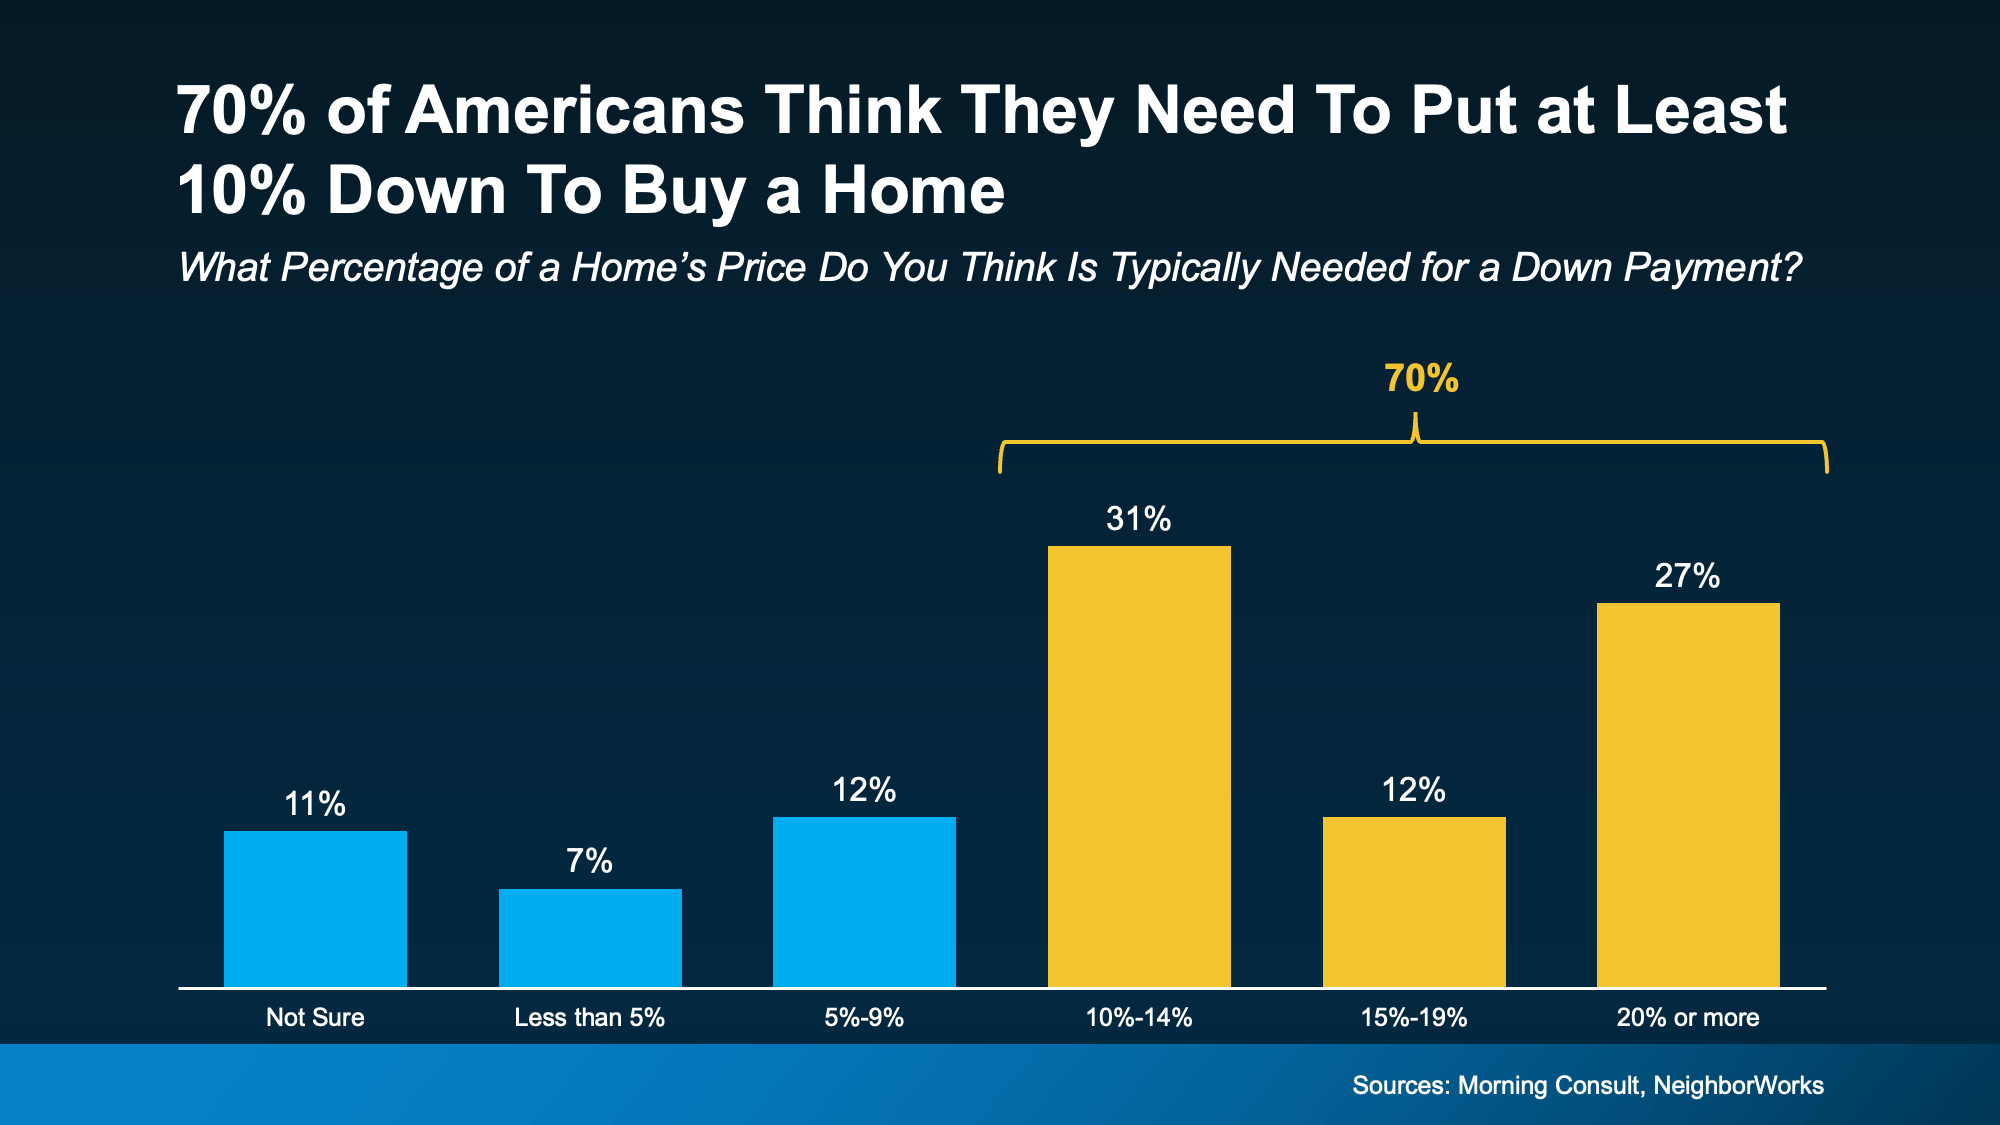
This one stops a lot of people in their tracks. A recent poll from Morning Consult and NeighborWorks shows 70% of Americans think they need to put at least 10% down to buy a home. And 11% aren’t sure what’s required at all (see graph below): 

a graph of a number of blue and yellow squaresThe truth? According to the National Association of Realtors (NAR), the typical down payment for first-time buyers has been between 6% and 9% since 2018. But there’s more to the story. If you qualify for an FHA loan, you may only need to put 3.5% down. And VA loans typically don’t require a down payment at all. So, there are options out there that can really make a difference for some buyers.

Myth 2: “It’ll take forever to save up for a down payment.”

Sure, saving can take time. But it may not have to be as long as you think. In many states, reaching your goal can happen faster than you might expect, especially when you know your budget and have a clear savings plan.

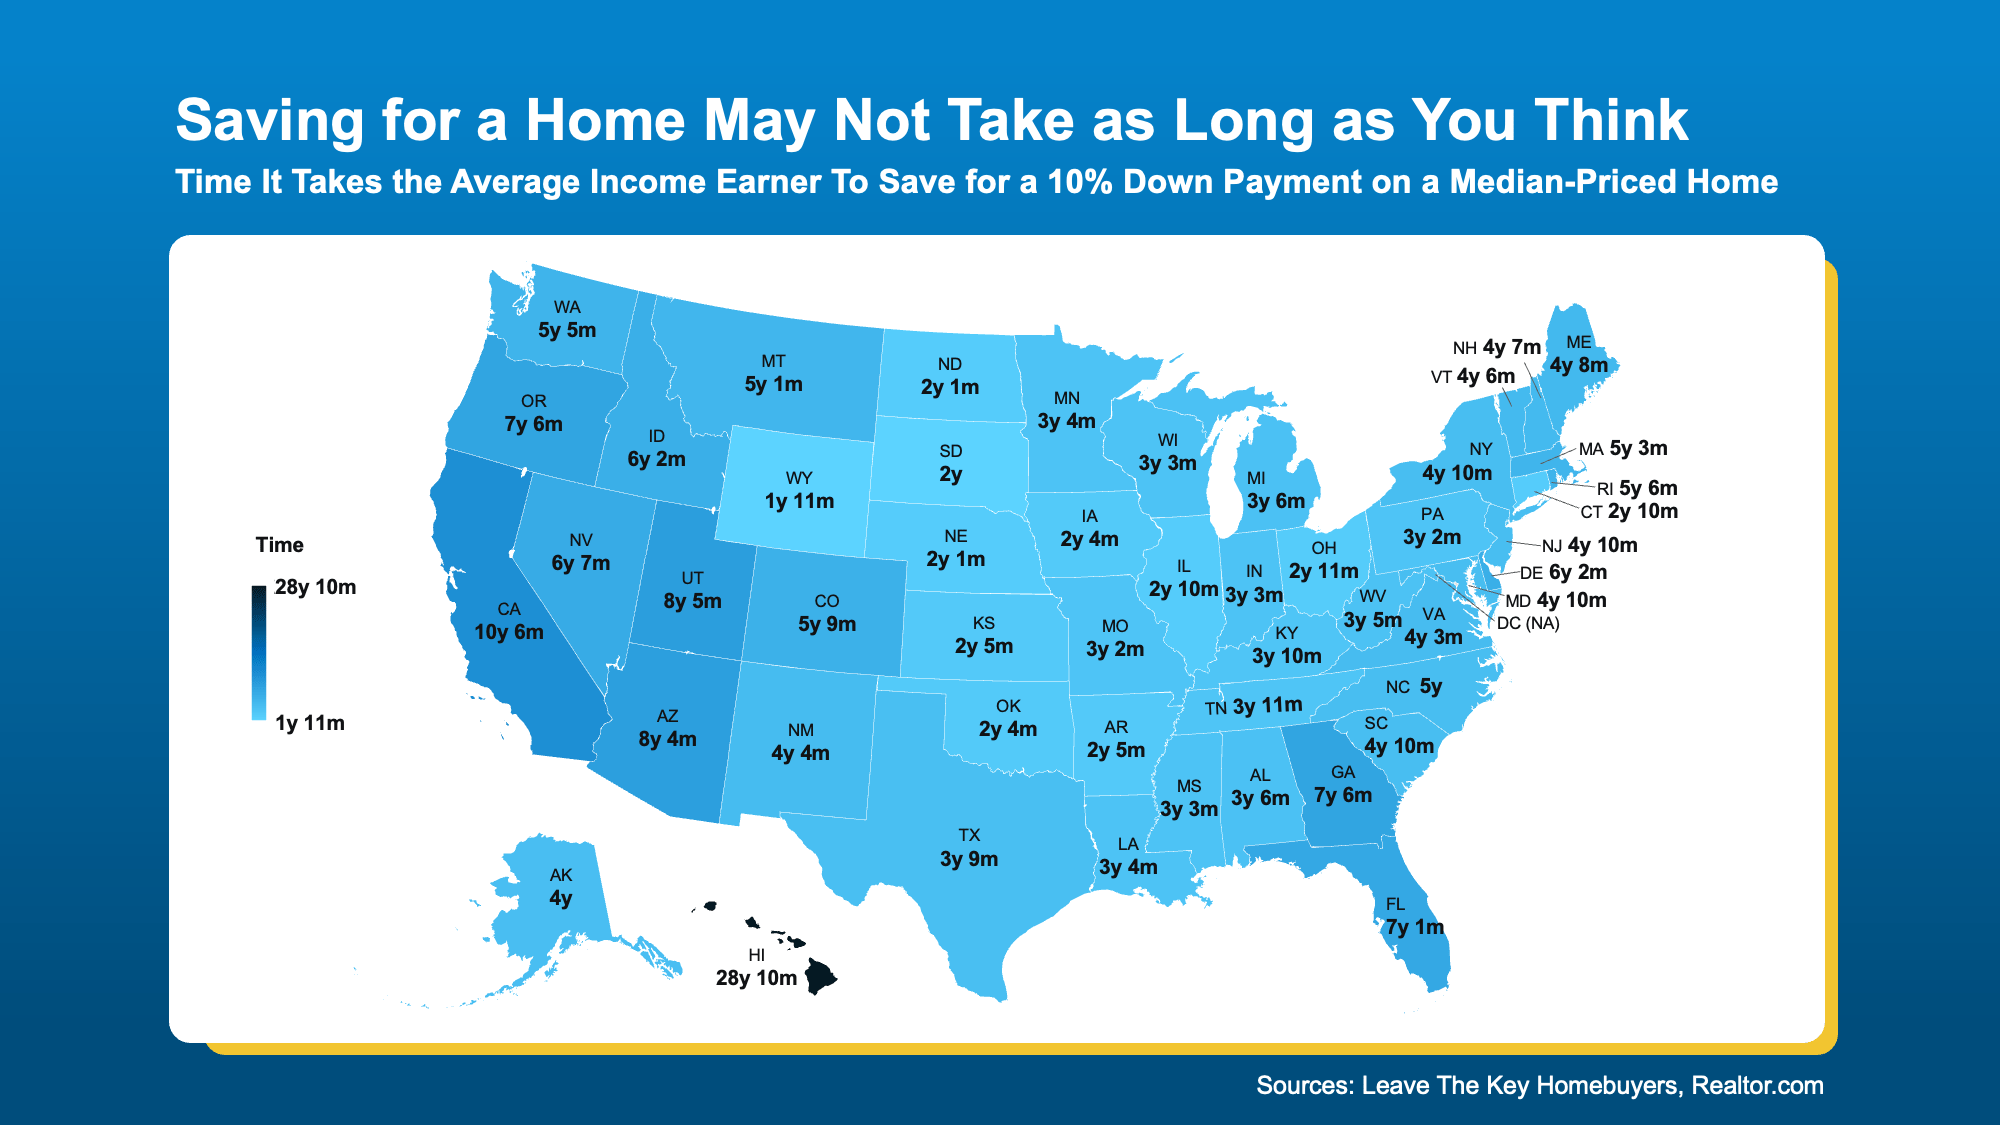
According to a new study, the amount of time varies depending on where you live. The map below shows, on average, how many years it takes to save up for a 10% down payment based on typical home values and income levels in each state (see map below):

But remember, in most cases you won’t even need a down payment as large as 10%. Plus, no matter how much money you end up putting down, it won’t all have to come out of your pocket. Here’s why.

Myth 3: “I have to do it all on my own.”

This is one of the biggest myths of all. The reality is, there are thousands of down payment assistance programs out there, and the same poll from Morning Consult and NeighborWorks shows 39% of people don’t even know about them. That means a lot of potential homebuyers could already be closer to homeownership – they just don’t realize it. 

These assistance programs are designed to help people like you who are ready to own a home but just need a little support getting started. As Miki Adams, President at CBC Mortgage Agency, explains:

“With high interest rates and soaring home prices, down payment assistance is more essential than ever.”

Bottom Line

If you’ve been putting off buying a home because the down payment feels like too much to tackle, talk to a local real estate agent. You may not need as much as you think, and there are plenty of resources out there, so you don’t have to do it alone. You just need an expert to point you in the right direction.

If the down payment wasn’t the thing holding you back, would you be ready to start your home search?

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida