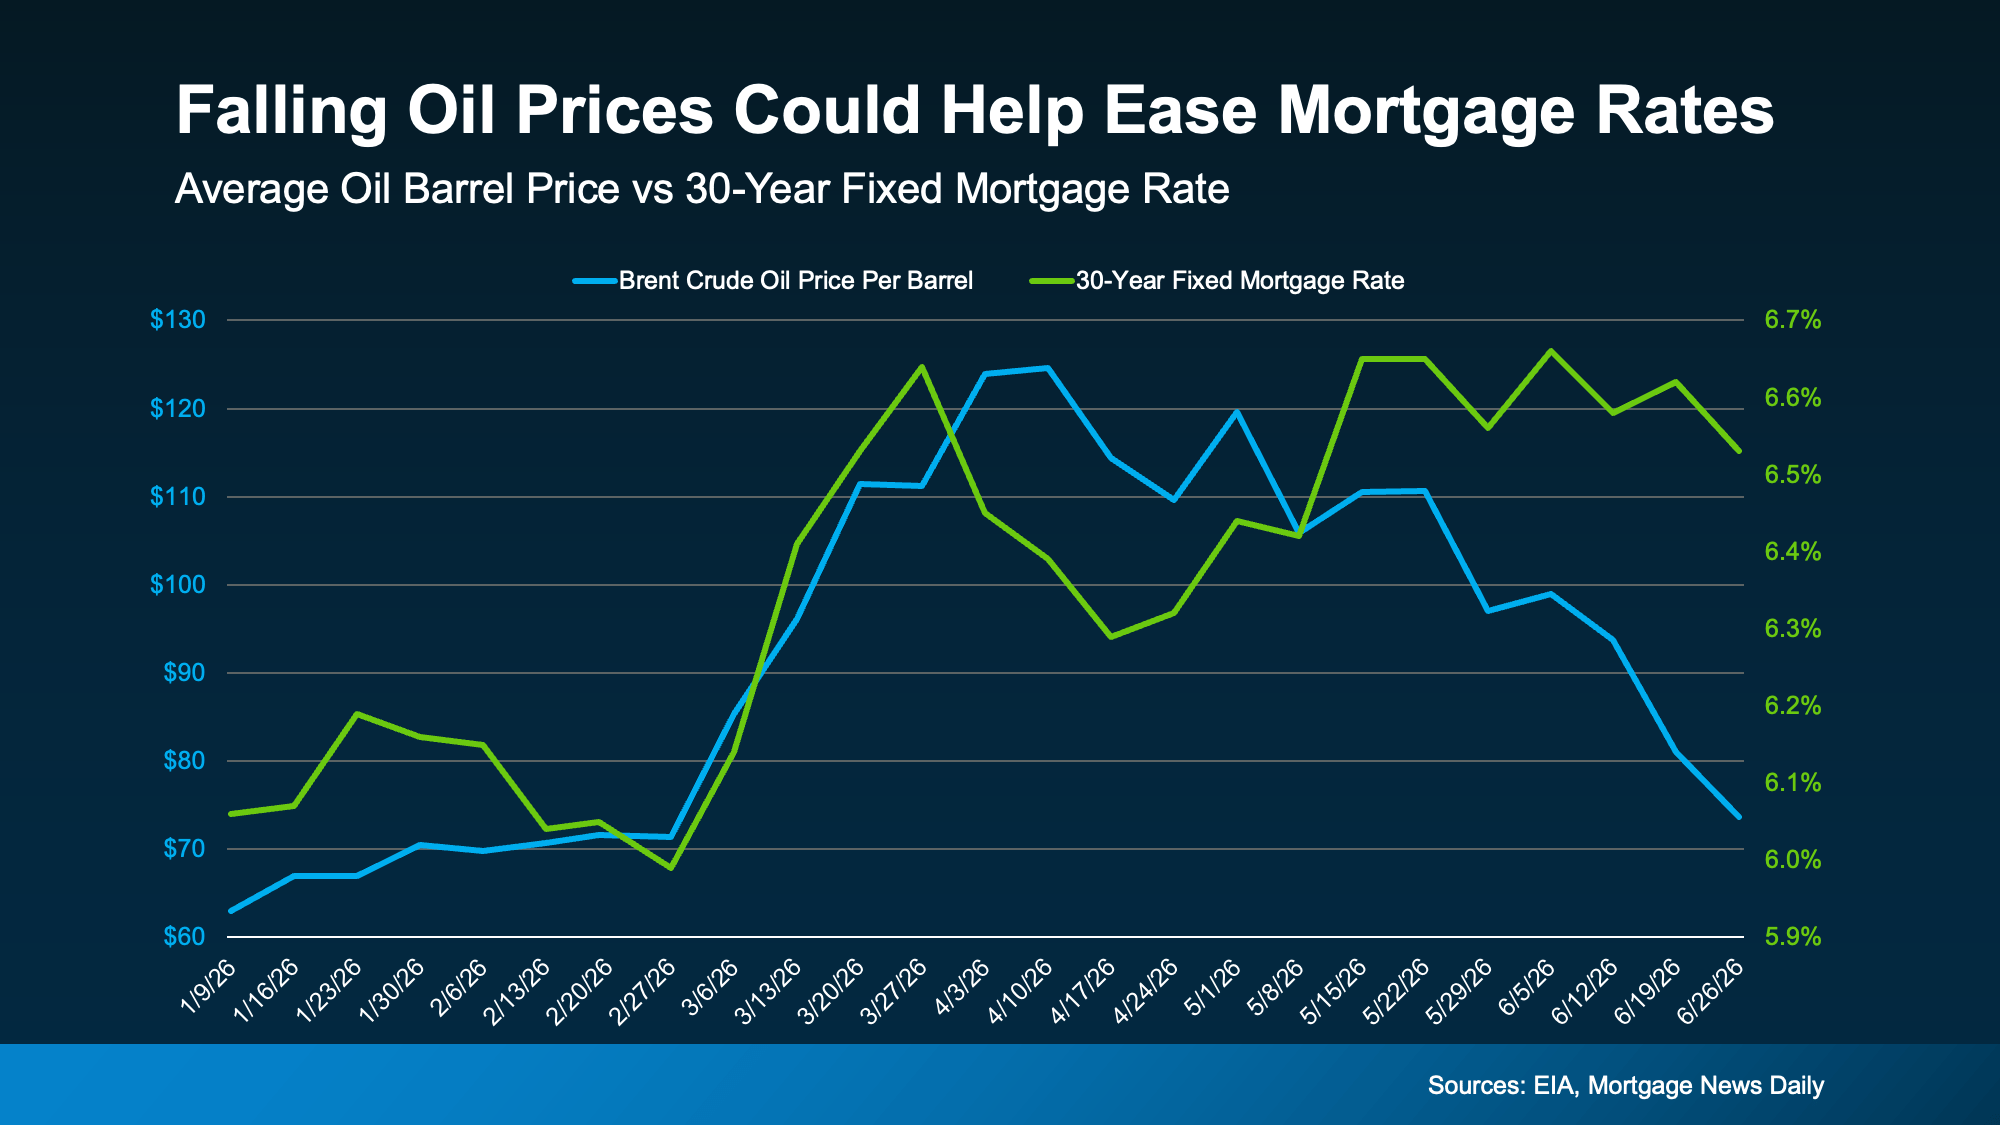Available 7 Days/Week       MON - FRI  8am - 7pm       SAT - SUN  10am – 6pm
Call us (407) 955-4575
Apply Now

Category: Mortgage Rates

View daily mortgage and refinance interest rates for a variety of mortgage products, and learn how we can help you reach your home financing goals. Lower Your Monthly Payments. Compare Rates Now! What Else Can You Afford When You Lower Your Monthly Mortgage Payment? Pre-Vetted Lenders. Apply Faster. Real Rates. Objective & Free. Skip the Bank.

Today’s Market Could Be a Win for Veterans Looking To Buy a Home
Today's Market Could Be a Win for Veterans Looking To Buy a Home Simplifying The Market

If you’re a veteran or active-duty service member who’s been hoping to buy a home, you may have more going for you in today’s housing market than you realize.

VA home loans already come with some pretty powerful benefits. But now, with more homes for sale and buyers having more room to negotiate in many markets, those benefits could go even further.

And if you’ve ever heard that buying with a VA loan is harder, takes longer, or puts you at a disadvantage, there’s something else you should know… a lot of what people believe about VA loans simply isn’t true.

The Benefits of VA Home Loans 

Today, nearly 4 million service members and veterans have an active VA home loan. And according to the Department of Veterans Affairs (VA), more than 343,000 homes were purchased using VA loan benefits in its most recent reported fiscal year. And it’s easy to see why.

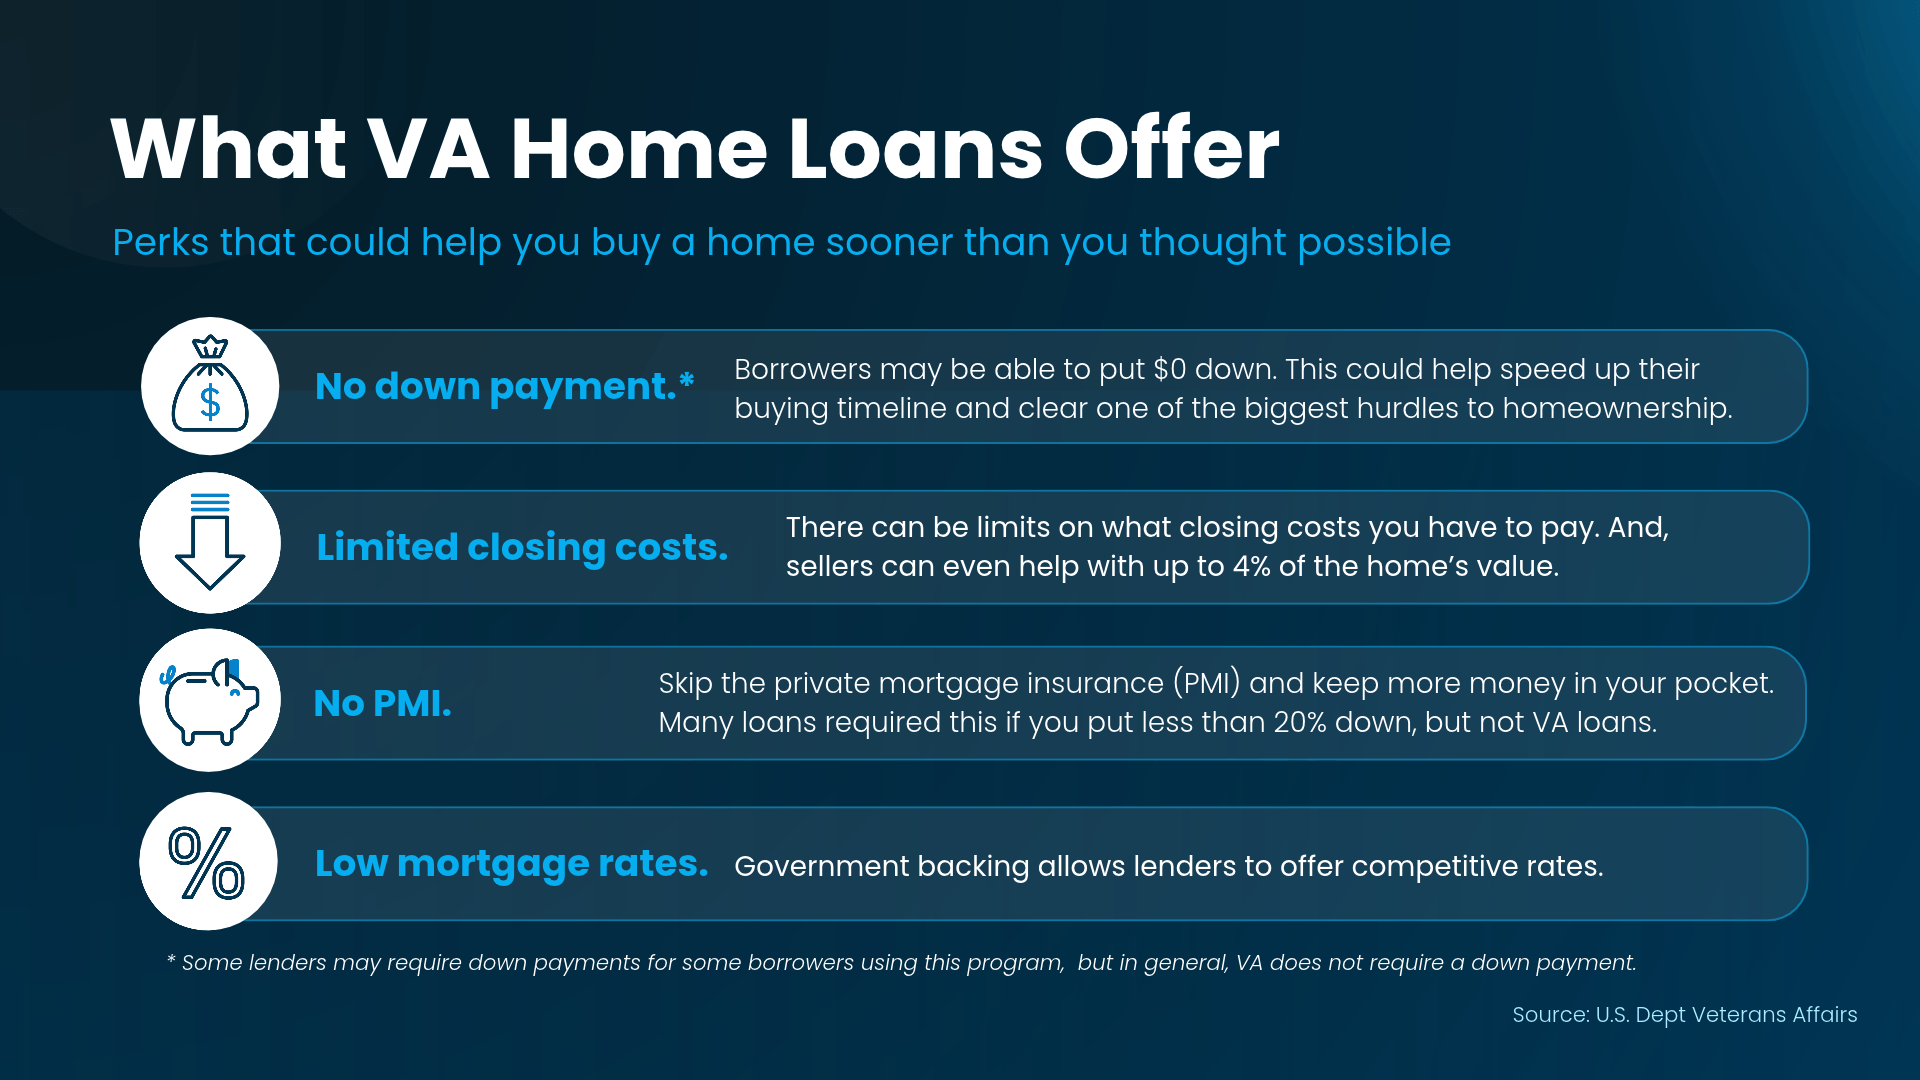
For eligible veterans and service members, VA loans offer advantages that can make buying a home more affordable, including:

  • No down payment required for many eligible borrowers.

  • No monthly mortgage insurance, even with no down payment.

  • Competitive mortgage rates that can help lower monthly payments.
a blue and white website with text

Benefits like this are powerful in any market – and even more so today. That may be why VA loan usage has grown for the last two years in a row.

Why Today’s Market Could Be Different for VA Buyers

A few years ago, when homes were getting multiple offers and buyers were competing for nearly every listing, VA buyers sometimes had a harder time getting their offers accepted.

A 2021 survey from the National Association of Realtors (NAR), found 89% of sellers were likely to accept an offer from a buyer using a conventional loan. But only 30% were likely to accept one using an FHA or VA loan.

The reason? Some sellers were concerned that VA financing would take longer, be more difficult to close, and require them to pay more in costs and repairs. But those concerns don’t necessarily reflect how VA loans actually perform.

VA Home Loan Myths vs. Reality 

A white paper from Vetted VA based on 2025 mortgage data busted a lot of VA loan myths:

Myth #1: VA loans get denied more often than other loans.

  • The Reality: VA loans actually have the lowest denial rate. Just 8.2% of VA purchase applications were denied, compared to 15.0% for conventional loans, 12.8% for FHA loans, and 12.5% for USDA loans. 

Myth #2: VA financing is less reliable.

  • The Reality: 90% of VA home loan applications that reached underwriting made it to closing, compared to 81% for conventional loans. 

Myth #3: VA appraisals take longer.

  • The Reality: VA loan appraisals typically take 7–10 business days, similar to conventional and FHA loans.

Myth #4: Sellers have to pay all the closing costs for VA buyers.

  • The Reality: VA buyers can pay many standard closing costs themselves. Buyers and sellers can also negotiate which eligible costs the seller will cover.

Today’s Market Gives VA Buyers More Leverage

Since there are more homes for sale and fewer buyers competing in many areas, sellers may be more open to different financing options than they were a few years ago. And the opportunity doesn’t stop at getting your offer accepted.

Depending on the house and your local market, you may also be able to negotiate a lower price, ask for repairs, or request help with closing costs.

VA guidelines allow sellers to cover the buyer’s normal closing costs, plus concessions of up to 4% of the home’s value.

Think about what that combination could mean. You may be able to buy with no down payment, avoid mortgage insurance, and negotiate help with some of the other expenses that come with buying a home.

That could mean keeping thousands of dollars in your savings instead of spending them upfront, giving you more breathing room after you get the keys.

Bottom Line

If you’re active duty, you’ve served, or you know someone who has, connect with a local agent and a trusted VA-approved lender to see what you qualify for.

Your VA home loan benefit and today’s market could be a powerful combination.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Low Rates or Lots of Leverage? Buyers Rarely Get Both.

Low Rates or Lots of Leverage? Buyers Rarely Get Both. Simplifying The Market

If you’ve been watching mortgage rates lately, you might feel a little stuck. Rates climbed above 7% this year, and a lot of buyers have decided to sit tight and wait for them to come back down.

But rates are only half the story. When you buy a home, you usually get one of two things: low rates or negotiating power. It’s rare to get both at the same time. And right now, you have a lot more of that second one than you might think.

Why Low Rates and Leverage Don’t Usually Show Up Together

Think back to 2020 and 2021. Rates were near 3%, and buyers rushed into the housing market. Those low rates sounded great, but they came with a catch. There were a lot of buyers just like you that you had to compete with – and there weren’t enough homes for sale to meet that demand. 

That’s why homes got multiple offers, buyers paid over asking or waived inspections, and sellers held all the cards. Jake Krimmel, Senior Economist at Realtor.com, shows just how one-sided things got:

“Seller’s markets peaked at 98 of 100 metros in spring 2022 after two years of mortgage rates near 3%.”

Then, in the second half of 2022, rates went up. As a result, the number of people buying homes went down, inventory grew, and the balance slowly started tipping from sellers back to buyers. Fast forward to today, and that flip is officially here. 

In a recent report, Realtor.com found about two-thirds (66) of the top 100 metros now lean in favor of buyers (see graph below):

a blue and orange pie chart

And while you may want lower rates, this shift in power has its own perks.

What Your Leverage Looks Like Right Now

There are more homes for sale than there have been in years. And in a more buyer-friendly market like that, it means sellers have to work harder to get their homes sold. As Lawrence Yun, Chief Economist at the National Association of Realtors (NAR), says:

“Higher inventory and lengthening days on market give buyers improved negotiating power.”

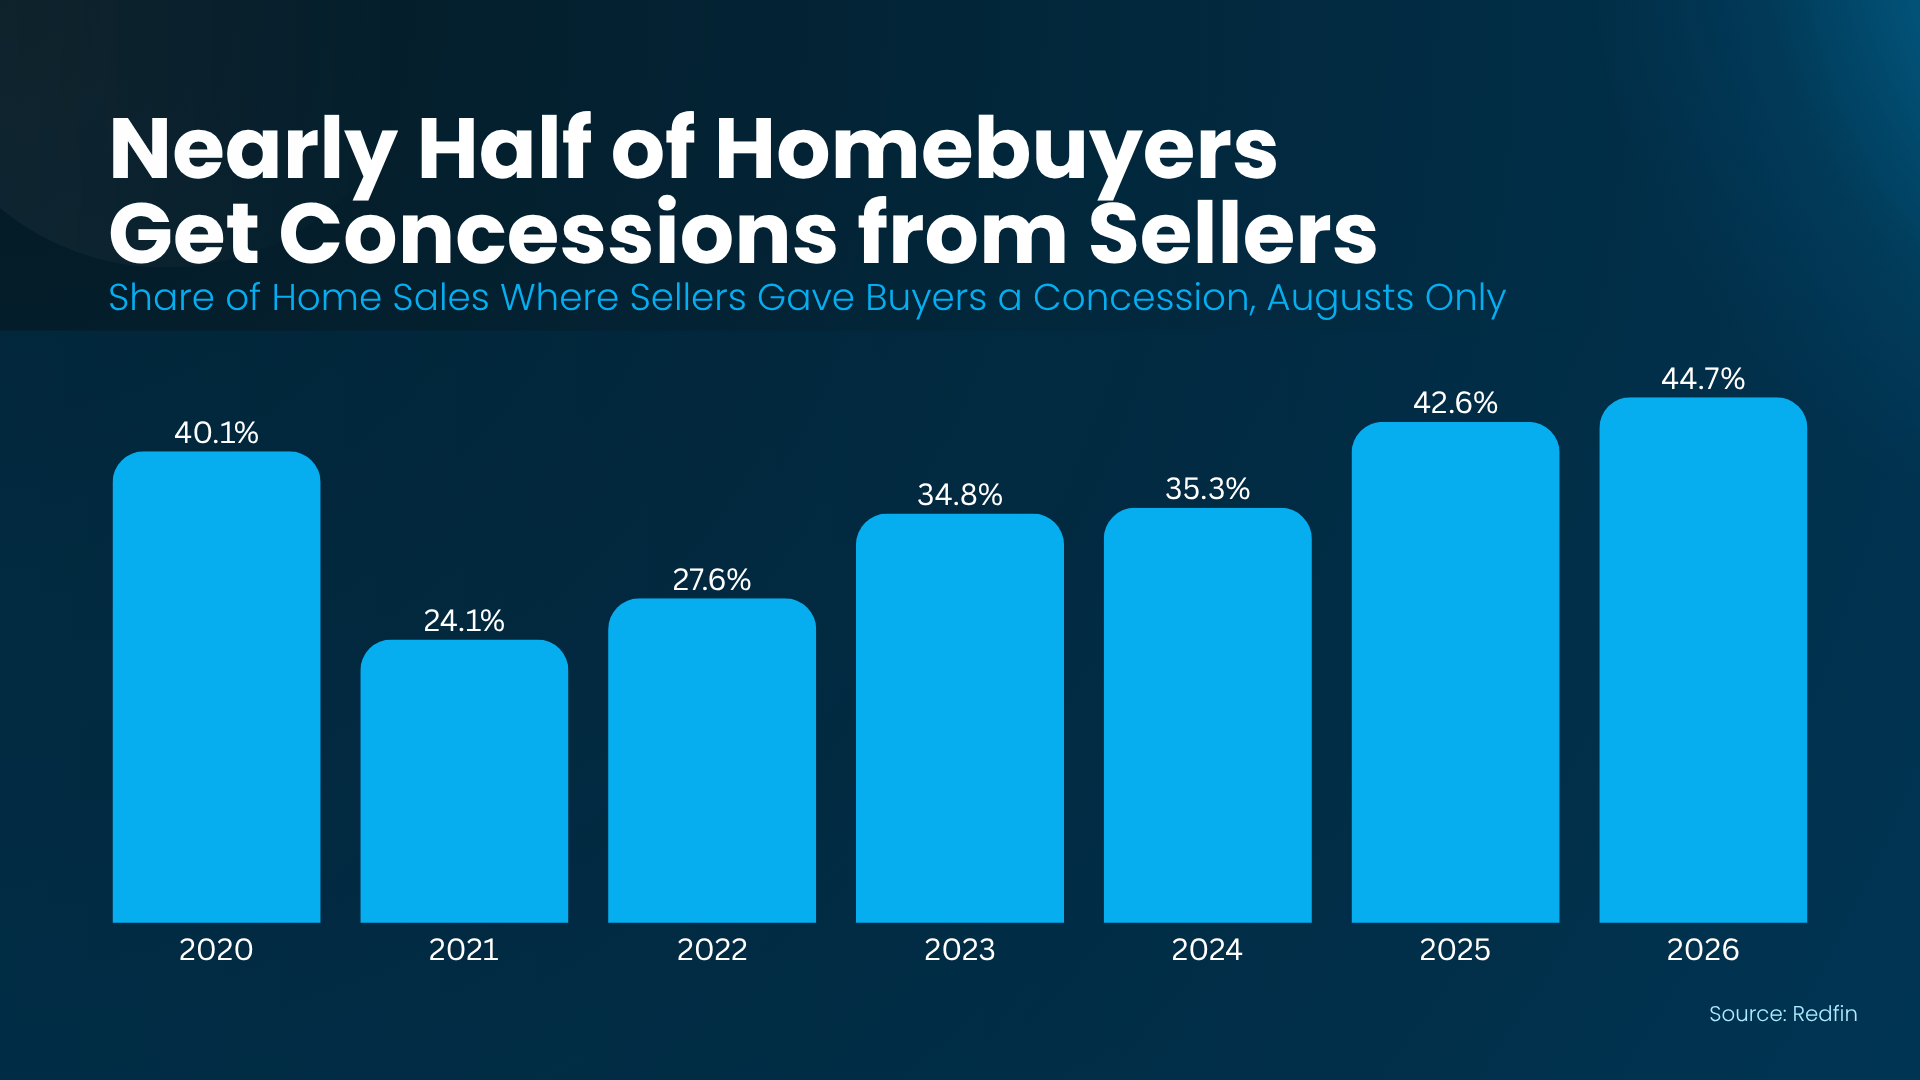
That shows up in the deals buyers are getting. According to Redfin, nearly half of buyers now get some kind of concession from the seller – like help with closing costs, money for repairs, or even the seller paying to buy down your mortgage rate (see graph below):

a graph of sales growth

So when you find a home you love, even if the rate isn’t what you necessarily wanted, there are other levers to pull. Ask about a price cut or a seller-paid rate buydown, too. It could take some of the sting out of today’s rates.

Why Waiting for Lower Rates Could Backfire

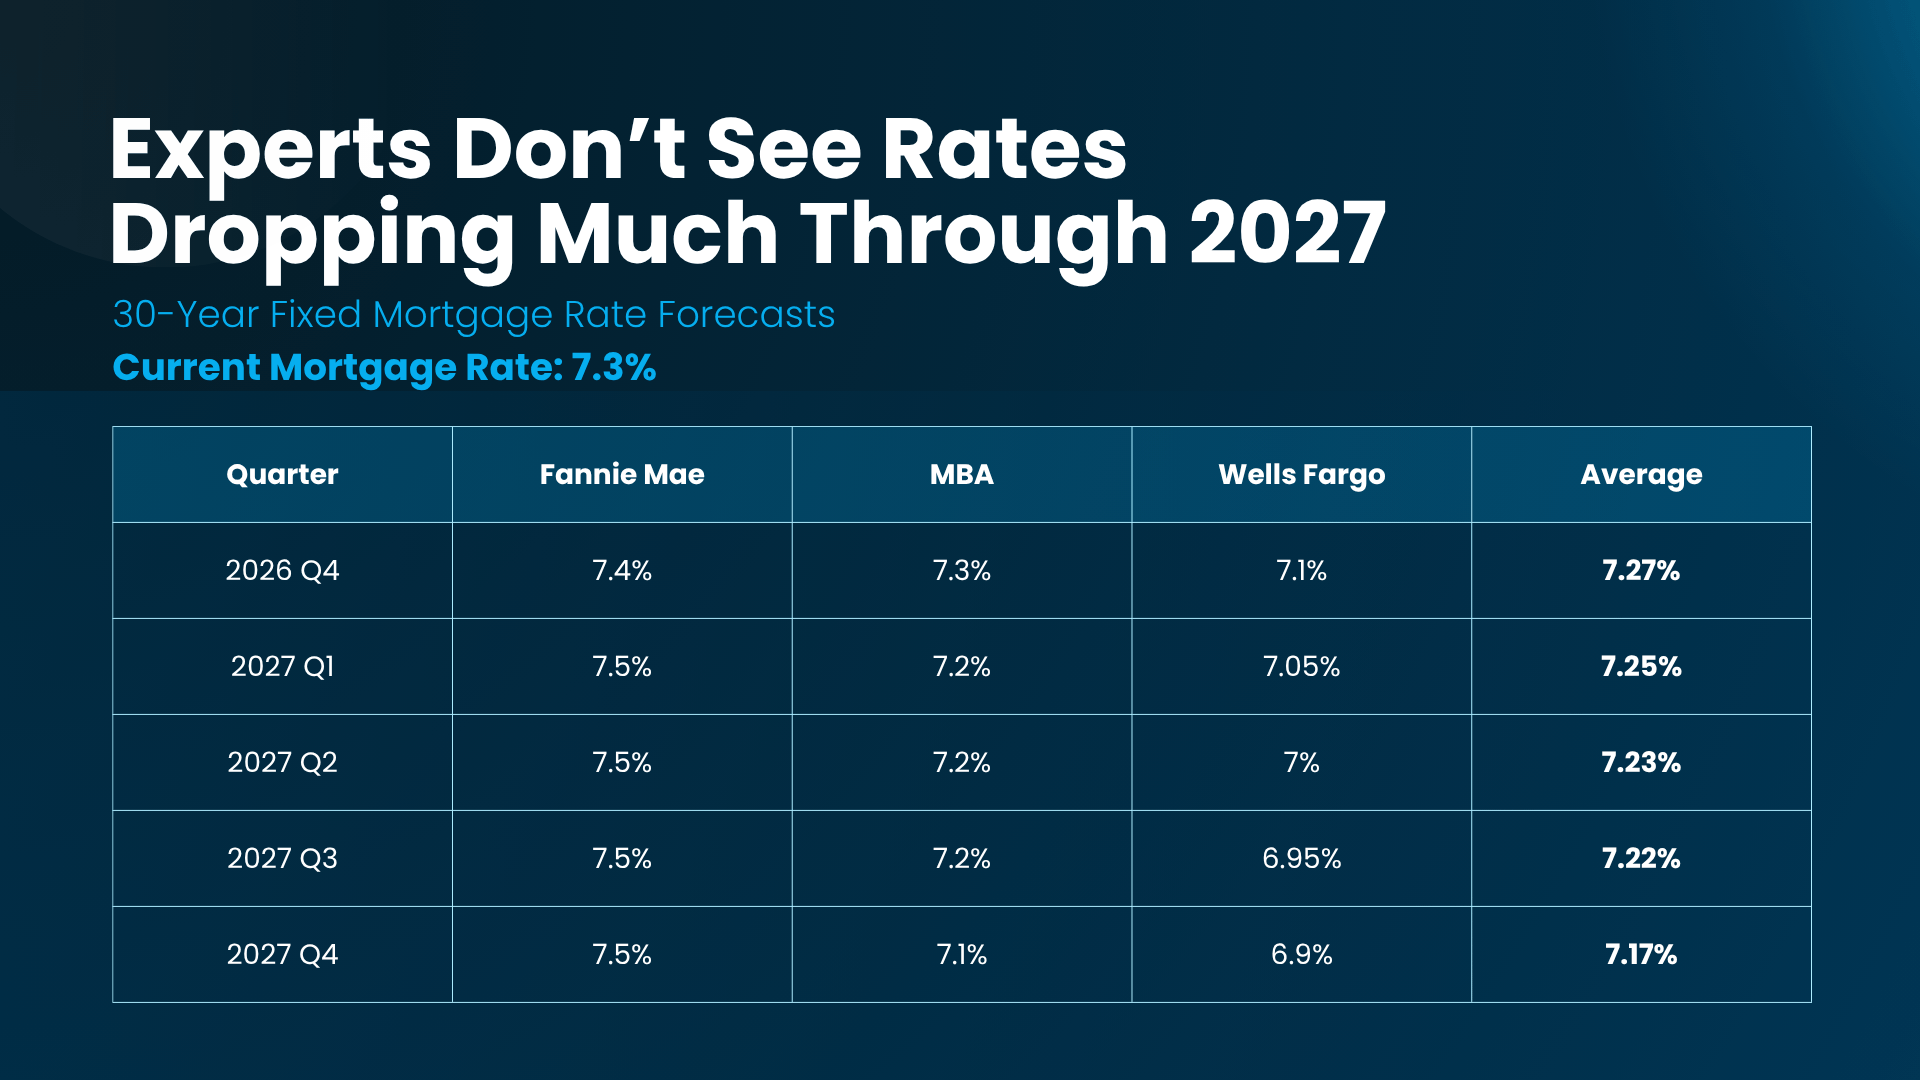
And just in case you’re still thinking you’ll just hold off until rates drop, here’s what you should know. Experts at Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo don’t expect rates to fall much through 2027 (see graph below):

a blue and white graph with white text

And here’s the whole point. Even if rates did drop in a big way, a lot of buyers would rush back in. More competition means fewer deals, fewer concessions, and sellers getting the upper hand again.

So waiting comes with a trade-off. You might land a better rate down the road, but you’d probably give up the bargaining power you have today.

That doesn’t mean you have to move right now. You should only buy when the numbers work for you. But if you’ve got a real reason to move, today’s leverage could help make your numbers work – even at today’s rates.

Bottom Line

Buyers rarely get low rates and strong negotiating power at the same time, and today’s market is handing you the leverage. 

Connect with a local real estate agent to find homes where sellers may be open to covering a rate buydown or closing costs, so you can see if today’s market can work for your budget.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
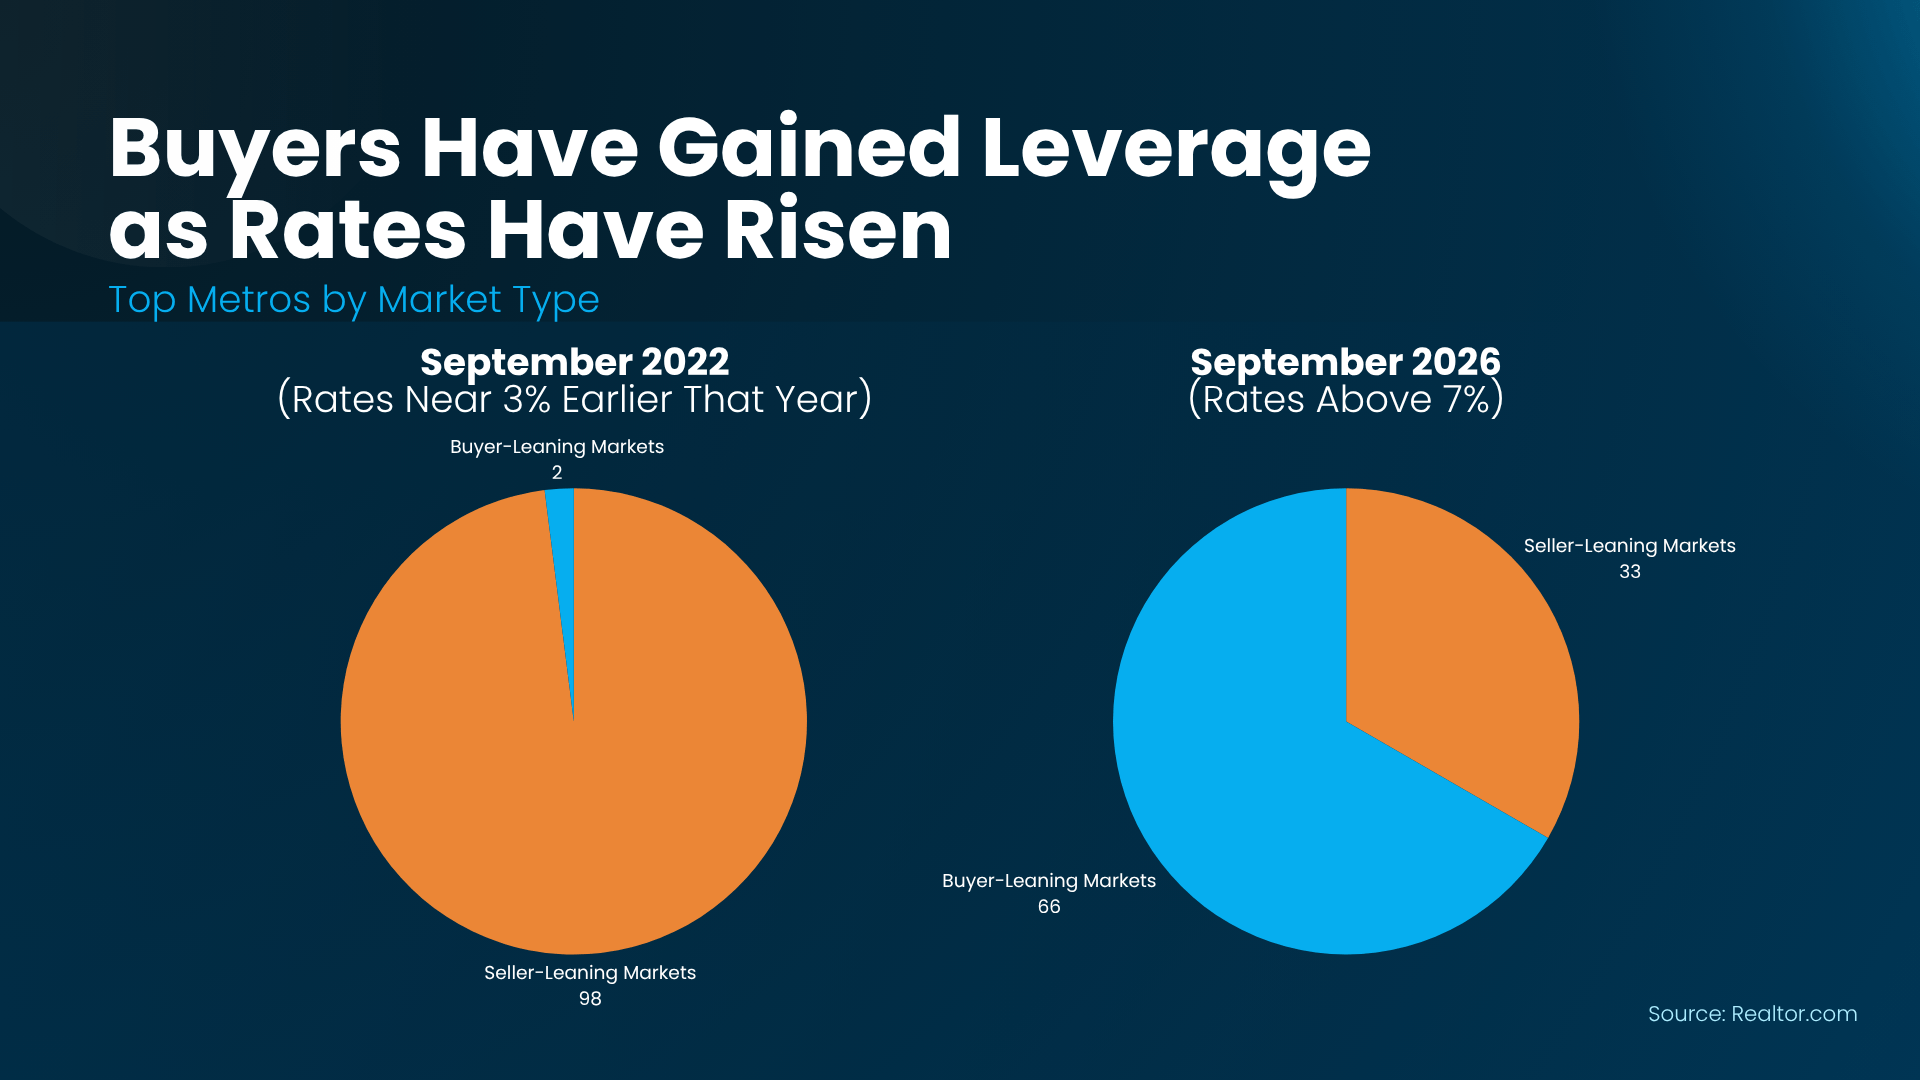
Fidelity Home Group | Fewer Homes Are Selling for Over Their Asking Price

Fidelity Home Group | Fewer Homes Are Selling for Over Their Asking Price Remember when it felt like almost every house went for way over asking? In many places, that’s calmed down. Fewer homes are selling for over list price today. Want to know what to expect if you’re buying in our market? Let’s talk. NMLS ID 1834853 #HomeAffordability #HomeSalesPrice #fidelityhomegroup #floridamortgage #floridamortgagerates #floridamortgagecompany #mortgagetips

#fidelityhomegroup, #floridamortgage, #floridamortgagerates

What Experts Forecast for Mortgage Rates and Home Prices in 2027

What Experts Forecast for Mortgage Rates and Home Prices in 2027 Simplifying The Market

When it comes to housing, two of the biggest questions on everyone’s mind right now are:

  1. What’s next for mortgage rates?

  2. Where will home prices go from here?

And if you’re weighing whether to move in the next few months or wait until 2027, here’s what you should know.

When experts look ahead to 2027, they see a steady housing market. No wild swings. No big surprises. Just a calmer, more balanced market.

And steady makes planning a whole lot easier. Let’s break it down.

Rates Are Expected To Settle into a Steady Range

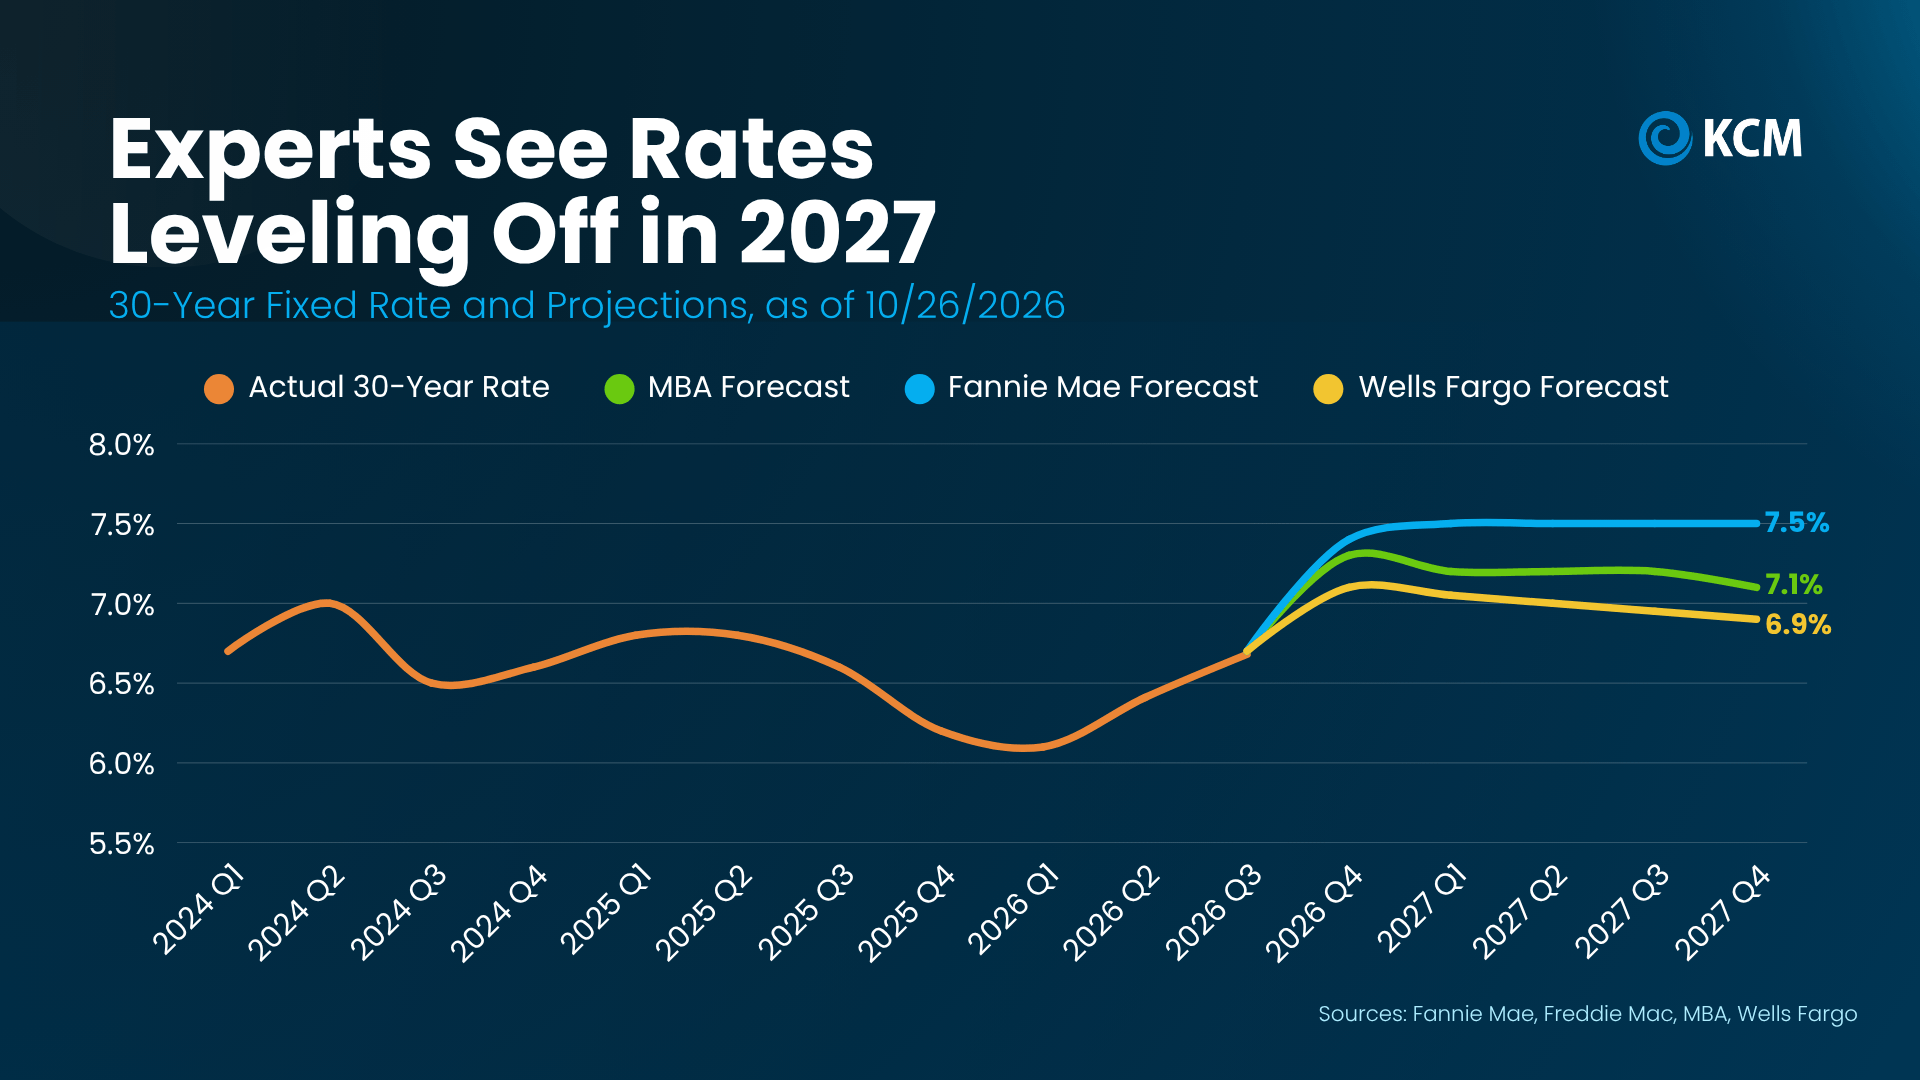
Lots of people are holding out for lower rates. But the latest forecasts from Fannie Mae, the Mortgage Bankers Association (MBA), and Wells Fargo show rates holding fairly flat through 2027 (see graph below):

a graph of a graph showing the number of the same time

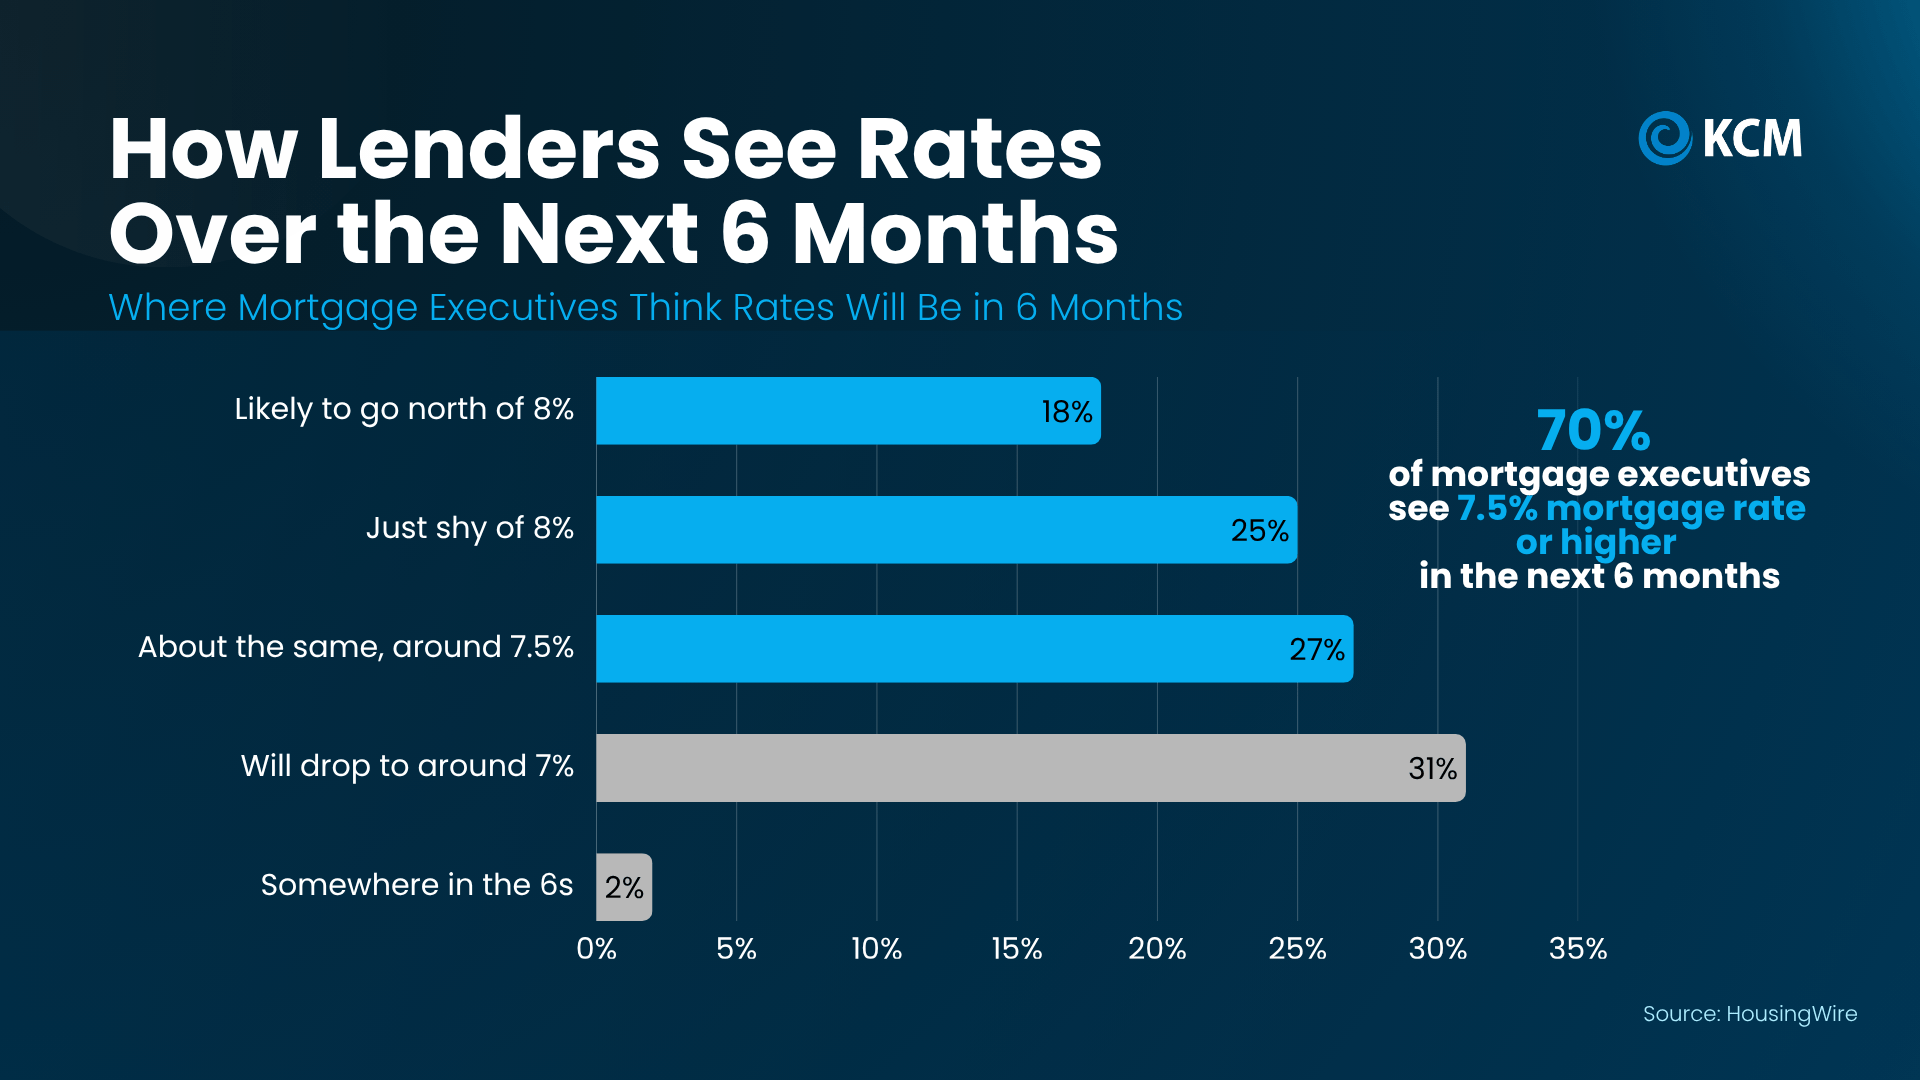
Lenders see it the same way. In a recent survey from HousingWire, 70% of mortgage executives said they expect rates to be around 7.5% or higher six months from now (see graph below):

a graph of percentages and numbers

And if you’re wondering why, the answer is fairly simple. Chen Zhao, Head of Economics Research at Redfin, says:

“Until the underlying economic fundamentals—everything from oil prices to AI–that are keeping rates high change, mortgage rates are unlikely to fall significantly.”

So what does that mean for you? Instead of trying to guess where rates go next, focus on what you can control. Even if rates don’t budge, there are still ways to get the best rate possible. When you talk with your lender, ask about:

  • Your credit score. Even a small bump in your score could help lower your rate.

  • Different loan types. Some programs offer lower rates or smaller down payments than you might expect.

  • Buying down your rate. Paying a little more upfront (called “points”) can lower your rate and your monthly payment.

That way, you’ll know exactly where you stand and what a comfortable monthly payment looks like for you. 

Prices Should Keep Climbing, Just More Slowly

But what about prices? Here’s where steady really works in your favor. 

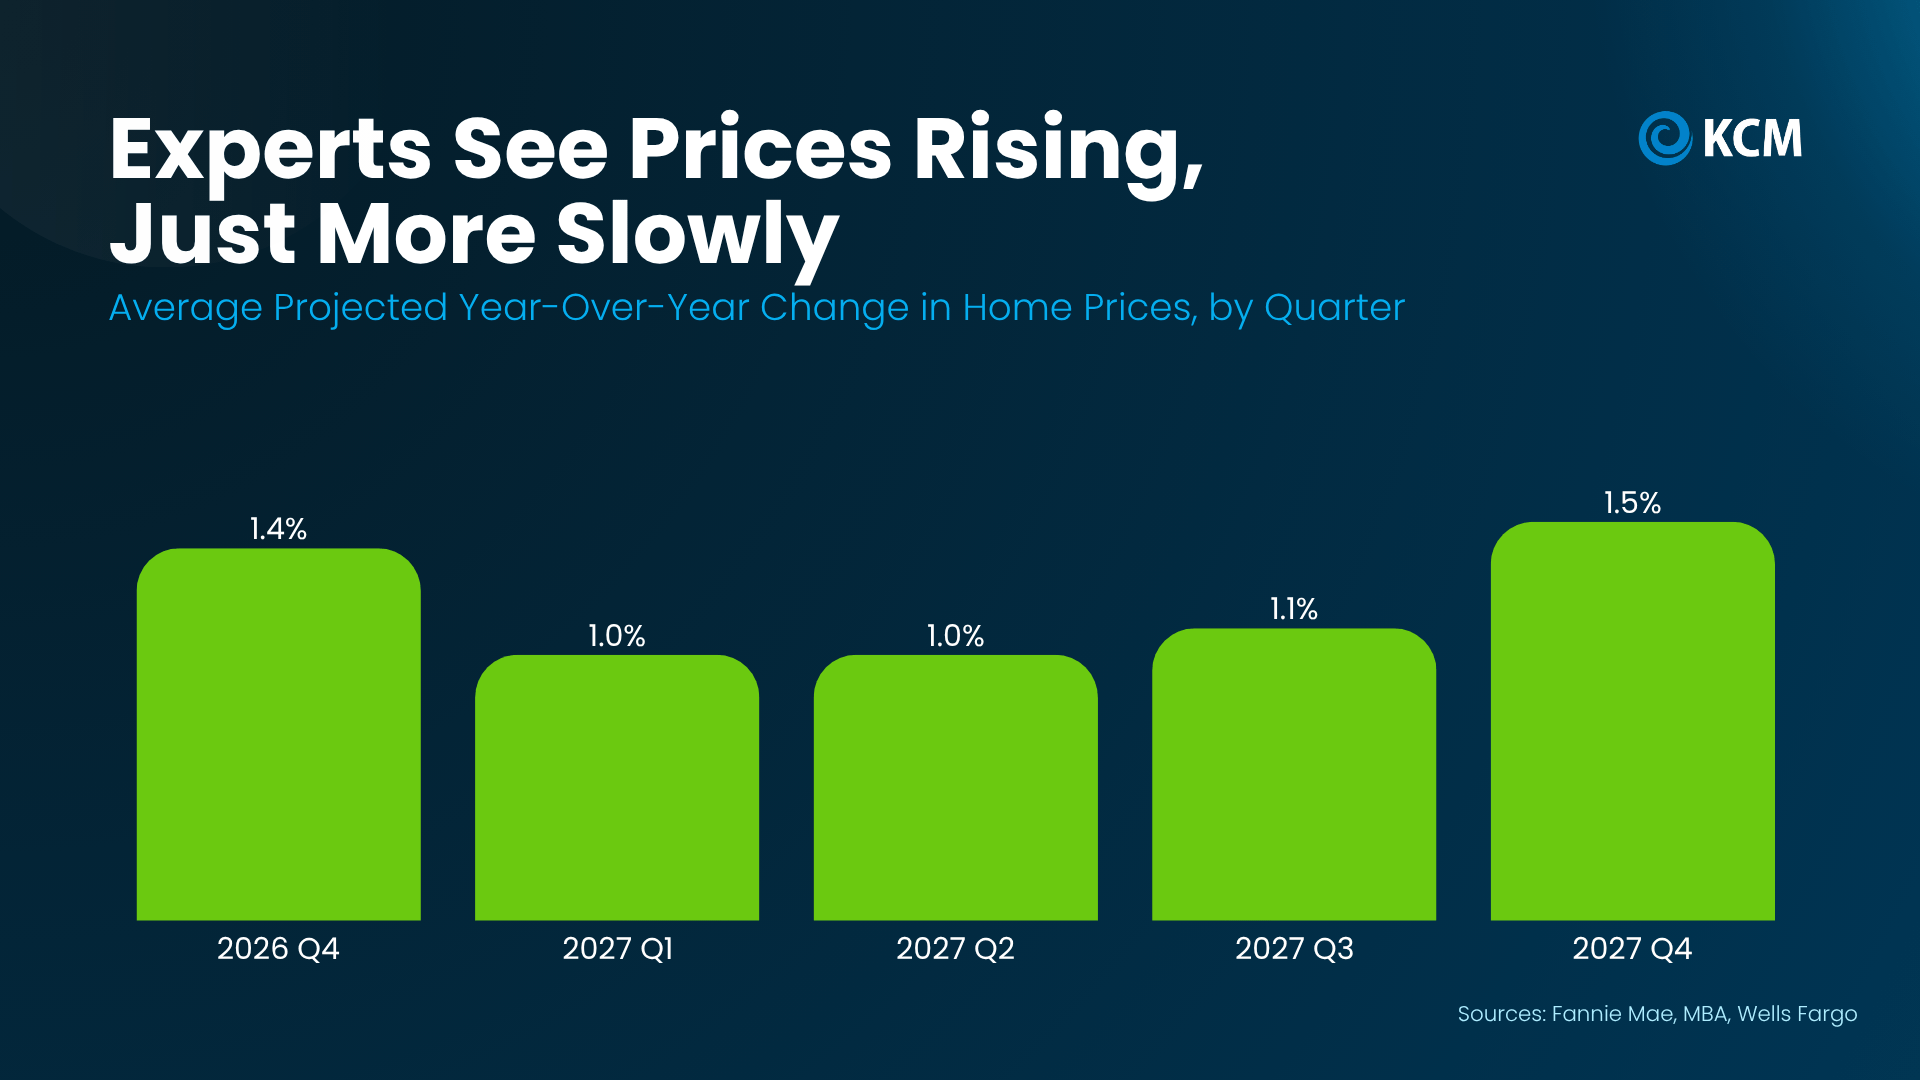
Experts don’t see a home price drop coming. On average, forecasts from Fannie Mae, MBA, and Wells Fargo show prices rising about 1% to 1.5% a year through 2027 (see graph below):

a graph of a number of green squares

In plain terms, in most places prices are still going up, just not as fast. For sellers, that means your home should hold onto its value. For buyers, slower growth gives you a little more breathing room. Just don’t count on prices getting cheaper while you wait.

But keep in mind, these are national forecasts. Prices can look very different from one area to the next, so what matters most is what’s happening where you live.

The Best Time To Move Is When It Fits Your Life

When the market is steady, you don’t have to try to time it perfectly. There’s no big swing to wait out.

That puts the focus back on you. Maybe you need more space for a growing family. Maybe you’re ready for less upkeep. A steady market makes it easier to plan for either one.

Bottom Line

If you’re asking yourself should you move now or wait? You should know experts see a steady market through 2027, with rates holding near today’s levels and prices rising slowly. 

So, rather than waiting for a big shift that may not come, connect with a local real estate agent and run the numbers on what a move looks like at today’s rates and prices, so you can decide based on your goals instead of the headlines.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Miami’s Iconic Condo Skyline

Start your home purchase qualifier with no personal info. Struggling to qualify for loans without traditional income proof? DSCR mortgages let your investment property’s cash flow do the talking. Use your property’s income, not your paystub. This program supports purchases and refinances with flexible down payments and credit requirements. Qualify with a minimum credit score of 660 and no personal income verification—perfect if you rely on rental income or own an LLC. Understand the clear rules on down payments, reserve requirements, and loan limits. Get your rate and see how DSCR programs can work for your investment goals. Get your rate now. ? Link in profile #DSCRMortgage #InvestmentPropertyLoan #FloridaRealEstate #Condotel #RealEstateInvesting

#fidelityhomegroup, #floridamortgage, #floridamortgagerates

When your mortgage approval feels like winning an Oscar!

Start your home purchase qualifier with no personal info to see how easy non-warrantable condo financing can be. Get your rate ? Link in profile #FloridaMortgage #NonWarrantableCondo #MortgageTips #FloridaRealEstate #InvestInFlorida

#fidelityhomegroup, #floridamortgage, #floridamortgagerates

FLorida Condos are growting

Start your home purchase qualifier with no personal info. Starting a Condo mortgage begins with development approval. This process helps qualify the property for financing and secures your investment in Florida’s growing market. We guide you through each step, so you can focus on your new home. Get your rate today and move closer to ownership. ? Link in profile #CondotelMortgage #NoConventionalIncome #FloridaRealEstate

#fidelityhomegroup, #floridamortgage, #floridamortgagerates

What To Expect from the Housing Market in the Second Half of 2026

What To Expect from the Housing Market in the Second Half of 2026 Simplifying The Market

If the first half of this year has left you feeling stuck, you’re not the only one. Mortgage rates stayed higher than people wanted. Affordability remained tight. And uncertainty overseas added another layer of pressure nobody saw coming.

That’s why so many people are asking the same question: Will the second half of the year be any better for the housing market?

While nobody has a crystal ball, there are a few encouraging signs things could start moving in a better direction. Here’s what to watch.

Mortgage Rates Could Be Near a Turning Point 

One of the biggest reasons mortgage rates haven’t come down yet is inflation. And higher energy prices and uncertainty overseas are at least part of the reason inflation is still elevated. The encouraging news?

Oil prices have already started coming back down.

That may not sound like it has much to do with buying a home. But historically, mortgage rates and oil prices tend to move in the same direction.

Take a look at the graph below. Generally, they rise and fall together. Both went up in February when the conflict began. While there’s been some volatility lately, experts at the U.S. Energy Information Administration (EIA) say oil prices are forecast to come down. And since oil prices have been on an overall downward trend lately, mortgage rates could come down too:

a graph showing the price of a mortgage rate

It’s too soon to say exactly when that will happen (or by how much they’ll fall), but if energy prices go down, inflation cools off, and tensions overseas ease, mortgage rates could come down in the second half of the year.

And that’s good news for anyone thinking about moving. The first half of the year tested everyone’s patience. The second half may finally reward it.

Home Prices Could Pick Back Up

A lot of people want home prices to fall too. But that’s not what most forecasts show.

While price trends are going to vary by area, and some places are seeing mild declines, experts still expect home prices to net positive this year at the national level.

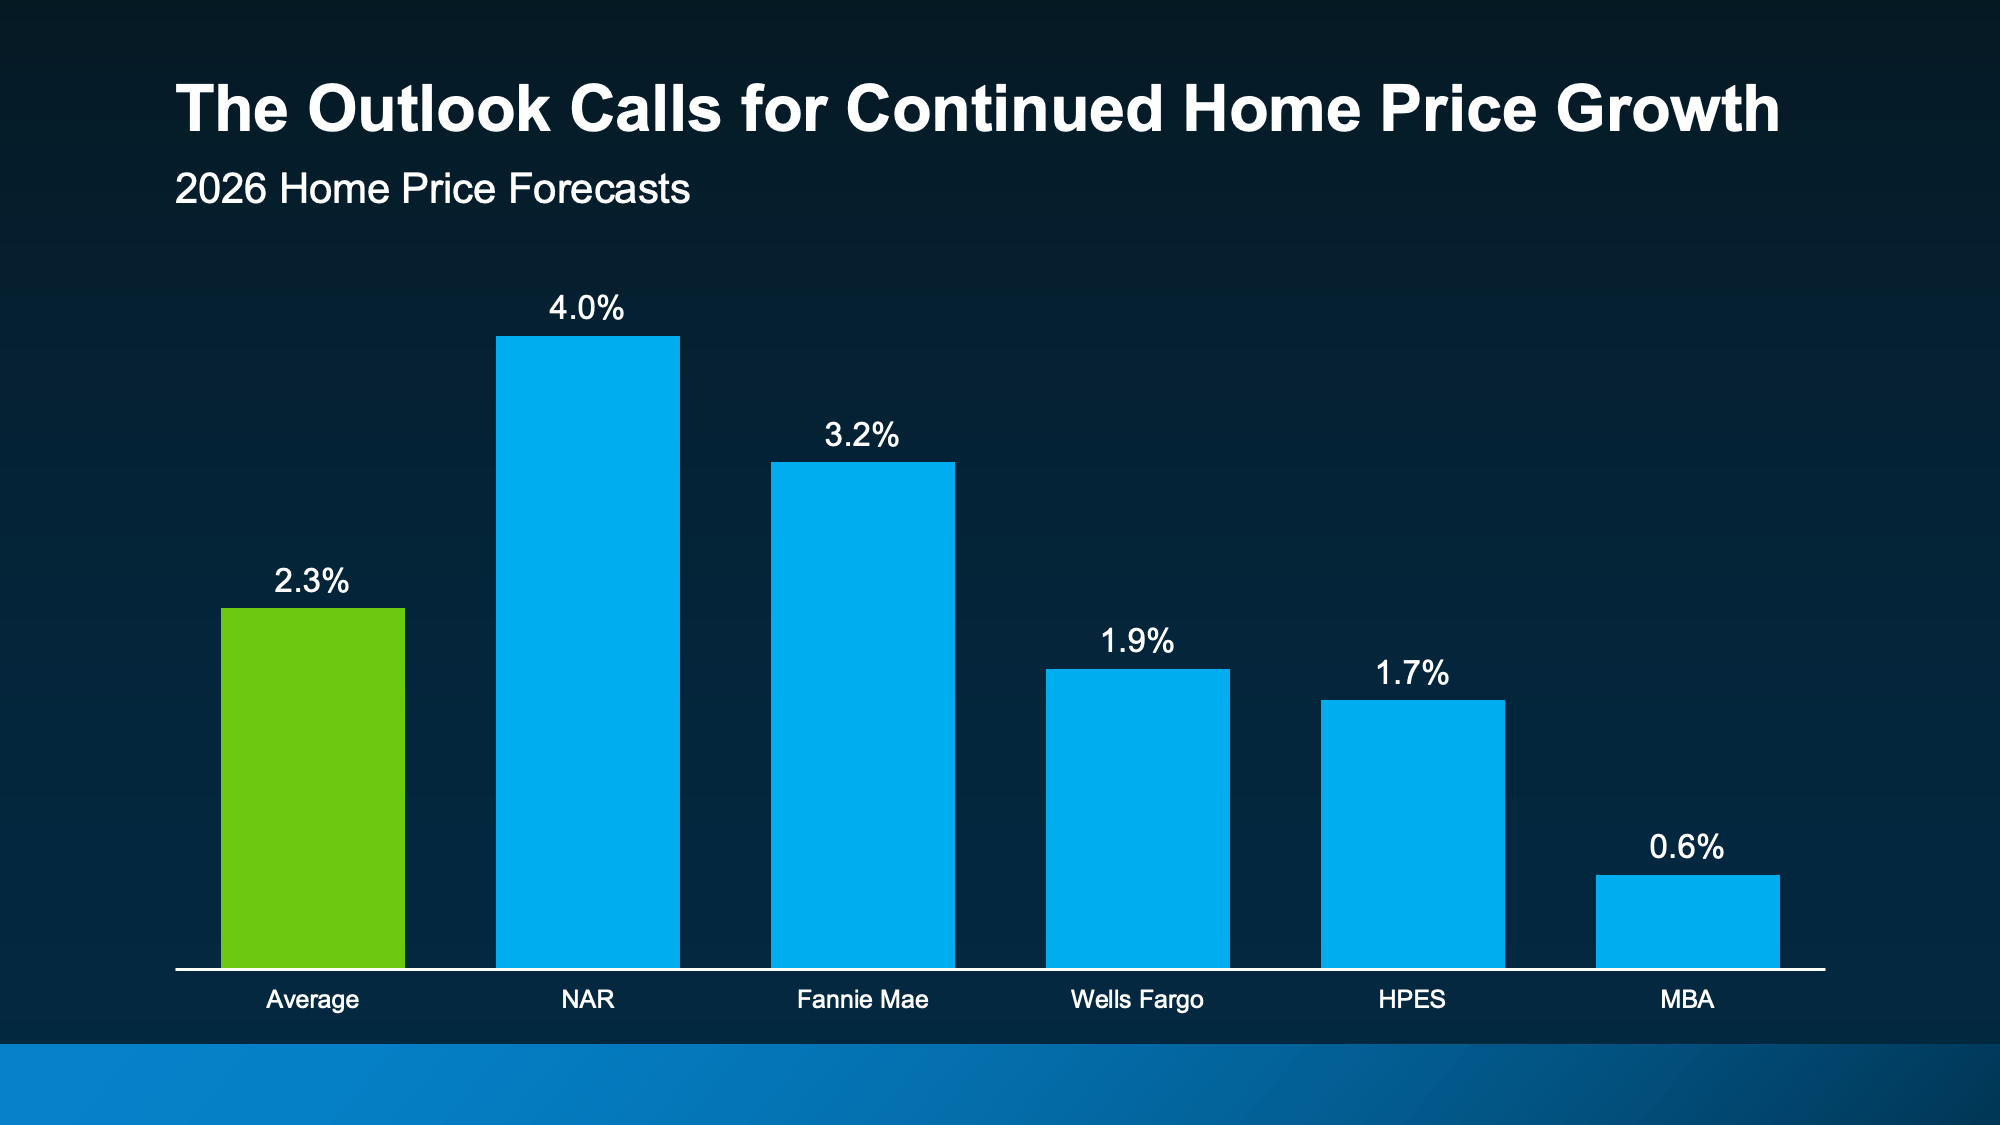
In fact, they’re projecting prices will rise by an average of 2.3% in 2026 (see graph below):

a graph of blue rectangular objects

What does that mean for you? Right now, Federal Housing Finance Agency (FHFA)data shows prices are up about 1.7% nationally year-over-year. The average forecast for all of 2026? 2.3%.

Based on those projections, home price growth would have to pick up a bit during the second half of the year. Nothing dramatic, just enough to finish the year around that projected 2.3% gain.

Here’s why that’s possible.

The number of homes for sale has grown, but that growth may be starting to slow down. And if rates improve, more buyers could jump back into the market. More buyers competing could put modest upward pressure on prices, especially if inventory’s not growing as fast.

That’s why buyers shouldn’t assume waiting will guarantee a lower price later. And for sellers, that’s great news if you’ve been worried about your home’s value.

More Homes Are Expected To Sell

If you’ve been wondering why the housing market has felt quieter lately, you’re not imagining it. Home sales have been slower than many experts expected. But that doesn’t mean people have stopped wanting to move.

A lot of people still want or need to make a change. They’ve just been waiting for more certainty, better affordability, or a clearer read on where the market is headed. And early signs show that may be on the horizon. 

If rates ease and confidence improves, more people may finally move. As Odeta Kushi, Deputy Chief Economist at First American, explains:

“Overall, we expect pent-up demand to continue emerging gradually. But the pace of recovery will vary significantly across markets and will depend on the path of rates, labor market conditions and inventory growth.” 

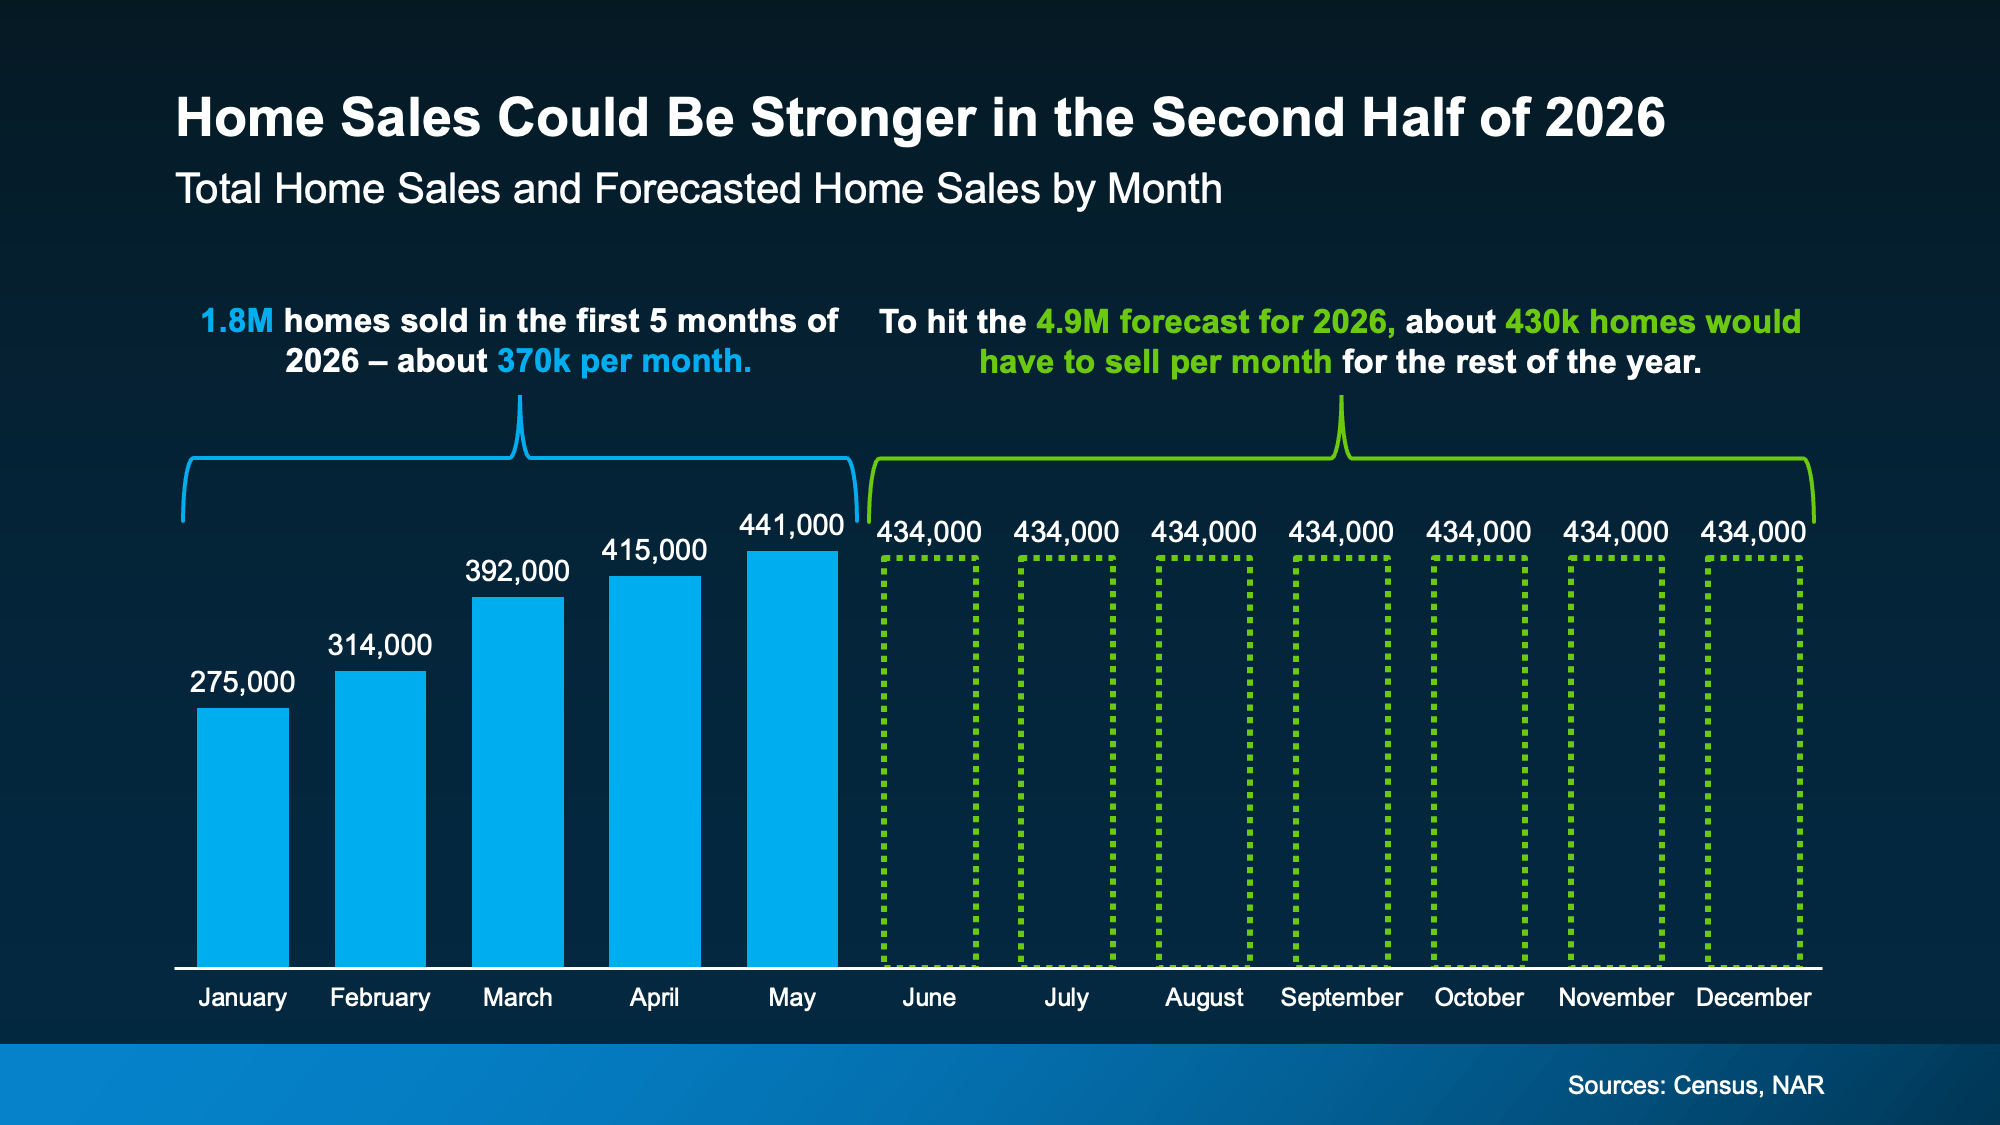
Based on the latest forecasts, to hit the number of sales expected this year, here’s what would have to happen. The second half of the year would need to outperform the first in sales (see graph below):

a graph of sales and statistics

In fact, each month for the rest of 2026 would have to come close to matching the best month we’ve had so far this year (May). That’s a sign the experts are calling for more momentum headed into the second half.

More people will finally make their move happen – and you’ve got the chance to be one of them.

Bottom Line

The second half of the year probably won’t be perfect. But it could be better.

Mortgage rates may ease. Home sales could pick up. And prices are expected to continue rising at a healthier, more sustainable pace. If you’ve been waiting for signs of progress, this is it.

If you want to understand what these forecasts mean for your plans and what’s happening in your local market, connect with an agent.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Condotel Financing

Start with our home purchase qualifier or get a rate quote with no personal info. ? A recent investor closed a waterfront condotel purchase! This fast process makes buying unique investment properties easier in the city. If you struggle to find lenders for non-traditional condos, you’ll see how this option helps smooth the way. Get your rate now to find out your options. ? Link in profile #FloridaRealEstate #InvestmentProperty #NonWarrantableCondo #CondotelFinancing

#fidelityhomegroup, #floridamortgage, #floridamortgagerates

Orlando Beach Boardwalk

Start with our home purchase qualifier or get a rate quote with no personal info. If you’re investing in Orlando real estate, DSCR loans can simplify financing, letting the property’s income do the work. This micro-case shows how a local investor secured a DSCR loan using cash flow—not personal income—to qualify for a non-warrantable condo. No conventional income docs needed, just solid property returns. Benefit from financing designed for investors like you, including options for hard-to-finance properties in Orlando. Get your rate now! ? Link in profile #OrlandoRealEstate #DSCRLoans #InvestmentPropertyFinancing

#fidelityhomegroup, #floridamortgage, #floridamortgagerates