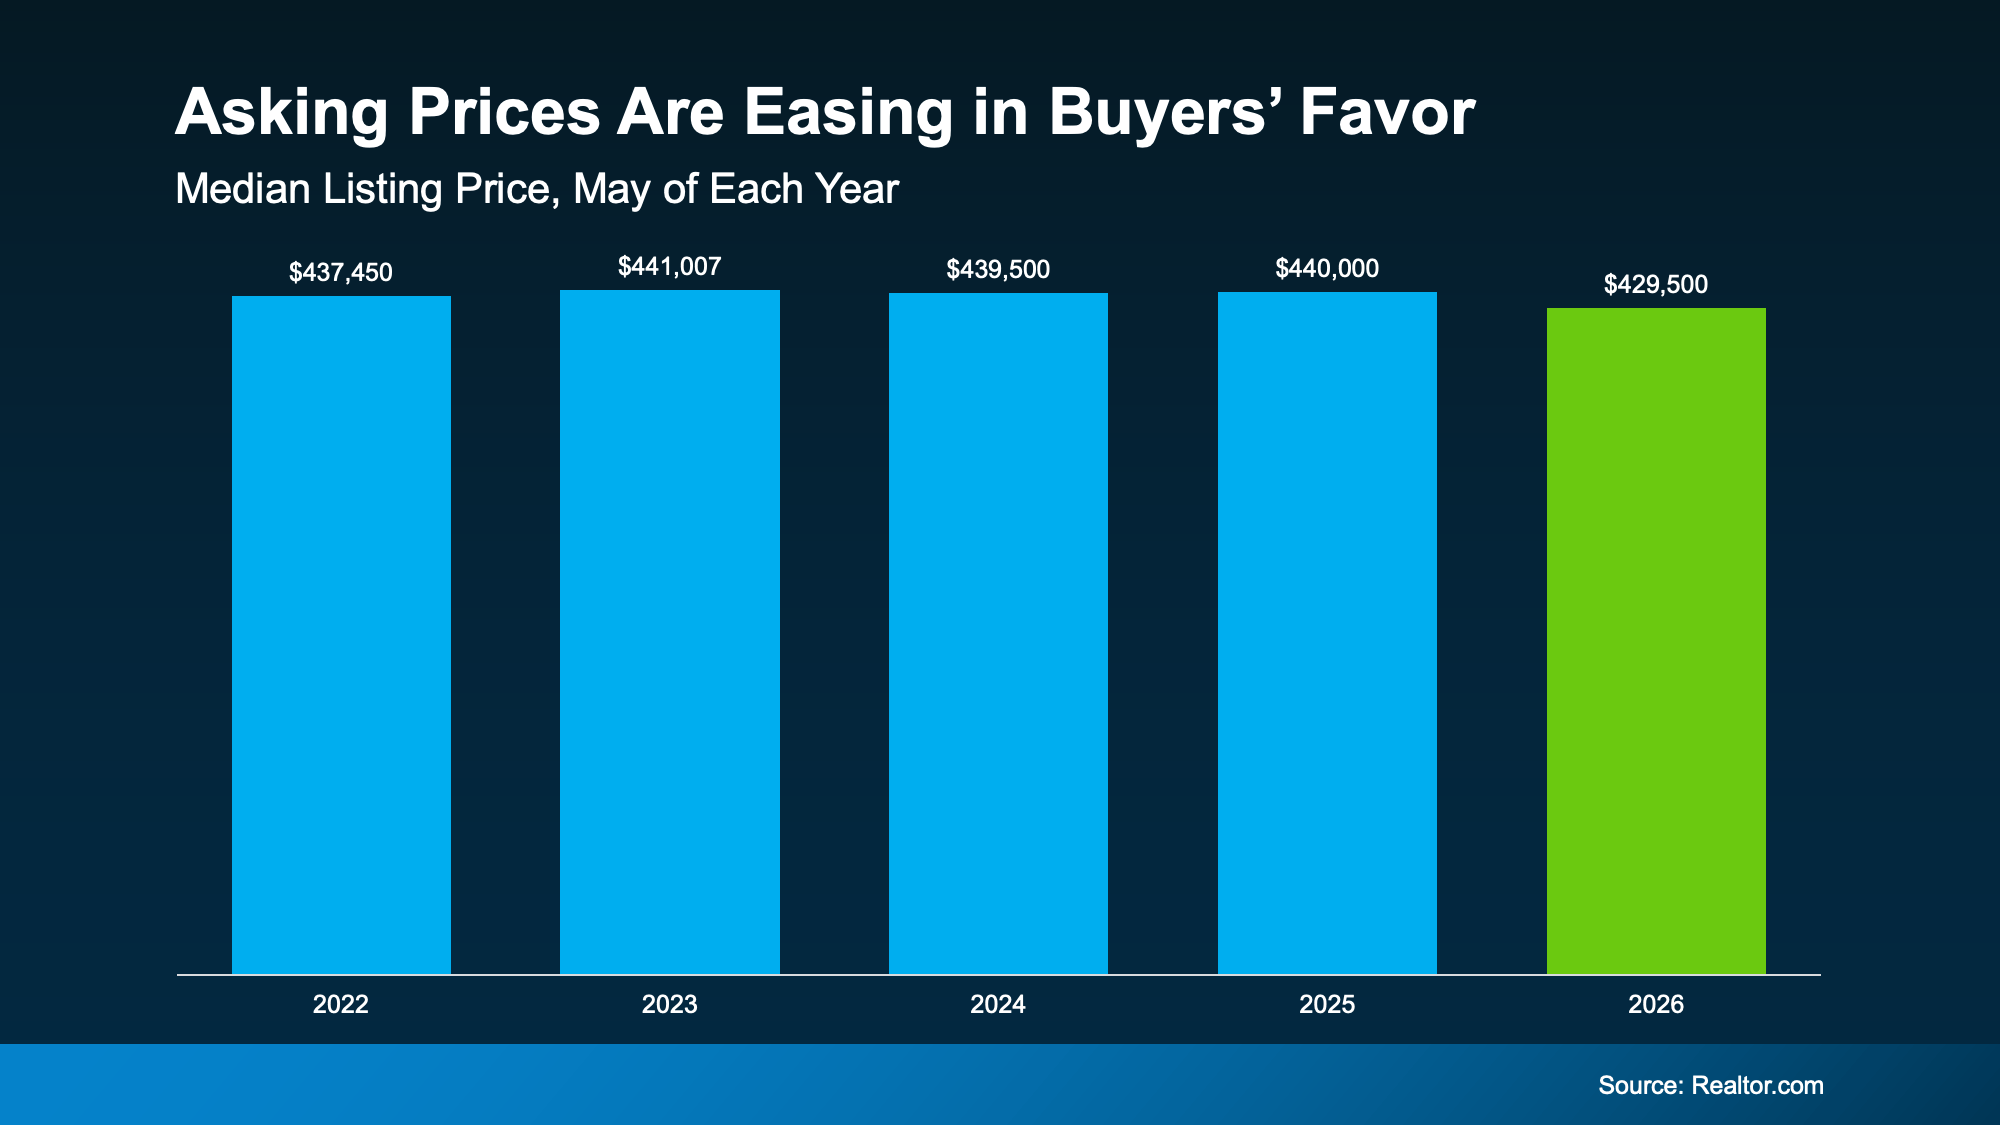Available 7 Days/Week       MON - FRI  8am - 7pm       SAT - SUN  10am – 6pm
Call us (407) 955-4575
Apply Now

Tag: #mortgageflorida

The 1 Factor That Explains Everything Happening with Home Prices Right Now
The 1 Factor That Explains Everything Happening with Home Prices Right Now Simplifying The Market

You’ve probably heard that home prices are cooling off. And that’s true – nationally. But zoom in on individual markets across the country, and the picture looks completely different depending on where you are.

Some areas are still seeing solid price growth. Others have gone flat. A few have actually dipped slightly negative. So, what’s causing all of that variation? 

It All Comes Down to Inventory

Here’s the simple version:

  1. When there are more homes for sale, buyers have options.

  2. More options, means less competition.

  3. Less competition means sellers can’t push prices as high.

On the flip side, when inventory is tight, buyers are competing over a small pool of homes, and that pushes prices up.

That dynamic is playing out right now in a really visible way across the country. 

Markets where inventory has climbed back to, or above, normal pre-pandemic levels are seeing prices flatten or fall slightly. Markets where inventory is still well below those 2019 benchmarks are still seeing prices rise. As Lance Lambert, CEO of ResiClub, puts it:

“Home prices are still climbing a little year-over-year in many regions where active inventory remains well below pre-pandemic 2019 levels, such as pockets of the Northeast and Midwest.

In contrast, some pockets in states like Texas, Florida, and Colorado — where active inventory exceeds pre-pandemic 2019 levels by a solid clip — are seeing modest home price pullbacks or flat pricing.”

The Maps Say It All 

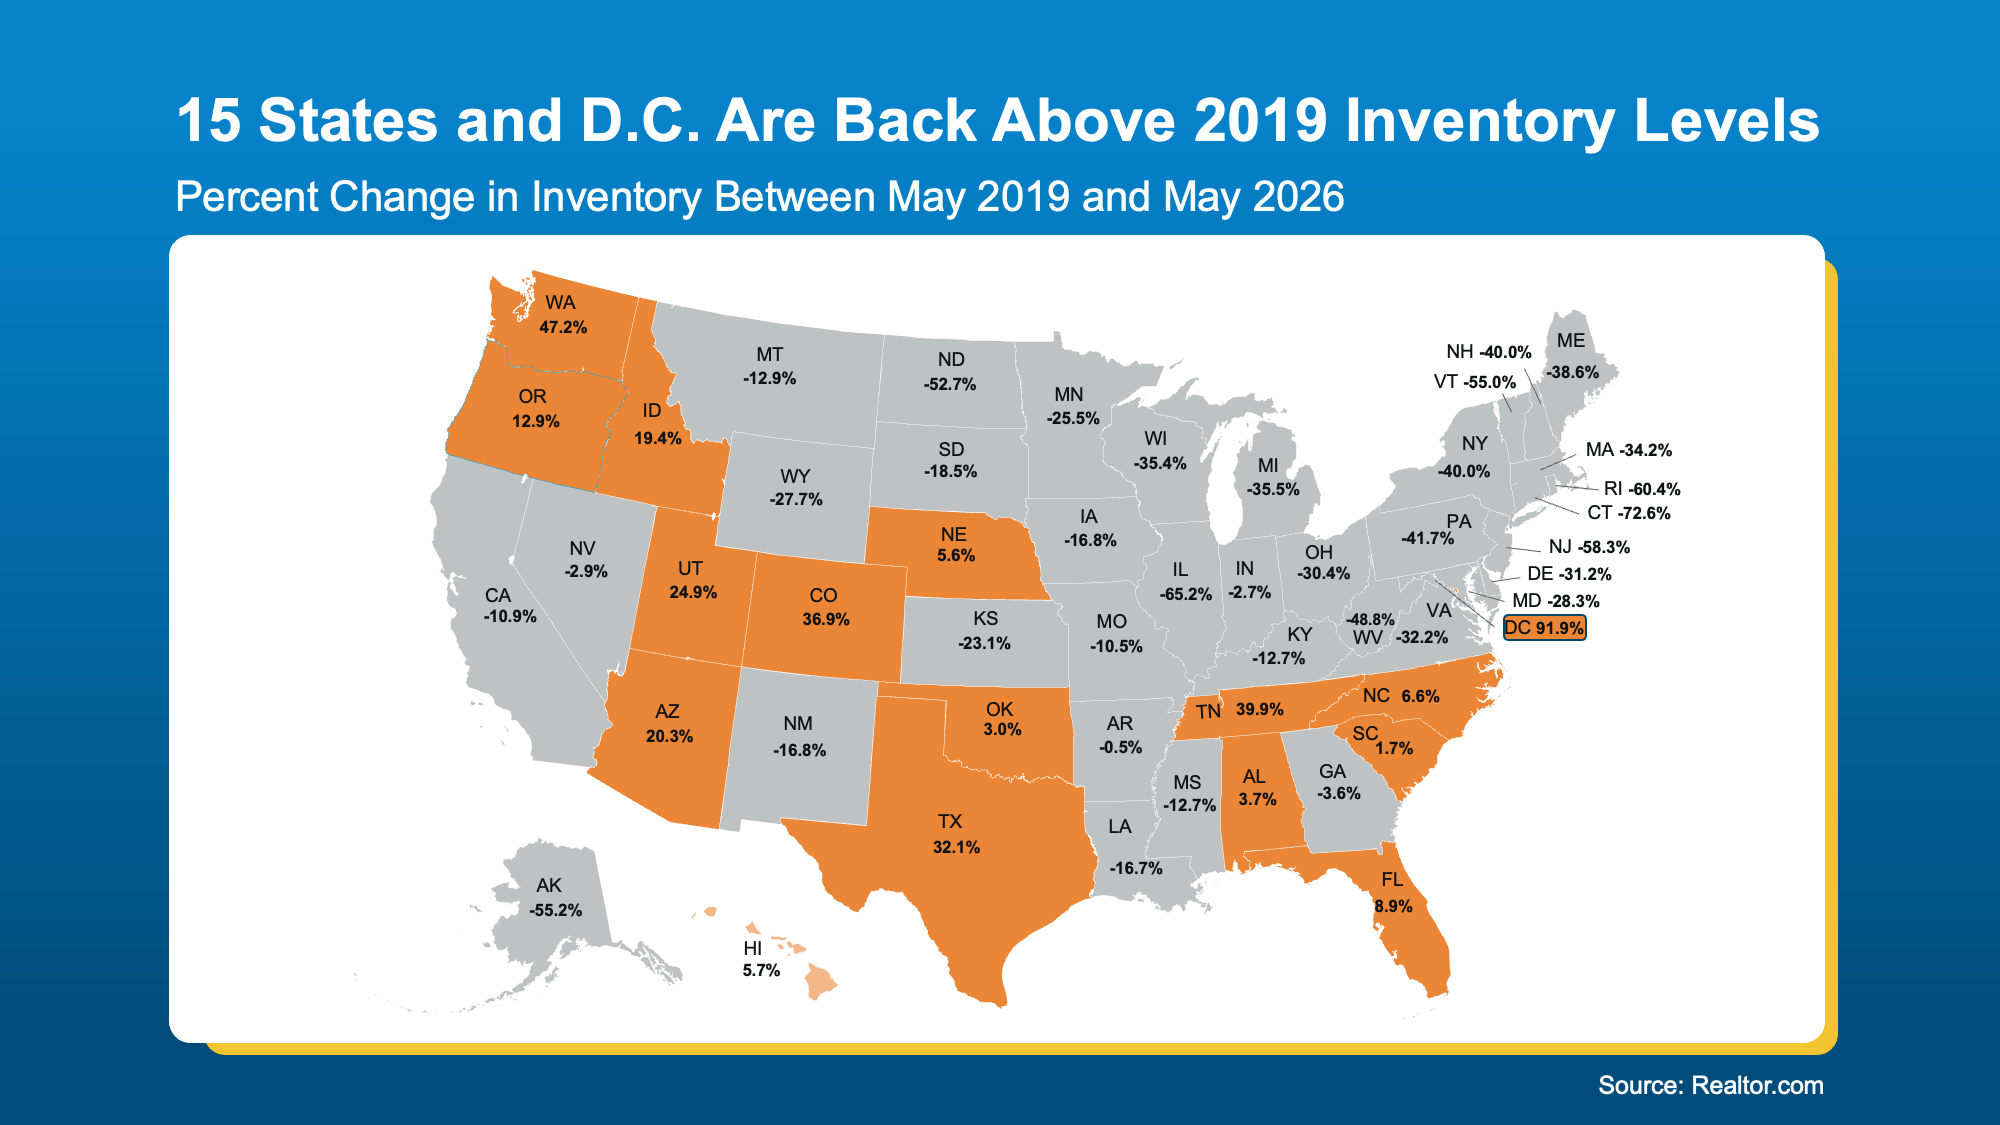
Take a look at where inventory stands today compared to 2019. In most places (the states in gray below), inventory still falls short of where we were back then. And that’s exactly why prices are climbing, albeit moderately, in the vast majority of states.

But you’re probably more interested in where prices are falling a bit, since that’s what is making headlines. So, let’s prove out how much inventory affects prices in those spots.

According to Realtor.com, 15 states and Washington, D.C. are now back above pre-pandemic inventory levels, and some by a wide margin (see the orange in the map below):
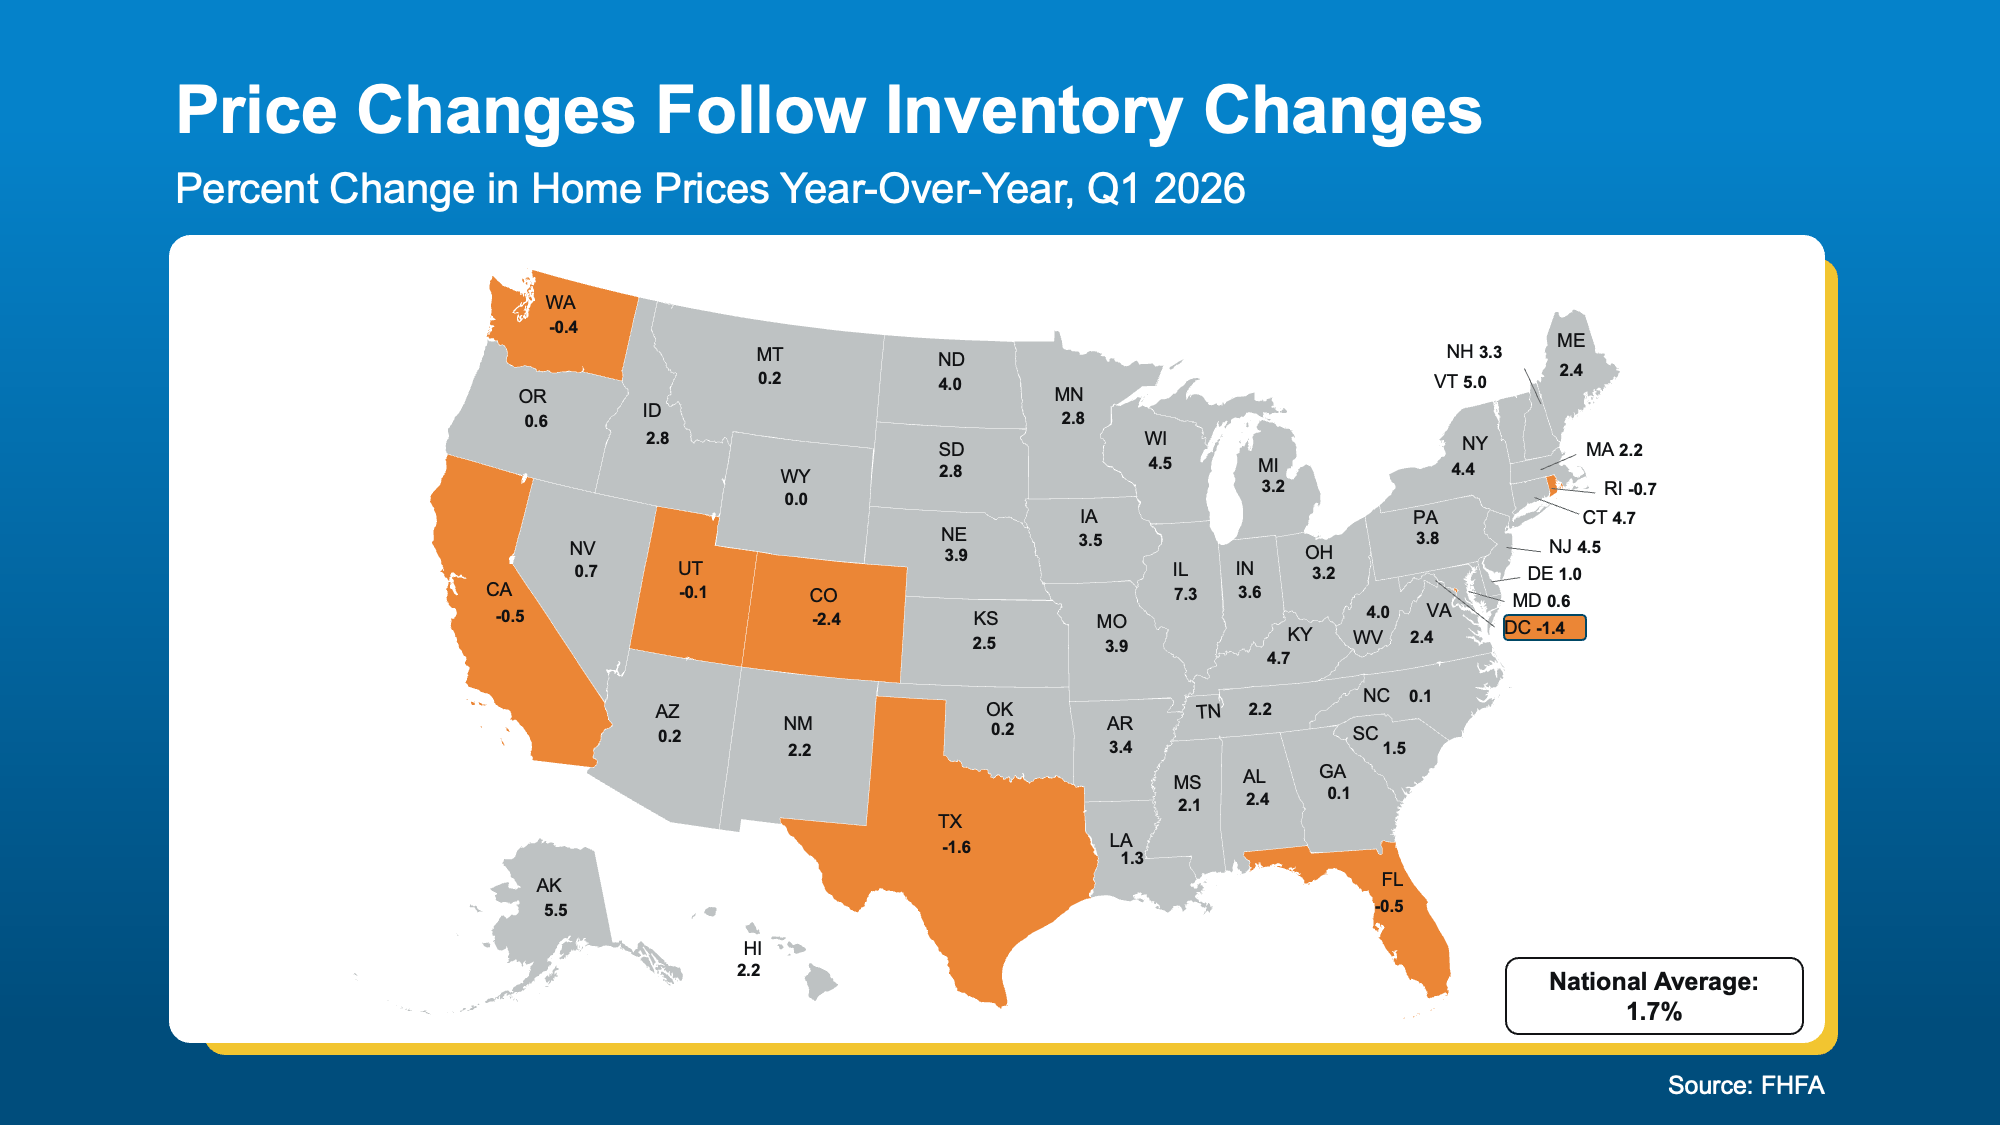
a map of the united statesNow, let’s look at the latest Federal Housing Finance Agency (FHFA) data to see what’s happened to home prices in those same states over the past year (again, you’ll want to focus on the orange in the next map). 

See how those line up pretty closely with the areas seeing more homes for sale today?

The overlap isn’t a coincidence. It’s cause and effect. 
a map of the united states

The national average of 1.7% price growth is accurate, but it’s an average of two very different stories happening at the same time – the few areas experiencing mild declines and the overwhelming majority that are still seeing prices rise.

What This Means If You’re Buying or Selling 

If you’re a buyer, the market you’re shopping in matters a lot right now. In places like Texas, Colorado, or Florida, you may have real negotiating power – more choices, less competition, and sellers who are more motivated to make a deal. In tighter markets like much of the Northeast, you’re still likely facing a lot of competition.

If you’re a seller, pricing strategy is everything. In markets where inventory has risen, overpricing is one of the fastest ways to linger on the market and eventually sell for less than you would have with the right price from day one. In markets where inventory is still low, you’re in a strong spot, but getting your price right still matters if you want to attract serious buyers quickly. Either way, that’s where a local real estate agent earns their keep.

Bottom Line

When it comes to prices, where you are matters more than ever right now, and a local real estate agent is the best person to help you make sense of it.

Reach out to a local real estate agent today and work together to build a plan that fits your market.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
That House That’s Been Sitting Could Be Your Best Shot at a Deal

That House That’s Been Sitting Could Be Your Best Shot at a Deal Simplifying The Market

Open up a home search and you’ll see them. Listings that have been on the market for two months. Three. Some longer.

Most buyers scroll right past them, assuming something’s wrong with the house. But that instinct could be costing you, since the longer a home sits, the more motivated the seller usually gets.

Where Some Buyers Are Finding Better Deals

If affordability has been your #1 hurdle to buying, here’s a surprisingly simple strategy that could help you finally get your foot in the door. Start with the homes that have been sitting the longest. That’s often where the best deals are.

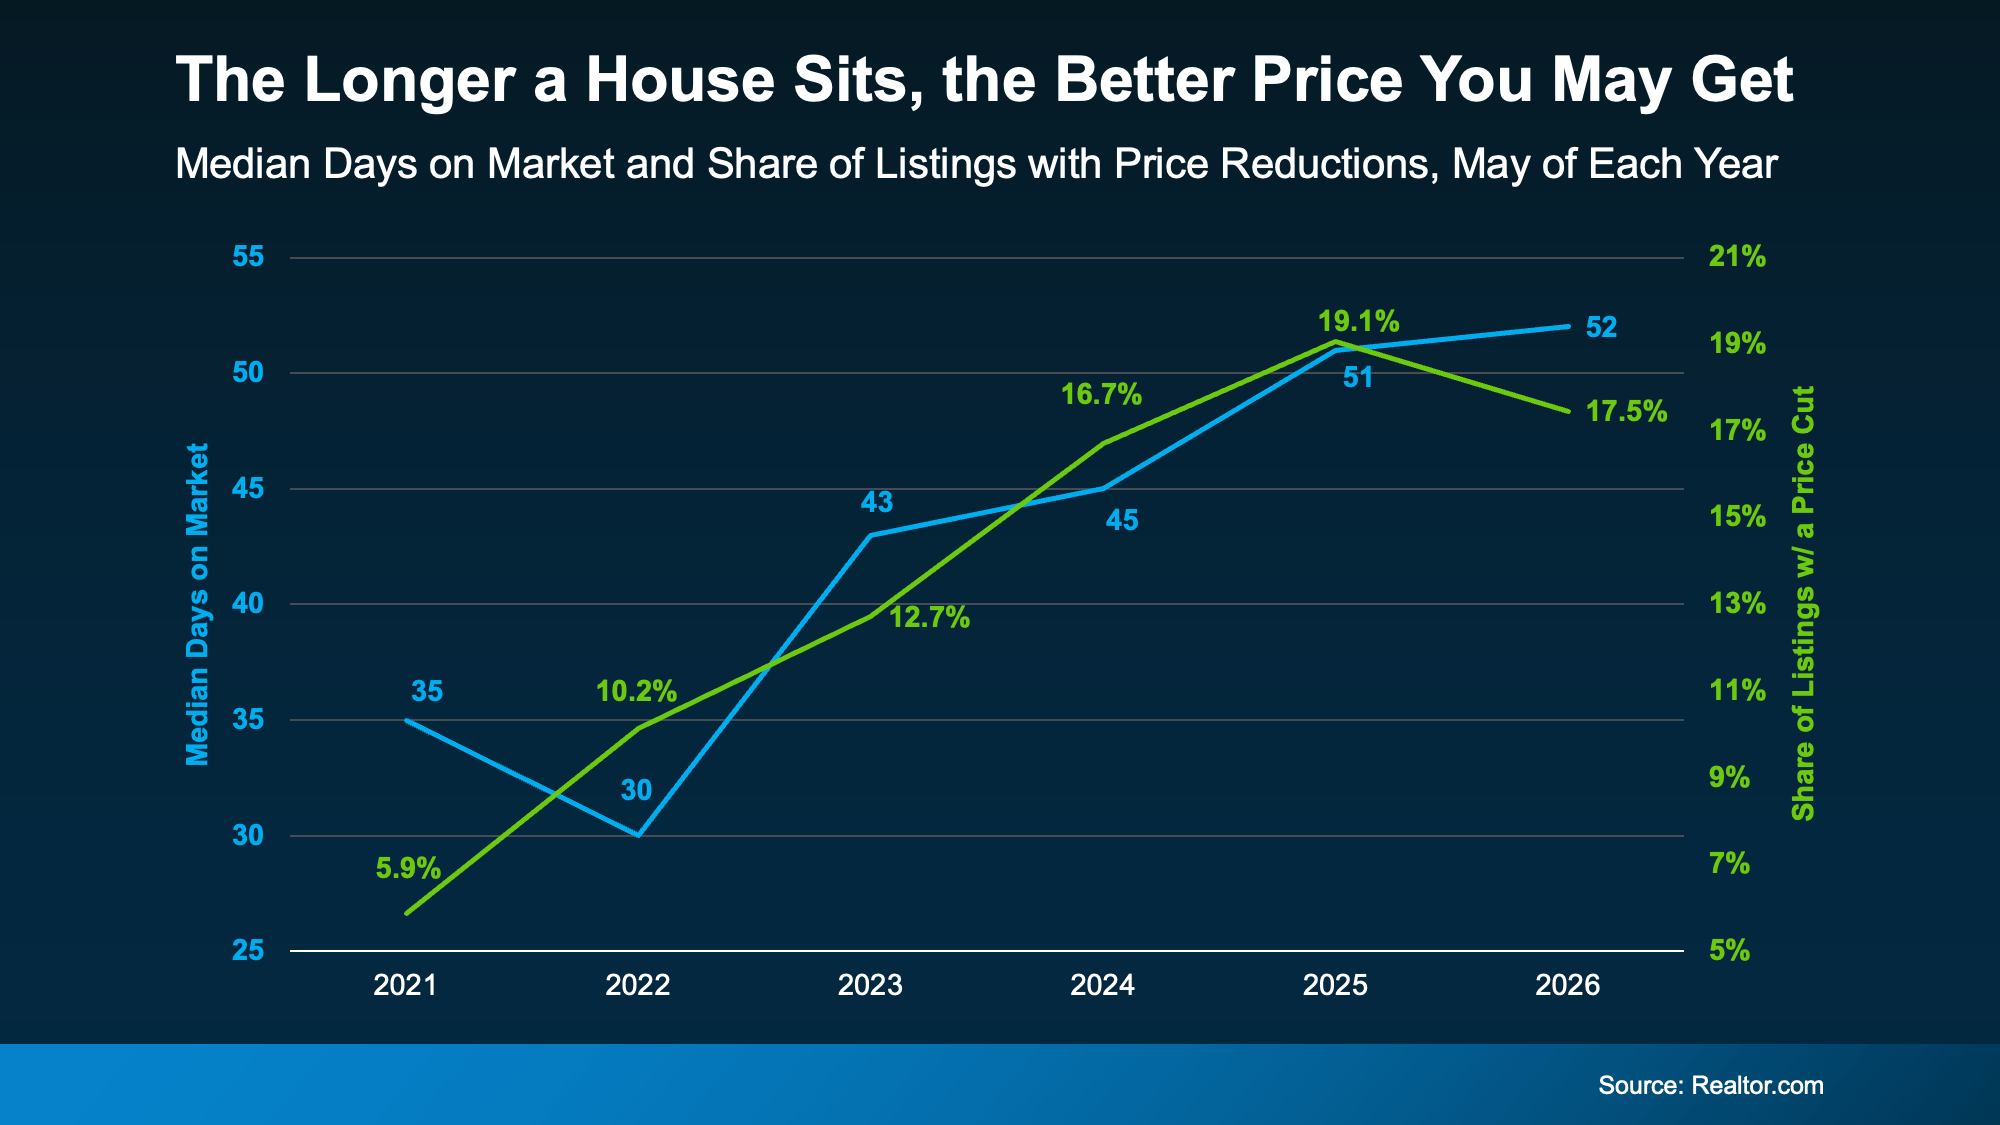
Here’s why. Data from Realtor.com shows there’s a connection between longer time on the market and lower sales prices. Basically, the longer a house sits, the more likely it is that the seller will reduce the price (see graph below):

a graph with numbers and lines

The blue line tracks how long homes stay on the market, while the green line tracks the share of homes getting a price reduction. As one climbs, so does the other.  

And if you focus on these homes that are just sitting and waiting, the opportunity for you is bigger than you may think right now.

Redfin data shows there’s $347 billion worth of stale listings on the market right now – more than ever before for this time of year. So, ask your agent to filter listings for you from oldest to newest. The home that fits your budget might already be there. Just further down the list than you thought.

Lingering Doesn’t Always Mean Something’s Wrong 

Let’s say you do that and something catches your eye. Still, you might be questioning why the home has been sitting in the first place. Just remember, sometimes it has nothing to do with the home itself.

According to Redfin, common causes are:

  • The asking price was set too high to start

  • The home didn’t show well online

  • There are a lot of homes for sale in the area, so it just got buried

So, nothing that’s necessarily a dealbreaker, or even anything that’s wrong with the home itself. If there’s a real issue, a thorough inspection will surface it. And that’s information you can use to negotiate. Not a reason to assume it’s a house worth skipping over.

How To Turn a Lingering Listing into a Win

So how do you capitalize on a lingering listing? According to USA Today, you have two main levers to pull.

The first is price. Work with your agent to study what comparable homes recently sold for, then build an offer around that. Coming in below asking price is fair game when a home has been sitting.

The second is concessions. If a seller won’t budge much on price, they may still help in other ways, like covering some closing costs, repair credits, or even a mortgage rate buydown that lowers your monthly payment.

A local agent has the context to tell which homes are the real opportunities and which are skippable.

Bottom Line

A house sitting on the market isn’t always a glaring red flag. In today’s market, it may be your best opportunity yet.

For help deciding which lingering listings are actually worth a second look, connect with a local real estate agent.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Is It Still a Seller’s Market? Here’s What the Data Says.

Is It Still a Seller's Market? Here's What the Data Says. Simplifying The Market

Remember a few years back when sellers held all the power and buyers were stuck offering way over asking or waiving inspections just to get a chance at the house? In many markets, those days are behind us.

While it’s going to vary by area, more metros are slowly shifting to favor buyers, and the market is starting to look a lot more like a two-way street again.

And that balance is something we haven’t had in a while.

Whether you’re buying or selling, here’s what you need to know about what’s changing and what it means for your move.

The Most Buyer-Friendly Market in Years

The national data tells an interesting story right now. According to Realtor.com:

“The national housing market is balanced but gradually loosening as the cycle moves in a more buyer-friendly direction . . .“

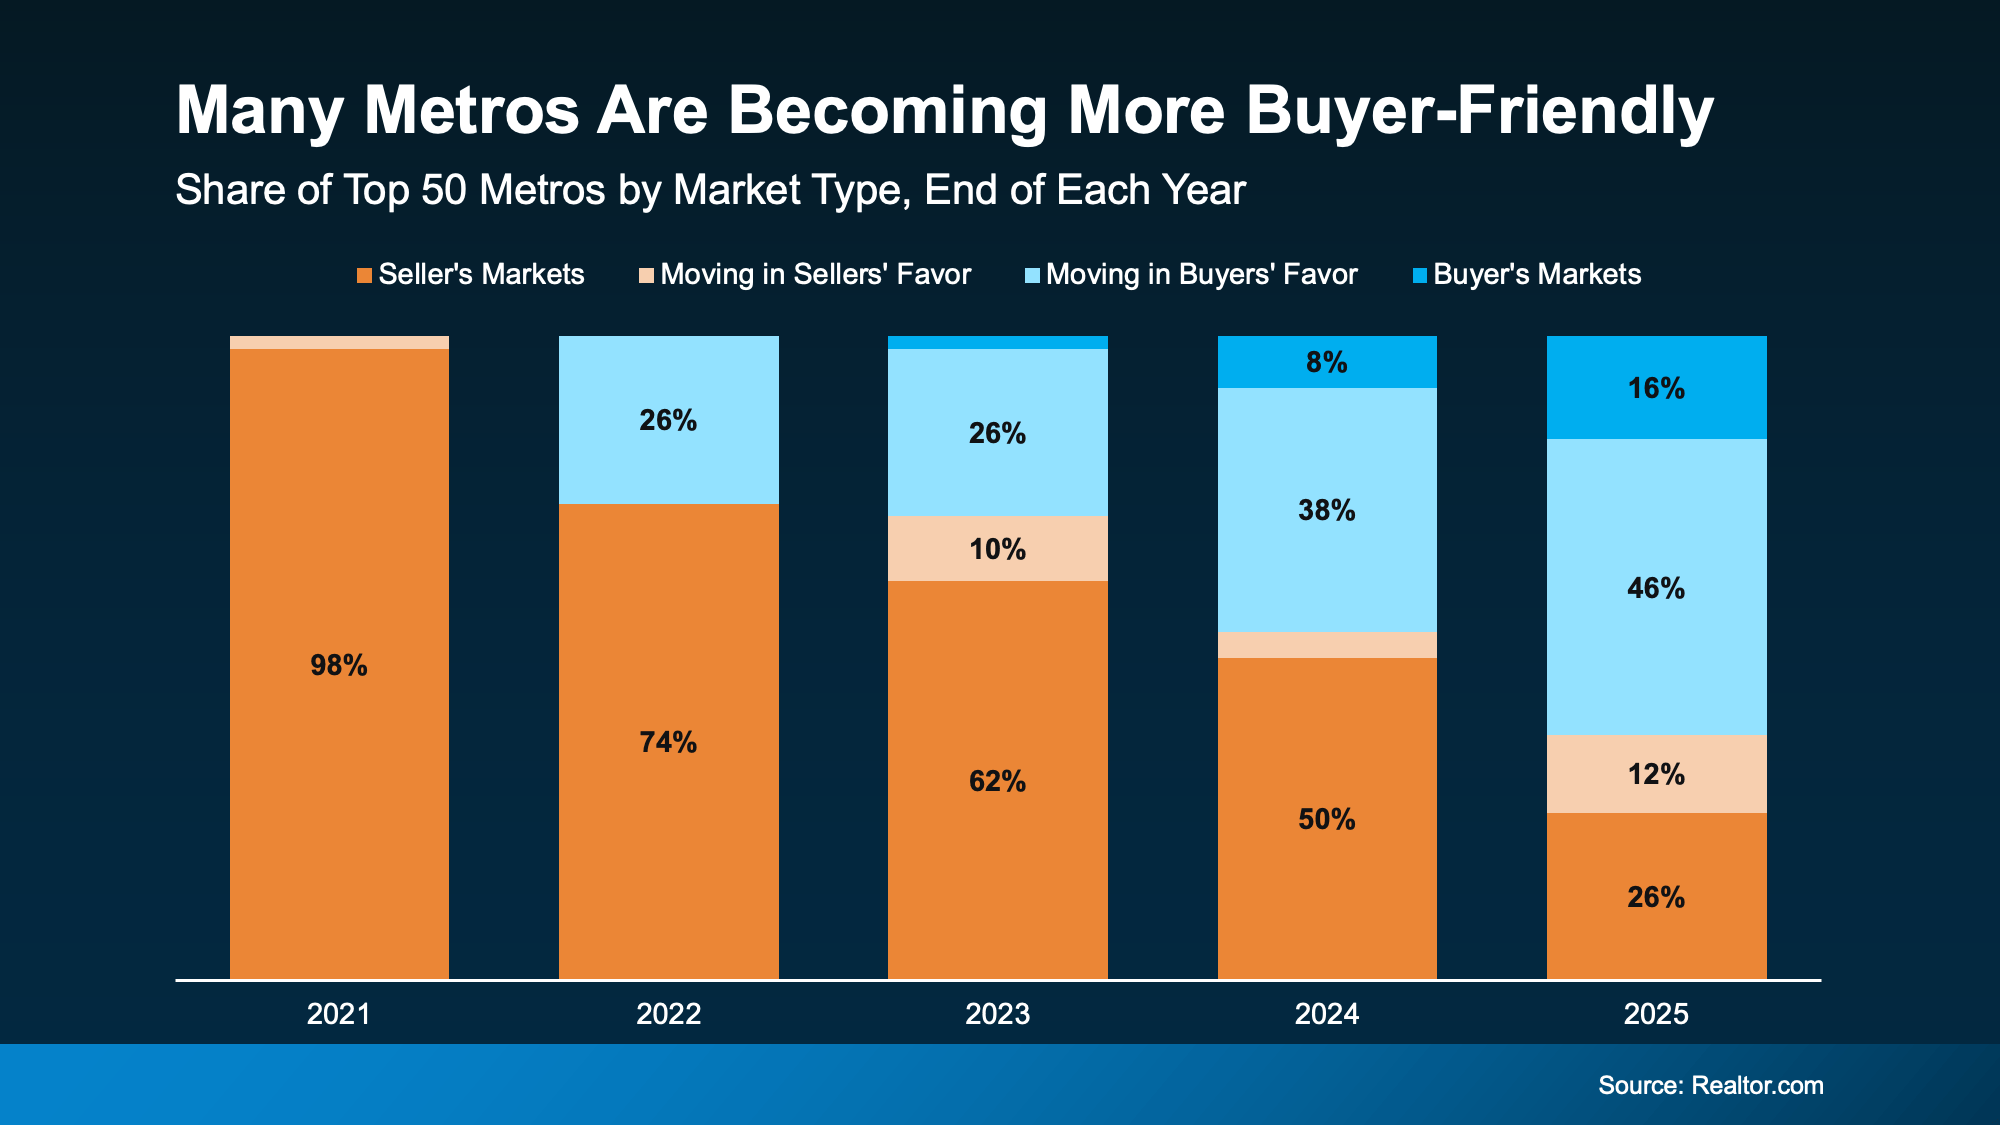
That’s because, over the past few years, more and more metros have been flipping back to more buyer-friendly terms as inventory’s grown. And when you zoom in on the latest Realtor.com data for the top 50 metro markets over time, the trend becomes really clear (see graph below).

Back in 2021, almost all major metros were seller’s markets. By the end of 2025, only 1 in 3 still favored sellers. That’s an obvious shift.

a graph of sales

And that changes how the market is going to feel for everyone. Sellers shouldn’t still expect 2021 conditions, but neither should buyers. At least, not generally speaking.

It’s Not the Same Story Everywhere

That said, who has the power ultimately depends on where you live. While more metros are leaning buyer-friendly lately, there are still plenty of strong seller’s markets right now, too.

It really comes down to how much housing supply and demand there is in your area. And that varies enormously by region.

Sun Belt cities like Austin, Tampa, and San Antonio saw major building booms in recent years, giving buyers more options and more negotiating room. Meanwhile, cities in the Northeast and Midwest – think Rochester, Hartford, and Buffalo – didn’t see that same wave, so inventory stayed tight and competition stayed fierce. As Jeff Ostrowski, Housing Analyst at Bankrate, explains:

“The formerly hot Sun Belt markets have cooled, while the Northeast and Midwest have stayed hot. The big driver here is construction activity. The softest markets now [have] experienced big booms that spurred new building, and that has led to a large supply of new and existing homes on the market in those places.”

Practical Advice for Your Move

To find out who has the power in your local market, talk to an agent. Because knowing what’s happening locally is going to be the key to setting the right strategy for your move.

If the market is working in your favor, great. Lean in and use it to your benefit. But if it’s not, all hope isn’t lost. Your agent can help you figure out how to approach any market.

Here’s some practical advice if there’s a mismatch between your goal and local market conditions.

If you’re buying in a seller’s market:

  • Get pre-approved before you start shopping. It shows sellers you’re serious.

  • Be ready to act fast when the right home hits the market.

  • Consider offering a quick closing date or flexible terms.

  • Work closely with your agent to craft a competitive offer.

If you’re selling in a buyer’s market:

  • Price it right from day one. Overpricing will cost you time and money.

  • Focus on curb appeal and staging to stand out in areas with more inventory.

  • Be open to offering incentives, like covering closing costs or a home warranty.

  • Expect buyers to negotiate and be ready to be flexible.

Bottom Line

Right now, local markets are moving in very different directions. And your strategy as a buyer or seller should reflect your market.

Want to know which way your local market is leaning and what that means for your move? Talk to a local real estate agent.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Think Home Prices Will Crash? Here’s What the Experts Actually Expect.

Think Home Prices Will Crash? Here's What the Experts Actually Expect. Simplifying The Market

One of the biggest reasons buyers are still sitting on the sidelines is because they think home prices are going to come down.

  • Some believe a crash is coming and they’ll get a better deal if they hold off.

  • Others worry they’ll buy now and watch their home’s value fall later.

And nobody wants to overpay or buy right before values drop. But here’s the question worth asking:

What if the crash you’re waiting for isn’t actually coming?

Because that’s what the latest data suggests.

Experts Are Not Calling for a Crash

If you’ve spent any time online lately, you’ve seen posts claiming home prices are about to come crashing down. And it’s true that some markets are seeing small price declines right now.

But that’s not the same thing as a nationwide crash.

While some places are going through a price adjustment, Realtor.com data shows home prices are still rising in 71% of housing markets across the country.

The trouble is, since negative news sells, you’re seeing more coverage about how a handful of markets are seeing declines, than how the majority are still seeing prices rise. And that’s unfortunate.

It’s exactly why a lot of buyers end up with the impression that prices are falling everywhere when they’re not. So how do you really know where prices are really headed from here?

That’s where the Home Price Expectations Survey (HPES) from Fannie Mae comes in.

Home Prices Will Rise for the Next 5 Years

Every quarter, more than 100 economists, housing experts, and market analysts are asked where they think home prices are headed based on the latest data available.

And despite all the uncertainty in today’s market, there’s one thing they largely agreed on:

They don’t think a crash is coming.

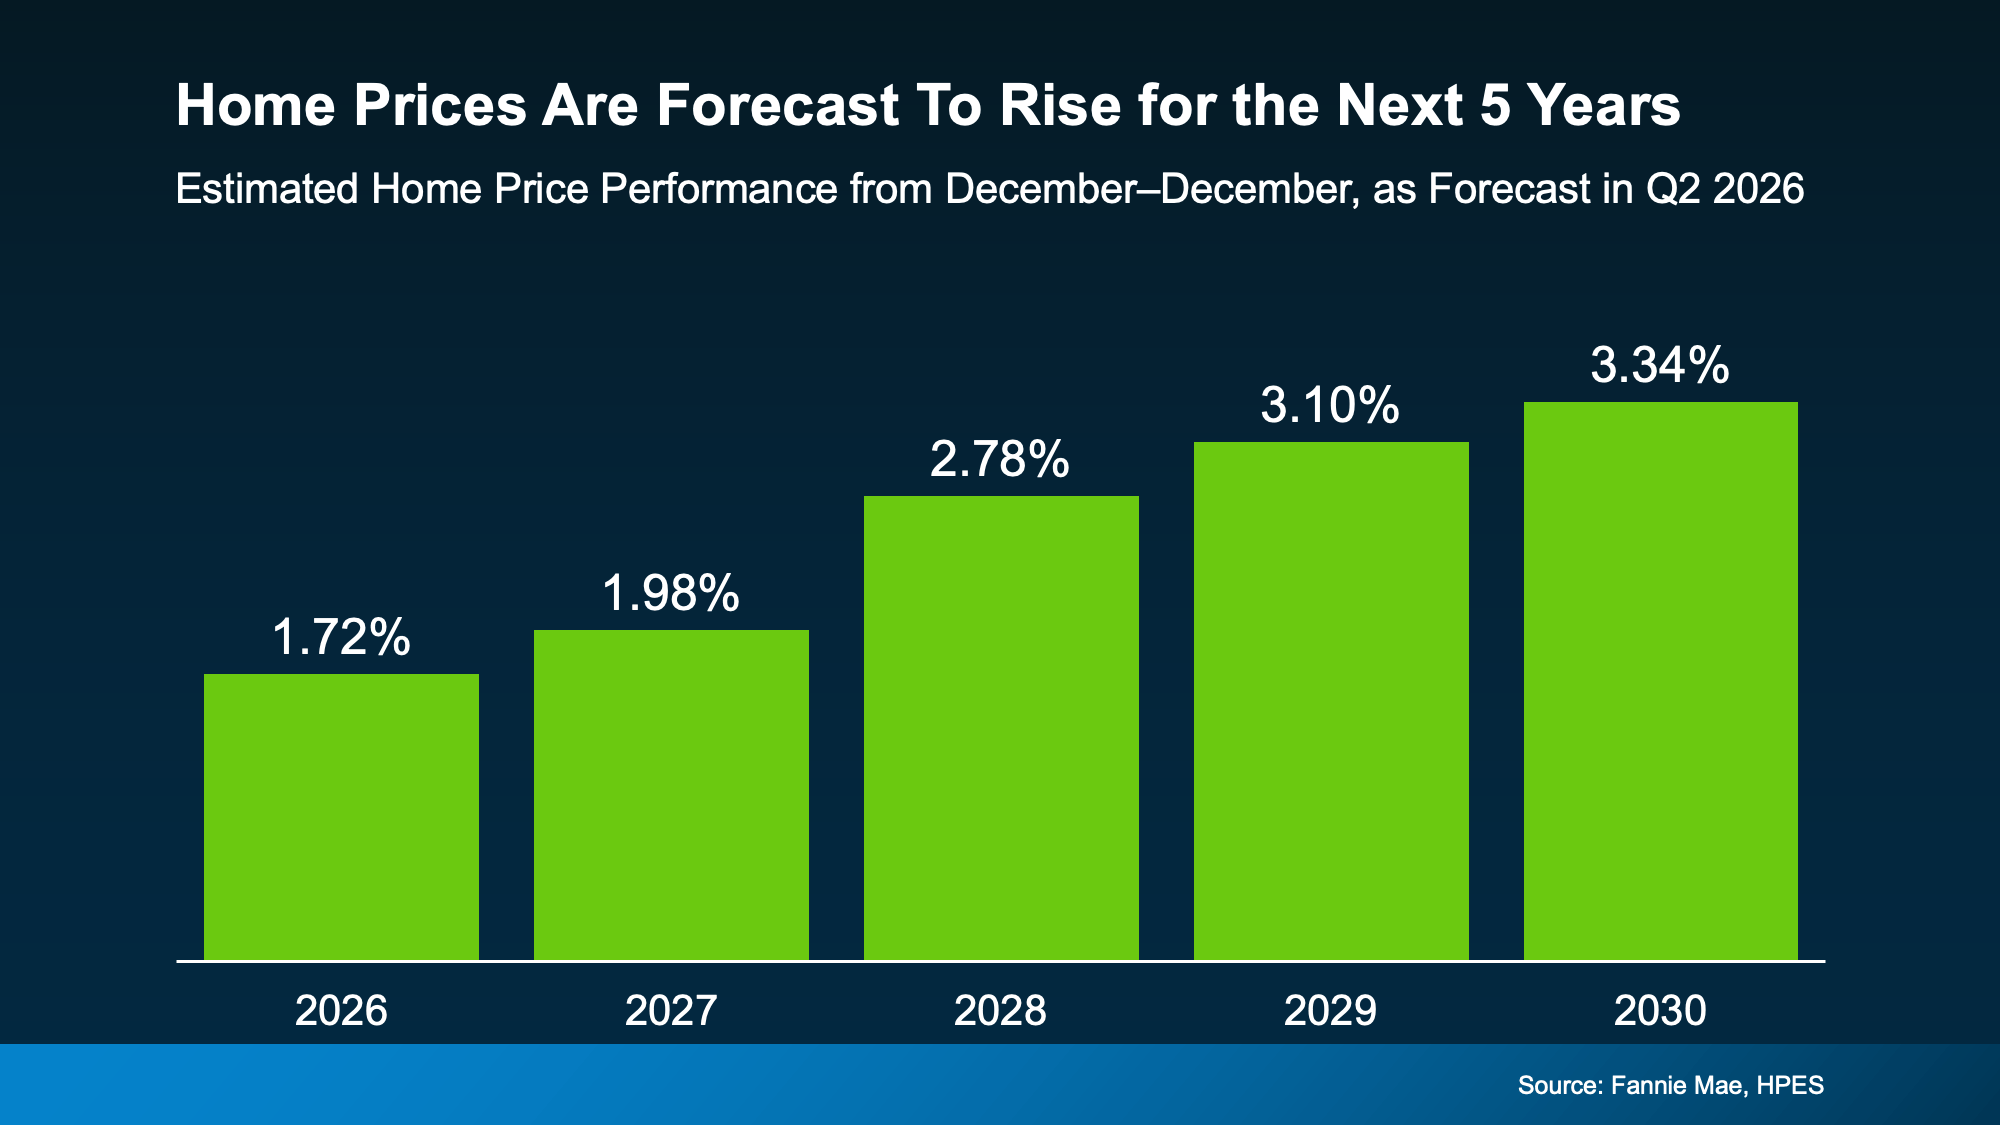
In fact, the average of all of their forecasts calls for home prices to rise every year for at least the next 5 years (see graph below):

a graph with green rectangles and numbers

The point is that the overwhelming expectation isn’t for prices to fall. It’s for prices to rise at a more normal pace. And just in case you’re looking at the forecasts and saying: “of course they’d say that” – know that this survey doesn’t just include optimists. It includes pessimists too.

Even the Pessimists Aren’t Predicting a Crash

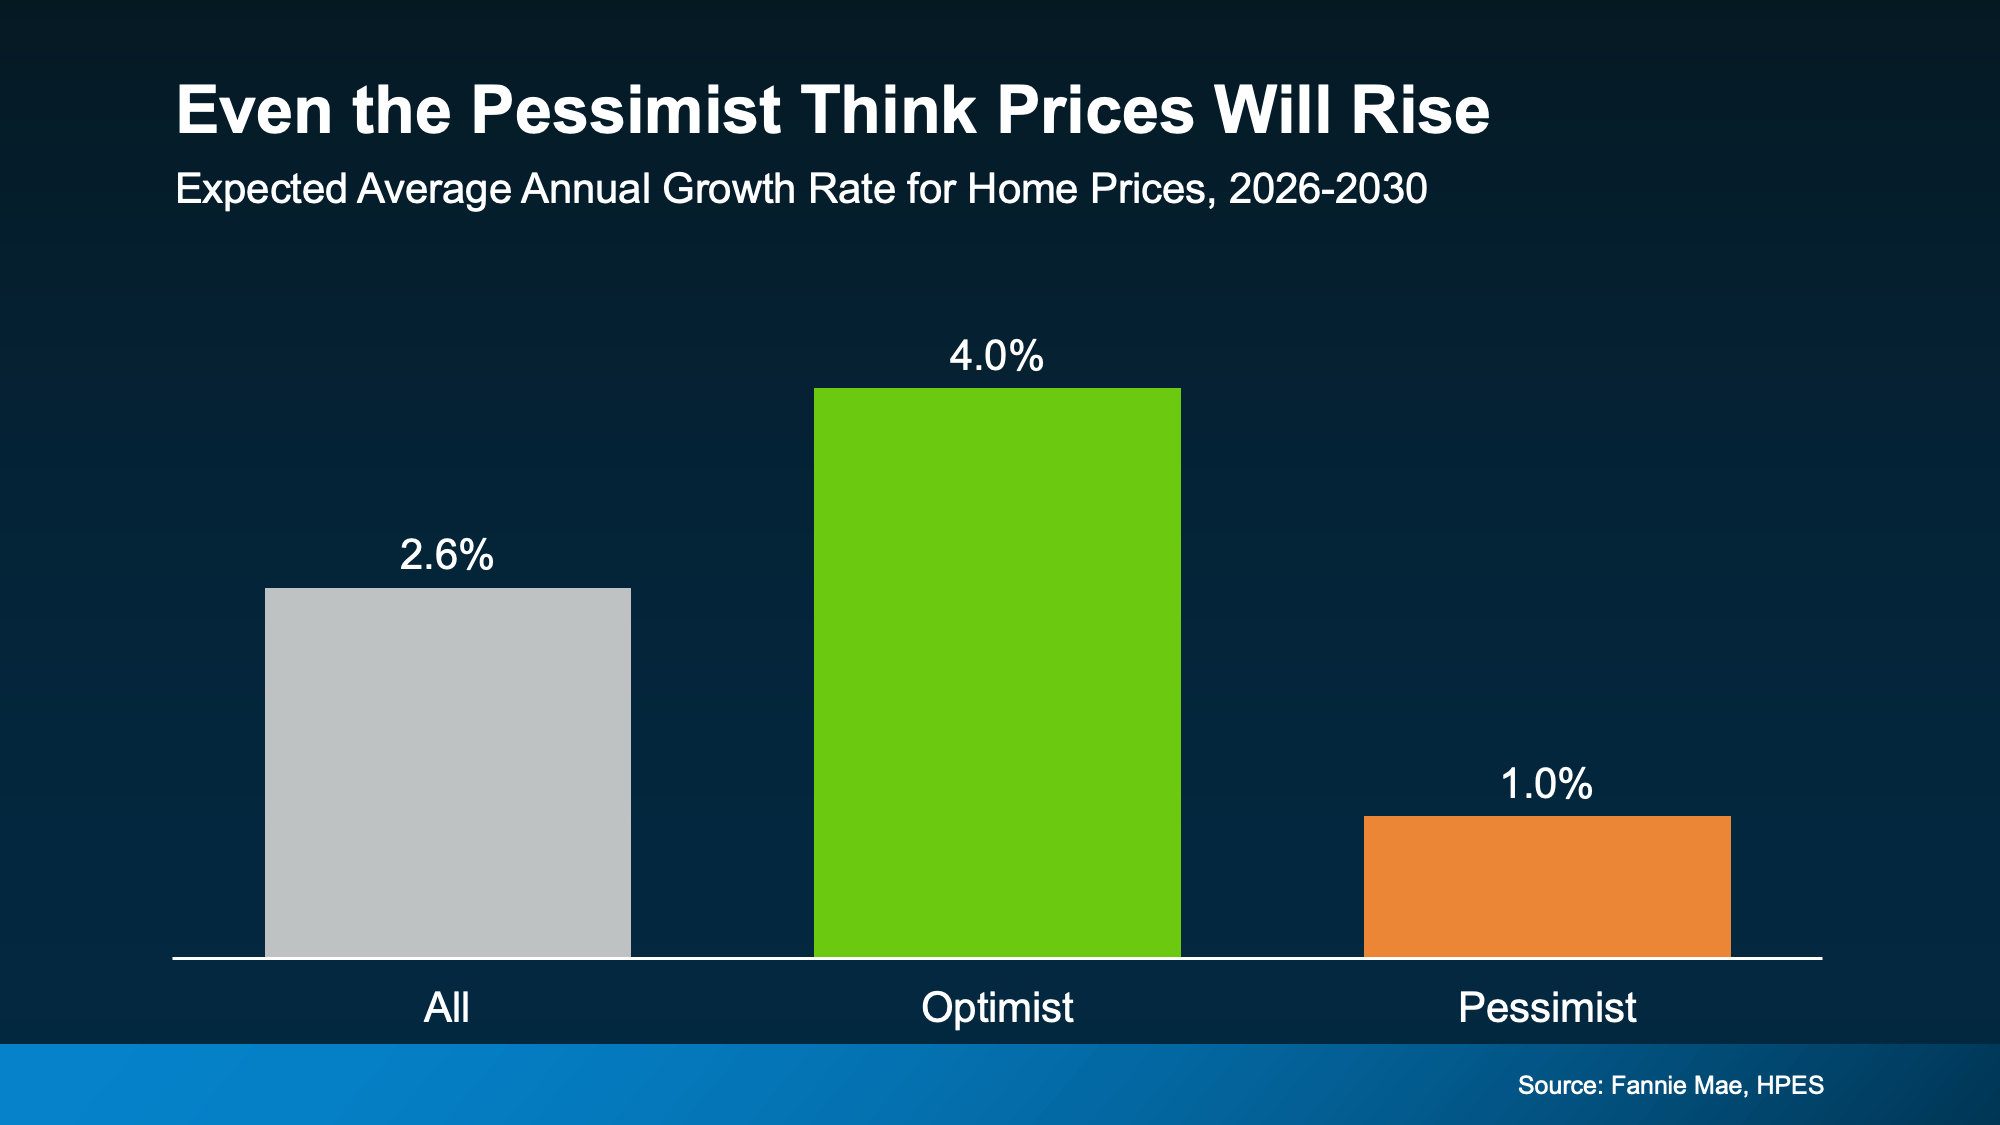
Researchers broke the panel into groups based on how bullish or bearish they were about housing. The result? Even the most pessimistic group still expects home prices to climb over the next five years.

Optimists think we’ll see prices go up roughly 4% a year. Pessimists say it’ll be closer to 1%. The reality may be somewhere in the middle.

a graph of growth rate for home prices

Think about that for a second. The debate among experts isn’t whether prices will crash. It’s how much they’ll rise.

That’s a very different conversation than the one happening across social media.

This Means Waiting Could Actually Cost You

So, if you’re putting off your move until prices come down, you may be disappointed. According to the experts, a widespread crash isn’t in the cards.

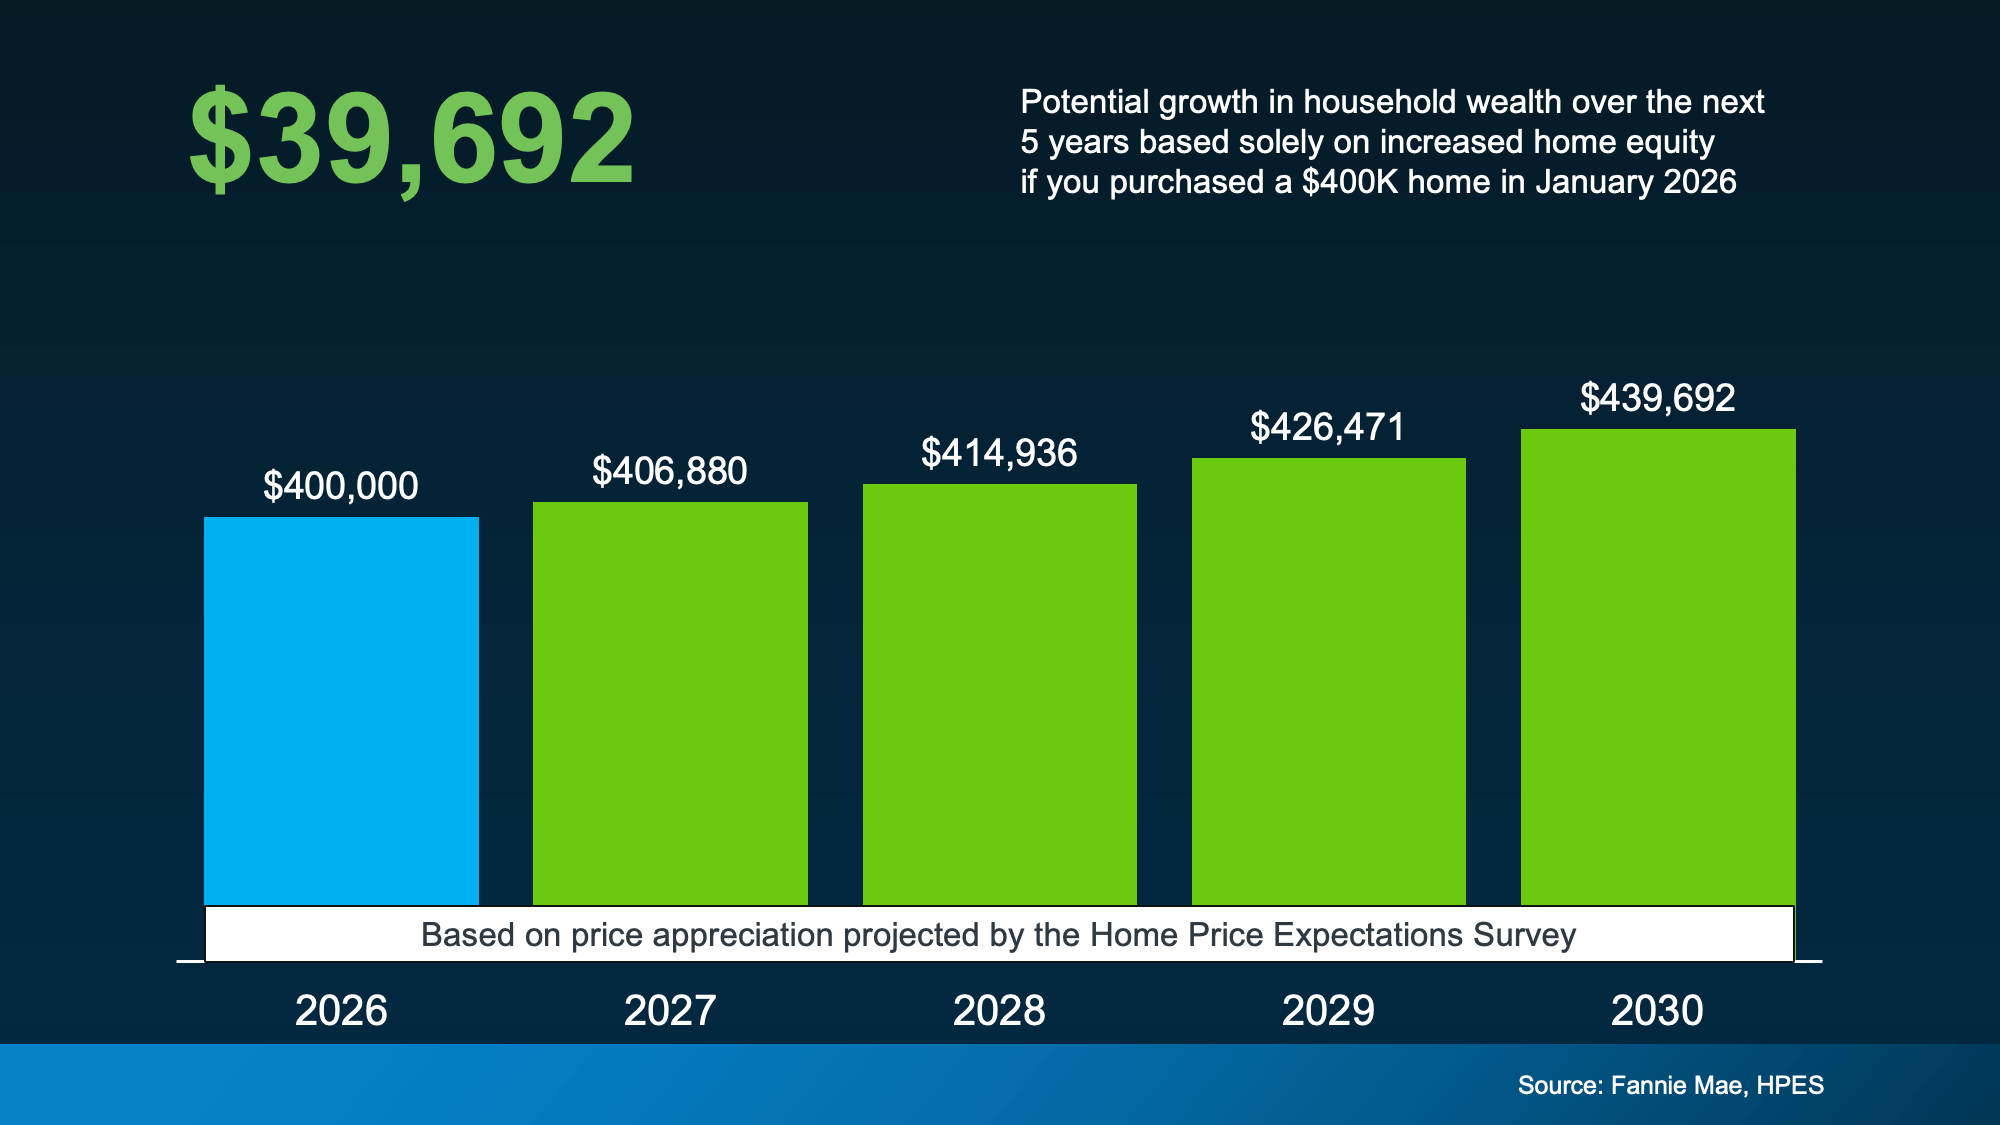
In fact, based on the HPES forecast, a buyer who purchased a $400,000 home this January would gain nearly $40,000 in equity over the next five years from appreciation alone, even in this more moderate market (see below):

a graph of growth in a chart

Of course, this all depends on local market conditions. This forecast is a national average. But broadly speaking, if the experts are right, the bigger risk isn’t that prices will crash. It may be waiting for a crash that never comes.

Because depending on your market, if you wait, you could be missing out on $40k in equity or paying 40k more in 5 years for the same house.

Bottom Line

A lot of buyers are waiting because they think prices will fall, but that’s not what the experts are saying.

If you’re trying to decide whether waiting still makes sense, connect with a local agent. They’ll help you understand what’s happening in your local market and what it could mean for your plans.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know.

Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know. Simplifying The Market

A few years ago, sellers could get away with saying “no” to just about everything.

No repairs.

No concessions.

No negotiation.

If buyers wanted the house, they pretty much had to take it on the seller’s terms. But now that inventory’s grown, negotiations are becoming a normal part of the process again.

That’s why one of the most important things sellers need to understand right now is this:

The goal isn’t to “win” every negotiation.

Sometimes, it’s worth meeting buyers where they are to get a deal done, fast. One example? Helping with a buyer’s closing costs.

Let’s break that down, so you know what to expect if it comes up in your sale.

What Are Buyer Closing Costs?

Closing costs are the extra expenses buyers pay on top of their down payment when they purchase a home. Freddie Mac gives some examples:

  • Loan origination fees

  • Appraisal and inspection costs

  • Title and attorney fees

  • Survey fees and more

Typically, buyer closing costs range from about 2% to 5% of the home’s purchase price. So, on the typical $400,000 home, that could mean anywhere from $8,000 to $20,000 out of pocket.

And in today’s affordability-challenged market, that upfront cash can be a major hurdle for some buyers – even if they can comfortably afford the monthly mortgage payment itself. 

That’s why more people are asking sellers for help.

And More Sellers Are Saying “Yes”

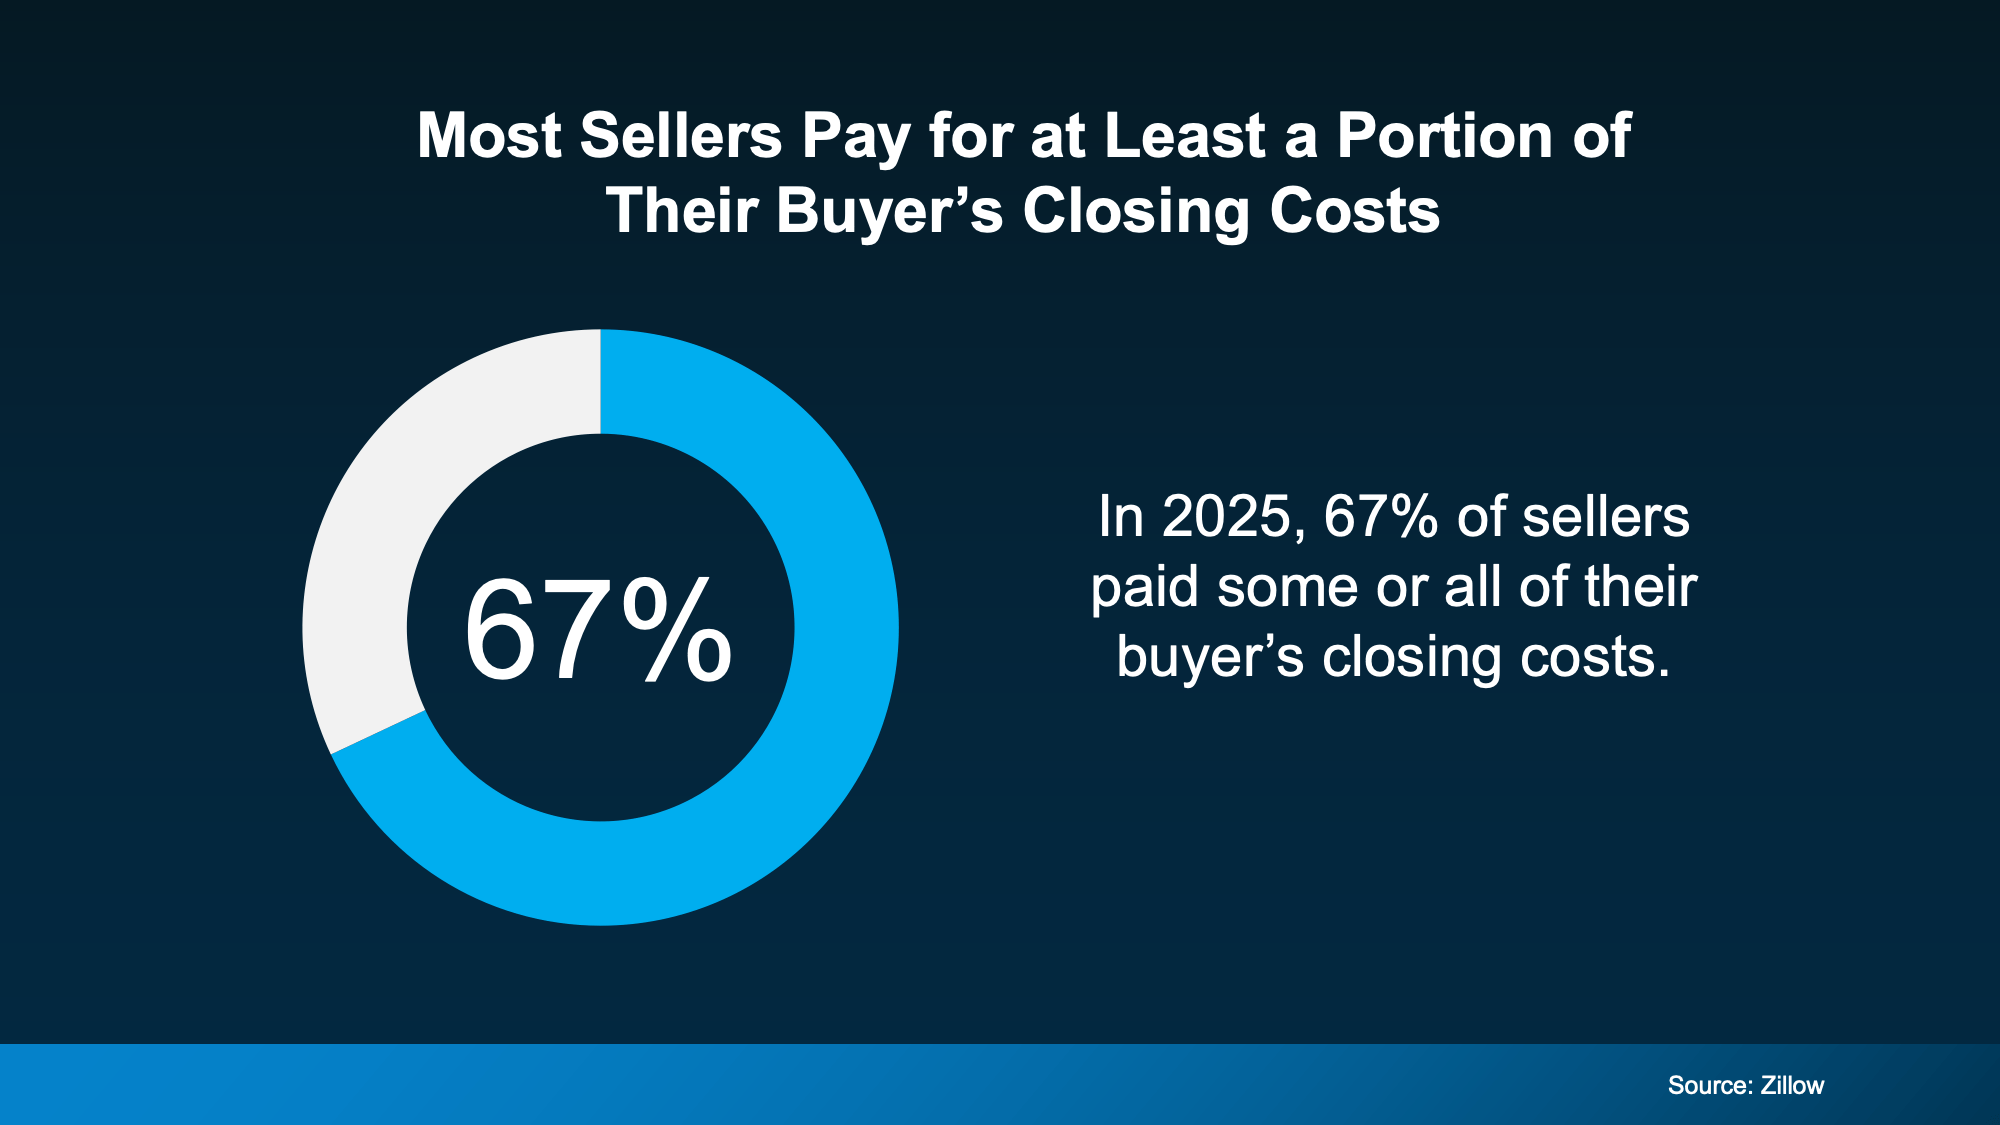
According to the latest data from Zillow, 67% of sellers reported paying some or all of the buyer’s closing costs in 2025 (see chart below):

a blue circle with white text

Now, that doesn’t mean every seller is doing it. And it definitely doesn’t mean every seller should. But it does show how common concessions have become as the market has shifted. And that’s important for you to know.

When Paying Closing Costs May Make Sense

This is where many sellers get stuck. They hear “help with closing costs” and immediately think: “Why should I pay for their expenses?”

But that’s not always the right way to look at it. You’ve got to consider who has the leverage in today’s market.

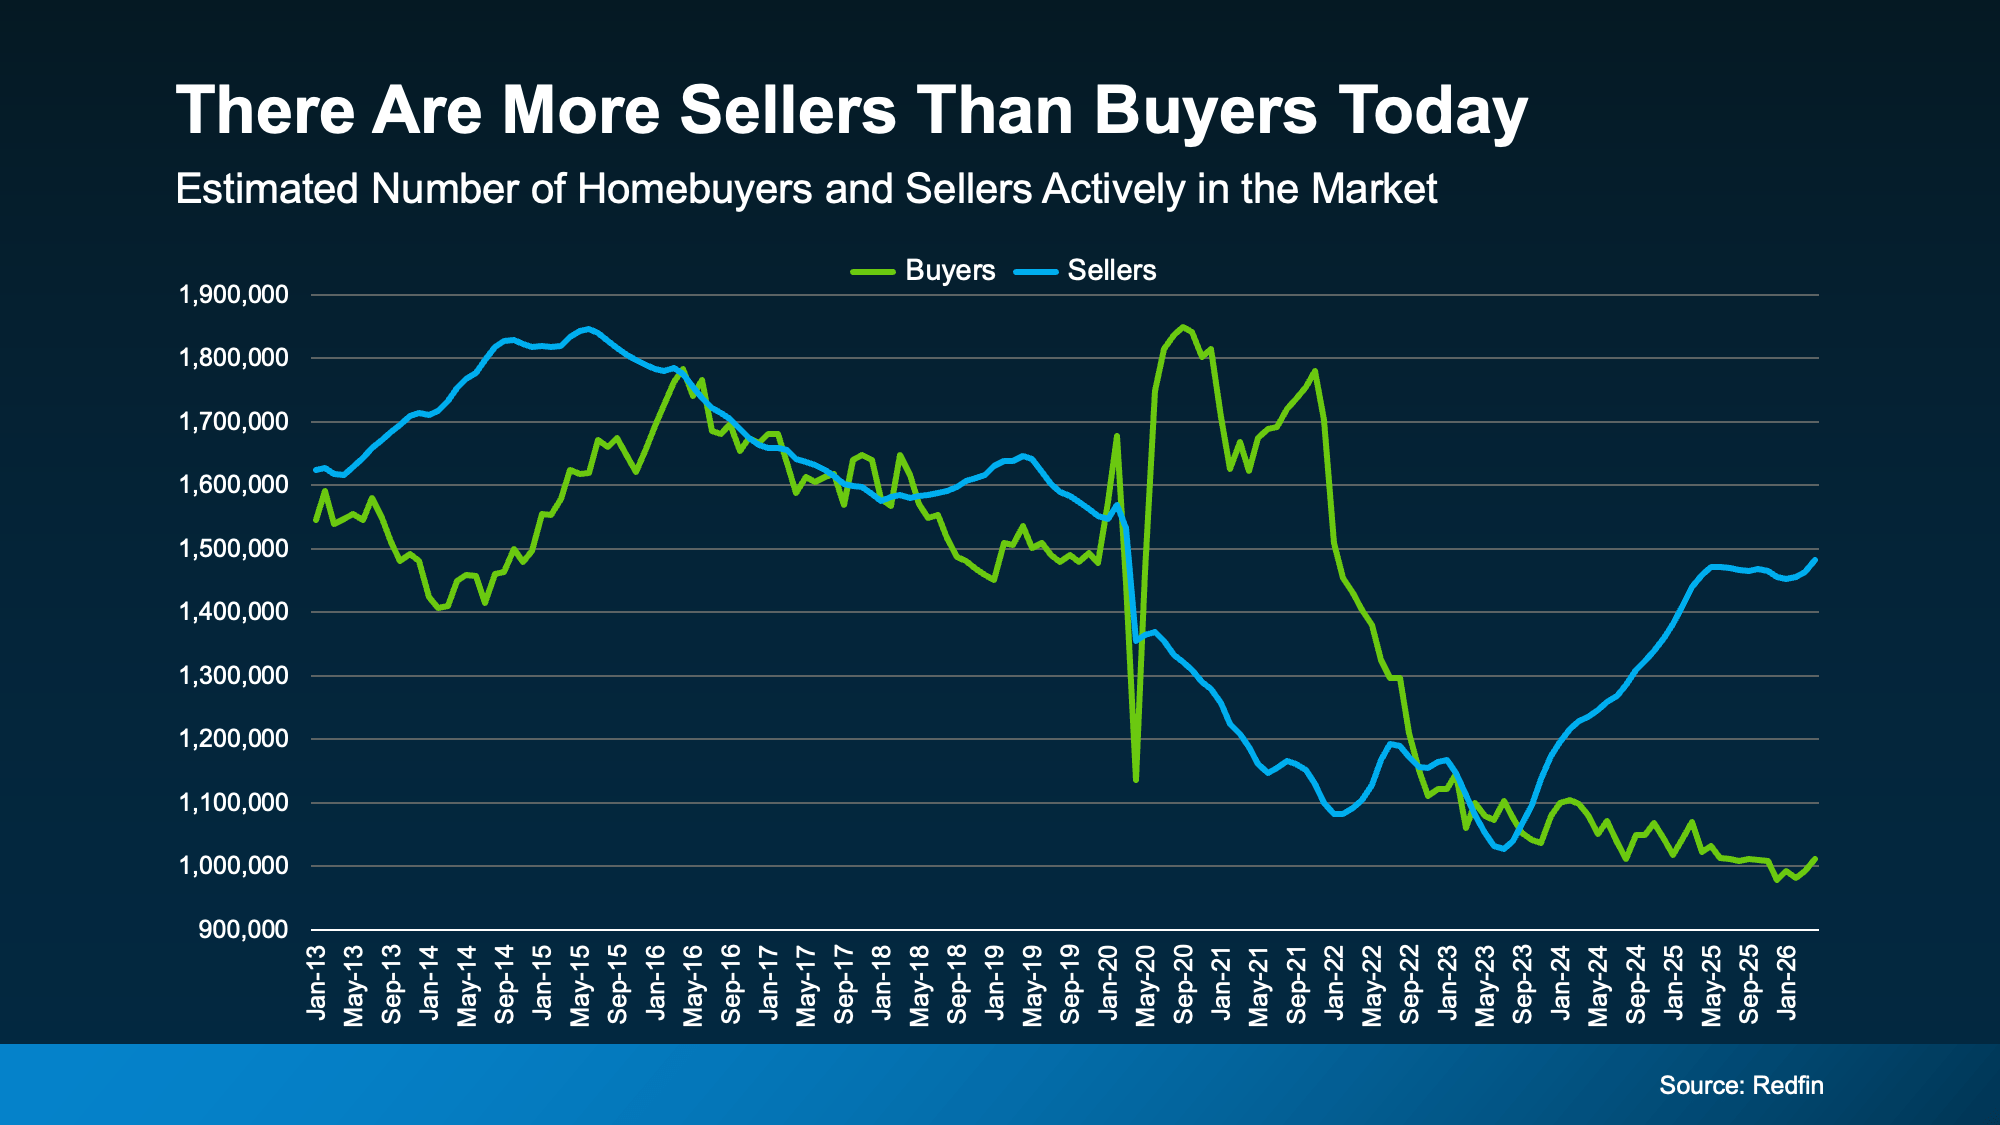
Redfin data shows there are more sellers than buyers active today. And that shifts the market dynamics (see graph below):

a graph of sales and buyers

That doesn’t mean every market favors buyers. Far from it. In some areas, homes are still selling quickly and sellers have plenty of leverage. But in others, buyers have more room to negotiate than they’ve had in years.

That’s why local market conditions matter so much when you make your decision.

For example, helping with closing costs may be worth considering if:

  • There are a lot of homes for sale in your area

  • Your house has been sitting on the market longer than expected

  • You’ve had showings, but no offers

  • You’re motivated to move quickly

  • Or you’re trying to keep a deal together during negotiations

After all, if it’s the thing that helps bring a serious buyer across the finish line, it could be well worth it.

Other Concessions You Could Offer Instead

Just remember, being flexible doesn’t mean saying “yes” to every request.  It means understanding which compromises actually help you accomplish your goals. Because there are always alternatives.

Redfin suggests considering other concessions if you’re not interested in helping with closing costs, like:

  • A home warranty

  • Repair credits

  • Flexible closing dates, or

  • Leave behind appliances or furniture

The right answer depends on what buyers in your market are asking for and what matters most to you. That’s exactly why working with an experienced local agent is so important.

Bottom Line

The sellers having the most success today are the ones who understand the market has changed and are adapting to meet it where it is.

Sometimes that means negotiating on closing costs. Sometimes it means offering something else. The key is knowing which concessions are worth it for your local market.

If you’re wondering what’s normal in your area, what’s worth negotiating, and where it makes sense to stand firm, connect with an agent.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Two Big Reasons To Move This Summer

Two Big Reasons To Move This Summer Simplifying The Market

A lot of people who want to move are telling themselves the same thing: “Maybe I’ll just wait until later this year once things calm down.” 

While waiting sounds like a good plan, there’s something worth knowing before you decide. Rates aren’t expected to change much, so if that’s the #1 reason you’re waiting, it may not pay off. And there may be other things you miss out on in the meantime. 

Historically, Summer is one of the strongest seasons of the year for both buyers and sellers. And if you delay your move until Fall or Winter, some of those opportunities may already be fading.

Buyers: Fresh Inventory Is Your Real Summer Advantage

One of the biggest frustrations buyers have faced over the past few years has been a lack of affordable options. Maybe you’ve run into that yourself:

  • You find a house you like, but it’s out of your budget.

  • You find something in your budget, but you don’t like it.

  • Or worse, nothing interesting hits the market for weeks.

Historically, Summer helps with that.

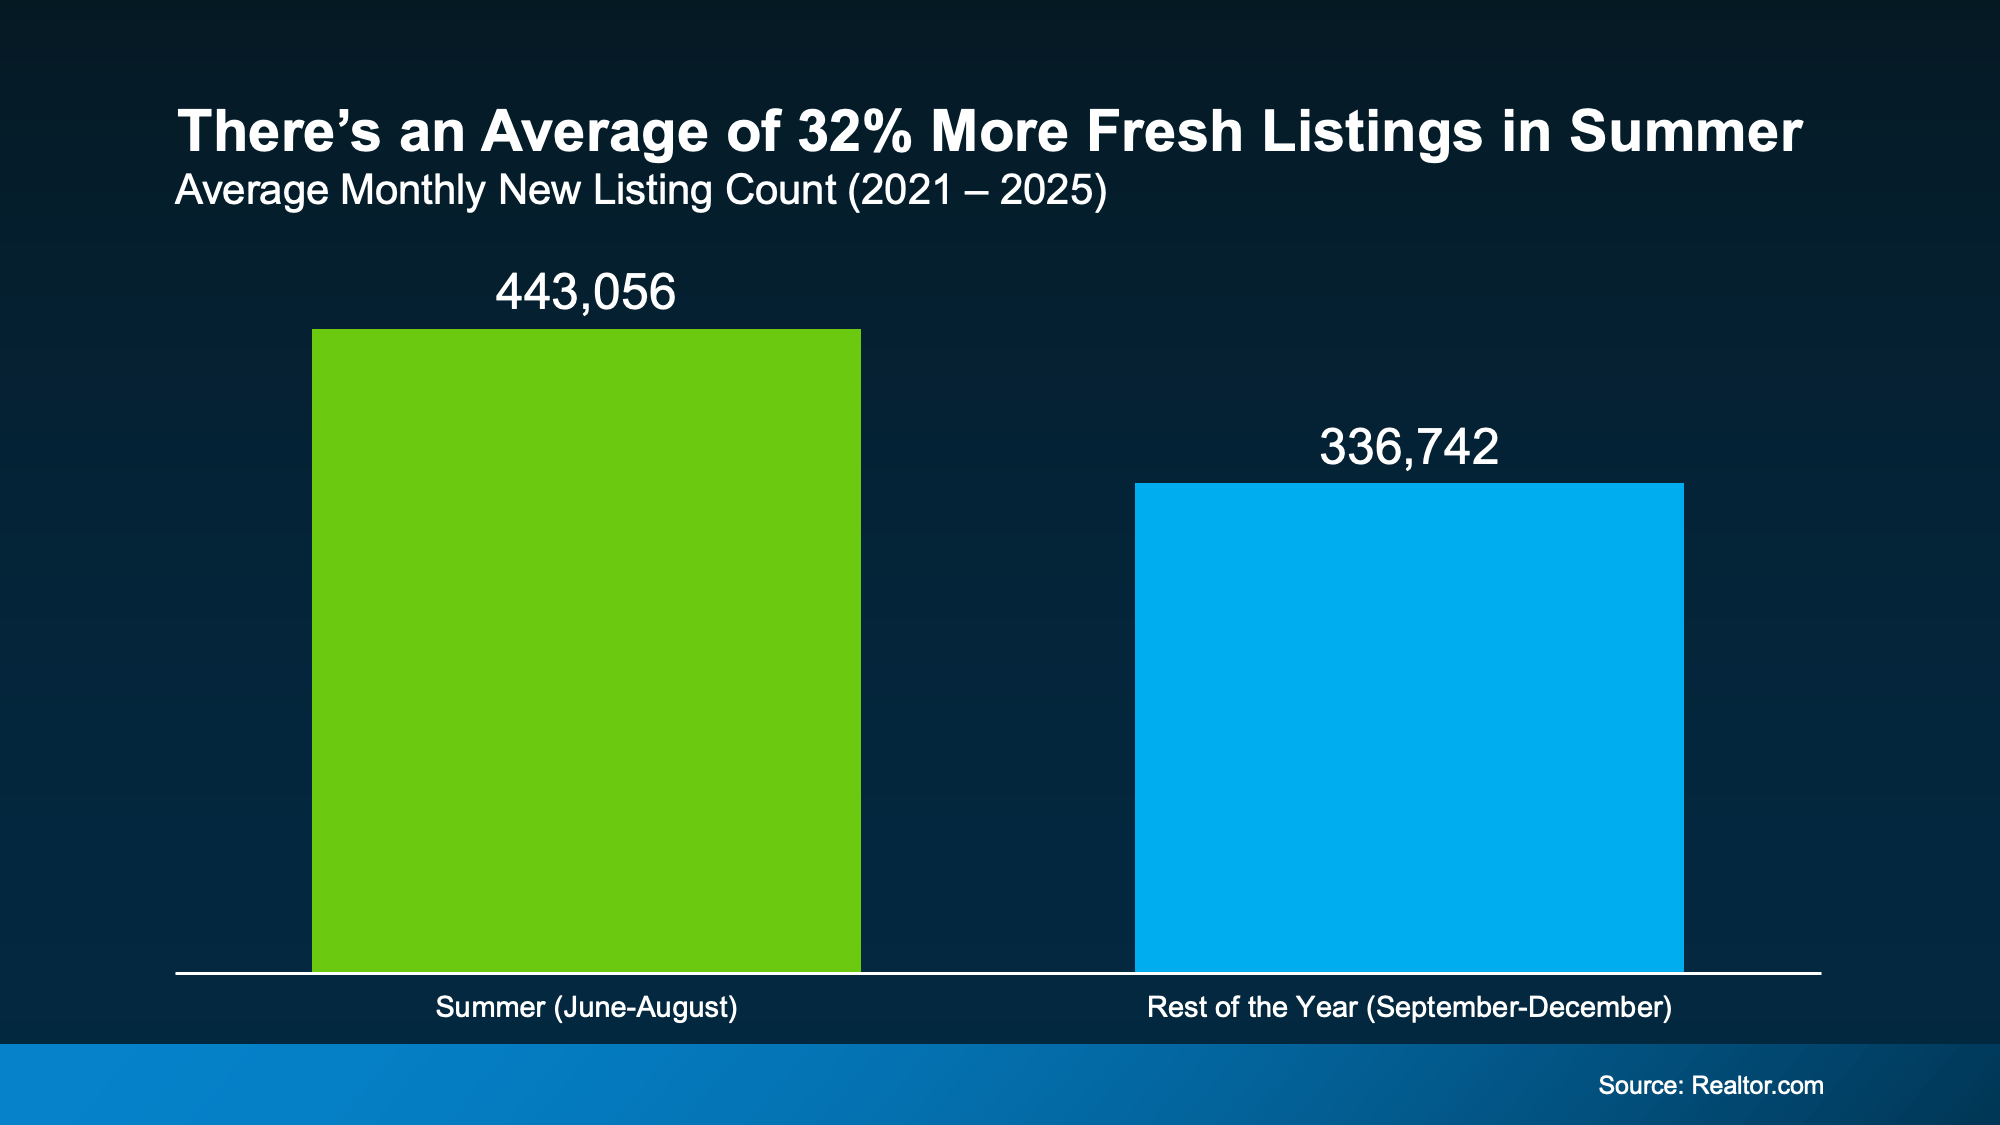
Looking at data from the last few years, Summer months consistently bring more sellers into the market than later in the year. And that gives buyers a real window of fresh choices.

According to Realtor.com, any given Summer month typically sees about 32% more fresh options than the average month from September-December.

a graph showing a number of prices

With more newly listed homes, there’s a better chance of finding one you like where the numbers actually work.

Because all it really takes is one home to completely change your search. And if you’ve got more popping onto the market to choose from, maybe one of those is exactly what you need. 

But keep in mind, this seasonal window isn’t open forever. Fresh inventory tends to slow down once Summer ends.

Many homeowners who planned to sell this year have already listed by then. Families who wanted to move before school starts have often already gotten it done, or at least, set it into motion. So, new listing activity usually cools as we head into Fall and Winter.

Of course, every year is different. But if finding the right home at the right price has been your biggest challenge, waiting until later in the year may not necessarily give you more options. In fact, recent history suggests it may do just the opposite.

Sellers: Homes Usually Sell for More in the Summer

If you’re thinking of selling, you may be considering holding off because you’ve seen headlines about lower asking prices, price cuts, and softer conditions in some markets. But those headlines don’t tell the whole story or convey just how much it varies by area.

Here’s what you really need to know. Even though the market’s becoming more balanced and some pockets are experiencing price declines, that doesn’t mean you’ve missed your chance to sell. 

Seasonality can still work in your favor no matter where you are. And this Summer could still give you the chance to sell for a good price.

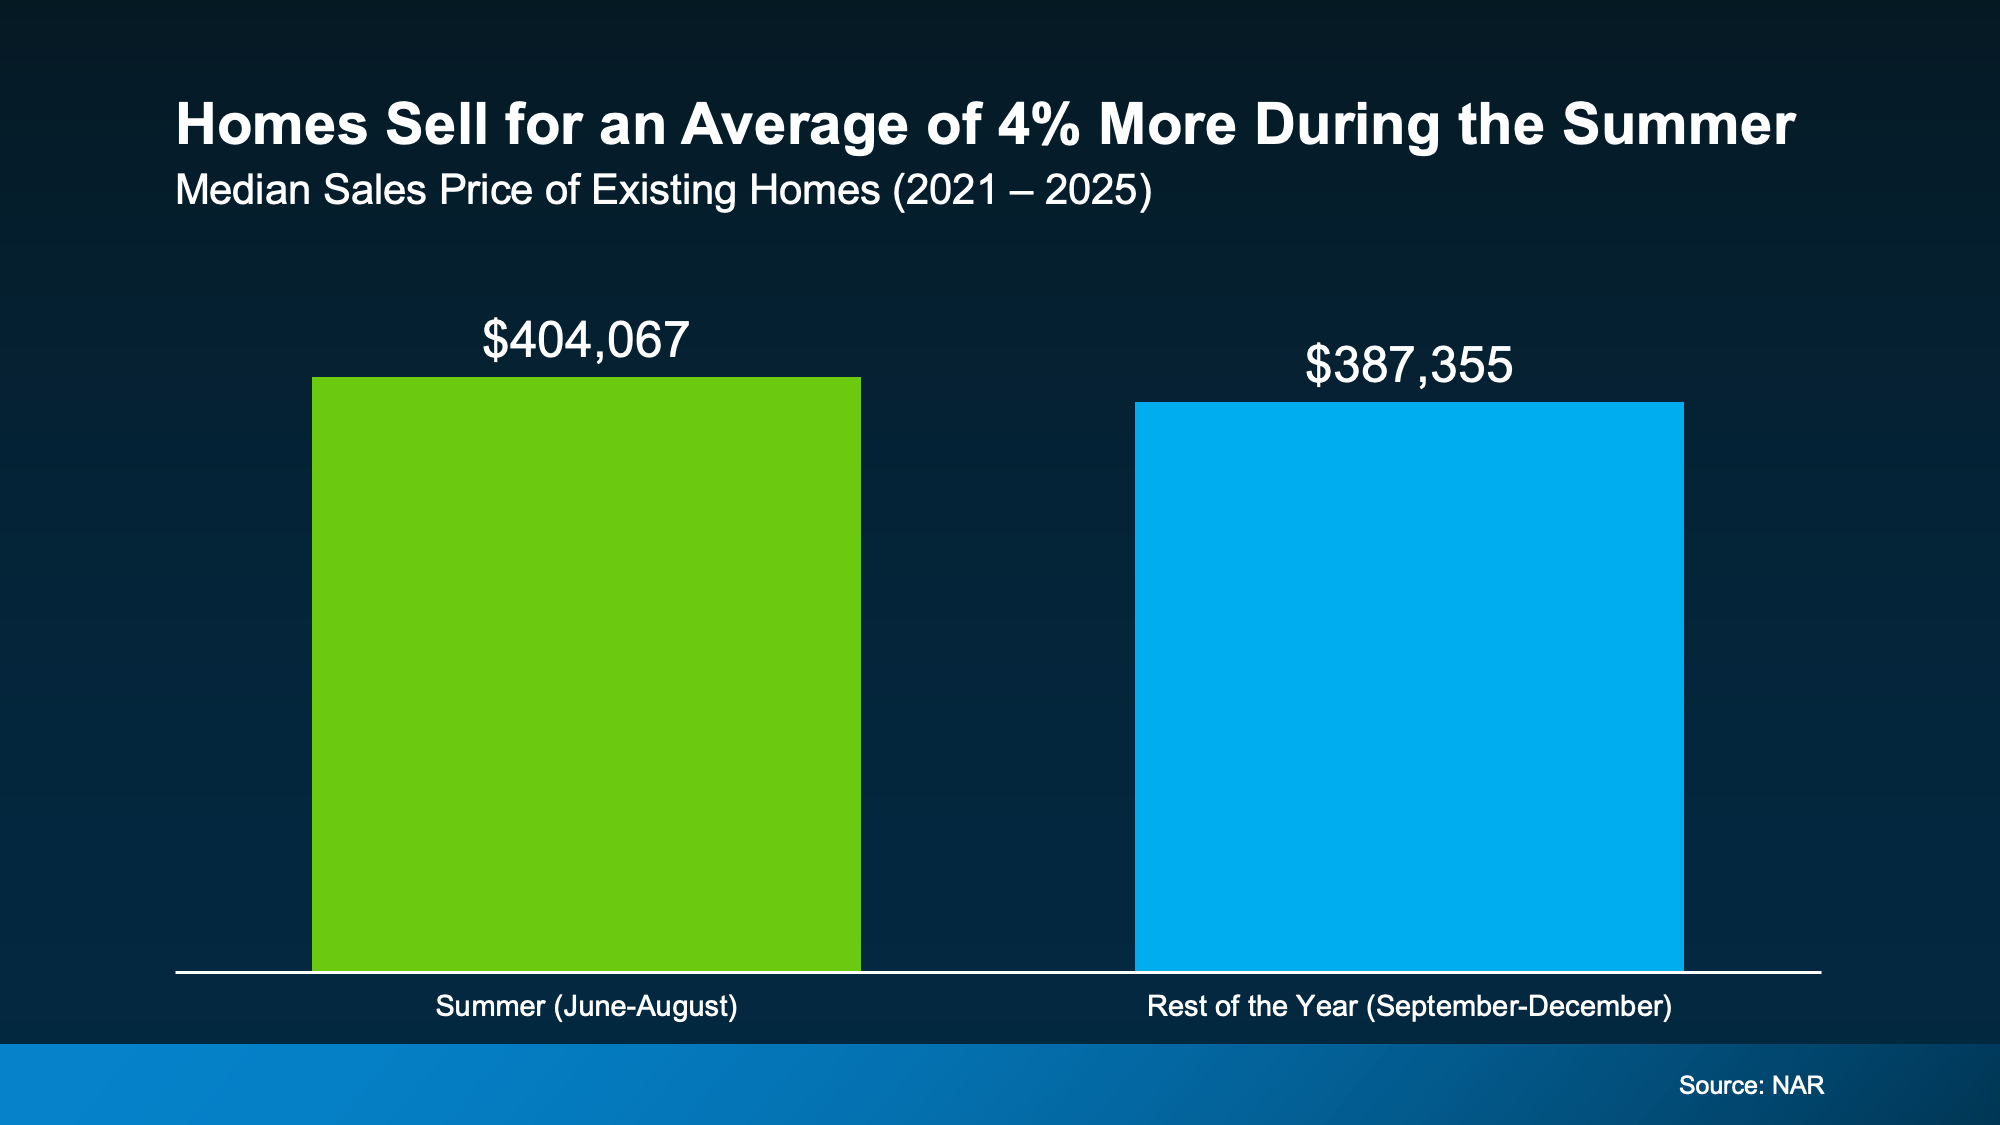
According to the National Association of Realtors (NAR), homes sold during a Summer month usually sell for about 4% more than homes sold during the typical month from September-December:

a graph of a sales report 

Why? Summer buyers are usually operating on a set timeframe. They’re trying to move before the next school year or when they have more PTO and warmer weather to tour houses. That urgency can translate into better offers.

Now, that doesn’t mean you should price your house 4% higher this Summer. That would actually be a mistake in today’s market.

It just means if you’re looking to get as much for your house as you reasonably can, a Summer move could be a smarter play than waiting until later this year. 

Because based on typical seasonality, you may get more for your house than you would if you waited until the Fall or Winter (when there are typically fewer buyers active).

And if you’re considering a move anyway, that’s worth factoring in.

Bottom Line

Could waiting until later this year work out? Sure. But it’s important to understand what you may gain by moving now too – that way you have the full picture before you decide.

If a 2026 move is on your radar, talk to an agent about what matters most to you. Depending on your priorities, Summer could be your moment.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Lower Asking Prices Are a Win for Today’s Buyers

Lower Asking Prices Are a Win for Today’s Buyers Simplifying The Market

If affordability has been the biggest thing standing between you and a home, there’s a little good news. 

Asking prices have started to come down.

The typical seller listed their house for a median of $429,500 in May. That’s 2.4% lower than a year ago, according to Realtor.com. On its own, that won’t transform what you can afford, but in today’s market every little bit helps and it signals a broader shift taking place.

Buyers Are Finally Catching a Break

Check out this data from Realtor.com and you can see this is the first May in years where buyers have caught any sort of break price-wise.

Each May from 2022-2025, things held pretty steady. But this year? You can see that more noticeable shift in your favor (see graph below):

a graph of sales in different colors

While the dip from $440,000 to $429,500 isn’t a big one, it gives you more breathing room. And that’s not a small thing when affordability has been this tough.

Now, lower asking prices don’t mean every home is suddenly within your range. But they do show buyers are gaining a little ground.

And in today’s market, a little ground can go a long way. 

What That Means for the Housing Market

And just in case this crossed your mind, this is good news for your move, not bad news for the market as a whole.

The subtle dip from last May to this one shows prices are easing, but they’re not dropping off a cliff. What this is actually a sign of is that the market’s rebalancing now that the number of homes for sale has grown.

Buyers have a bit more power again, and sellers know they can’t name just any price and expect their house to sell. They either meet the market where it is, or face a price cut later. And in general, sellers would rather avoid a price cut. As the New York Post explains:

“Rather than swinging for the fences with pandemic-era price tags, sellers are increasingly coming to terms with a new reality. The share of listings featuring price cuts actually fell to 17.5% in May, suggesting homeowners are doing their homework before putting up a “For Sale” sign instead of chasing unrealistic numbers and cutting later.“

This signals a broader change in the market.

Seller expectations have been skewed a little high since the pandemic buying frenzy – you’ve probably felt that firsthand. But now, things are starting to normalize. It could mean less back-and-forth to land on a fair number. And homes should be priced a bit more realistically from the start.

Bottom Line

If affordability has been your top concern, the recent dip in prices is an opening. Connect with a local real estate agent to see what that looks like in your area.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Is Late May the Best Time To List Your House?

Is Late May the Best Time To List Your House? Simplifying The Market

You may have heard April 12-18 was the “best week” to list your house. That’s based on a report from Realtor.com. But now that it’s passed, you may be wondering if you missed your moment.

Here’s the good news – you didn’t. 

Because the reality is, there isn’t just one perfect week to sell your house this Spring. There’s a window. And right now, you’re still in it.

Your Window To Sell Is Still Wide Open

Here’s why. Different organizations run studies like this every year. And they don’t always land on the exact same week. That’s okay. It’s because they’re using different research methods and even different definitions of what “best” means.

But the fact that the results vary points to a larger trend. While there may be sweet spots, the entire Spring season gives sellers an opportunity to get some of the best conditions (and best sales prices) of the year.

And it’s definitely not too late to jump in.

Why Listing in Late May Is the Perfect Play

According to Zillow, the best time to list your house this year is the last 2 weeks of May. And that’s approaching fast.

Based on their analysis, this is the ideal time to do it if you want to make top dollar. Because, in this 2-week window, homes sell for more. Sometimes, quite a bit more.

Depending on where you are and the price point in your area, some homeowners may even net tens of thousands of dollars extra in this sweet spot. As Zillow explains:

“Why late spring? Buyer demand typically peaks before Memorial Day. Families want to move during the summer and settle in before the new school year. More buyers shopping at once can spark competition and lift prices.”

And they’re not the only ones saying listing in May could be the key to selling for more. ATTOM Data analyzed almost 52 million home sales over the past 10 years and found sellers in May are achieving some of the highest returns.

That means the ideal window this year is very much still open.

What This Means for You 

If your goal is to sell for the strongest possible price, this is where timing and strategy come together. And you want to be sure you’re ready to make the most of it.

So, what should you be doing right now?

When prepping for a fast-moving window like this, you don’t want to waste time or money on the wrong prep work. And your agent is your go-to to make sure you’re focusing on the right things.

They’ll be able to tell you if the “best week” is slightly different in your market. And what quick repairs or updates can help you get a higher price, without taking a ton of time or effort.

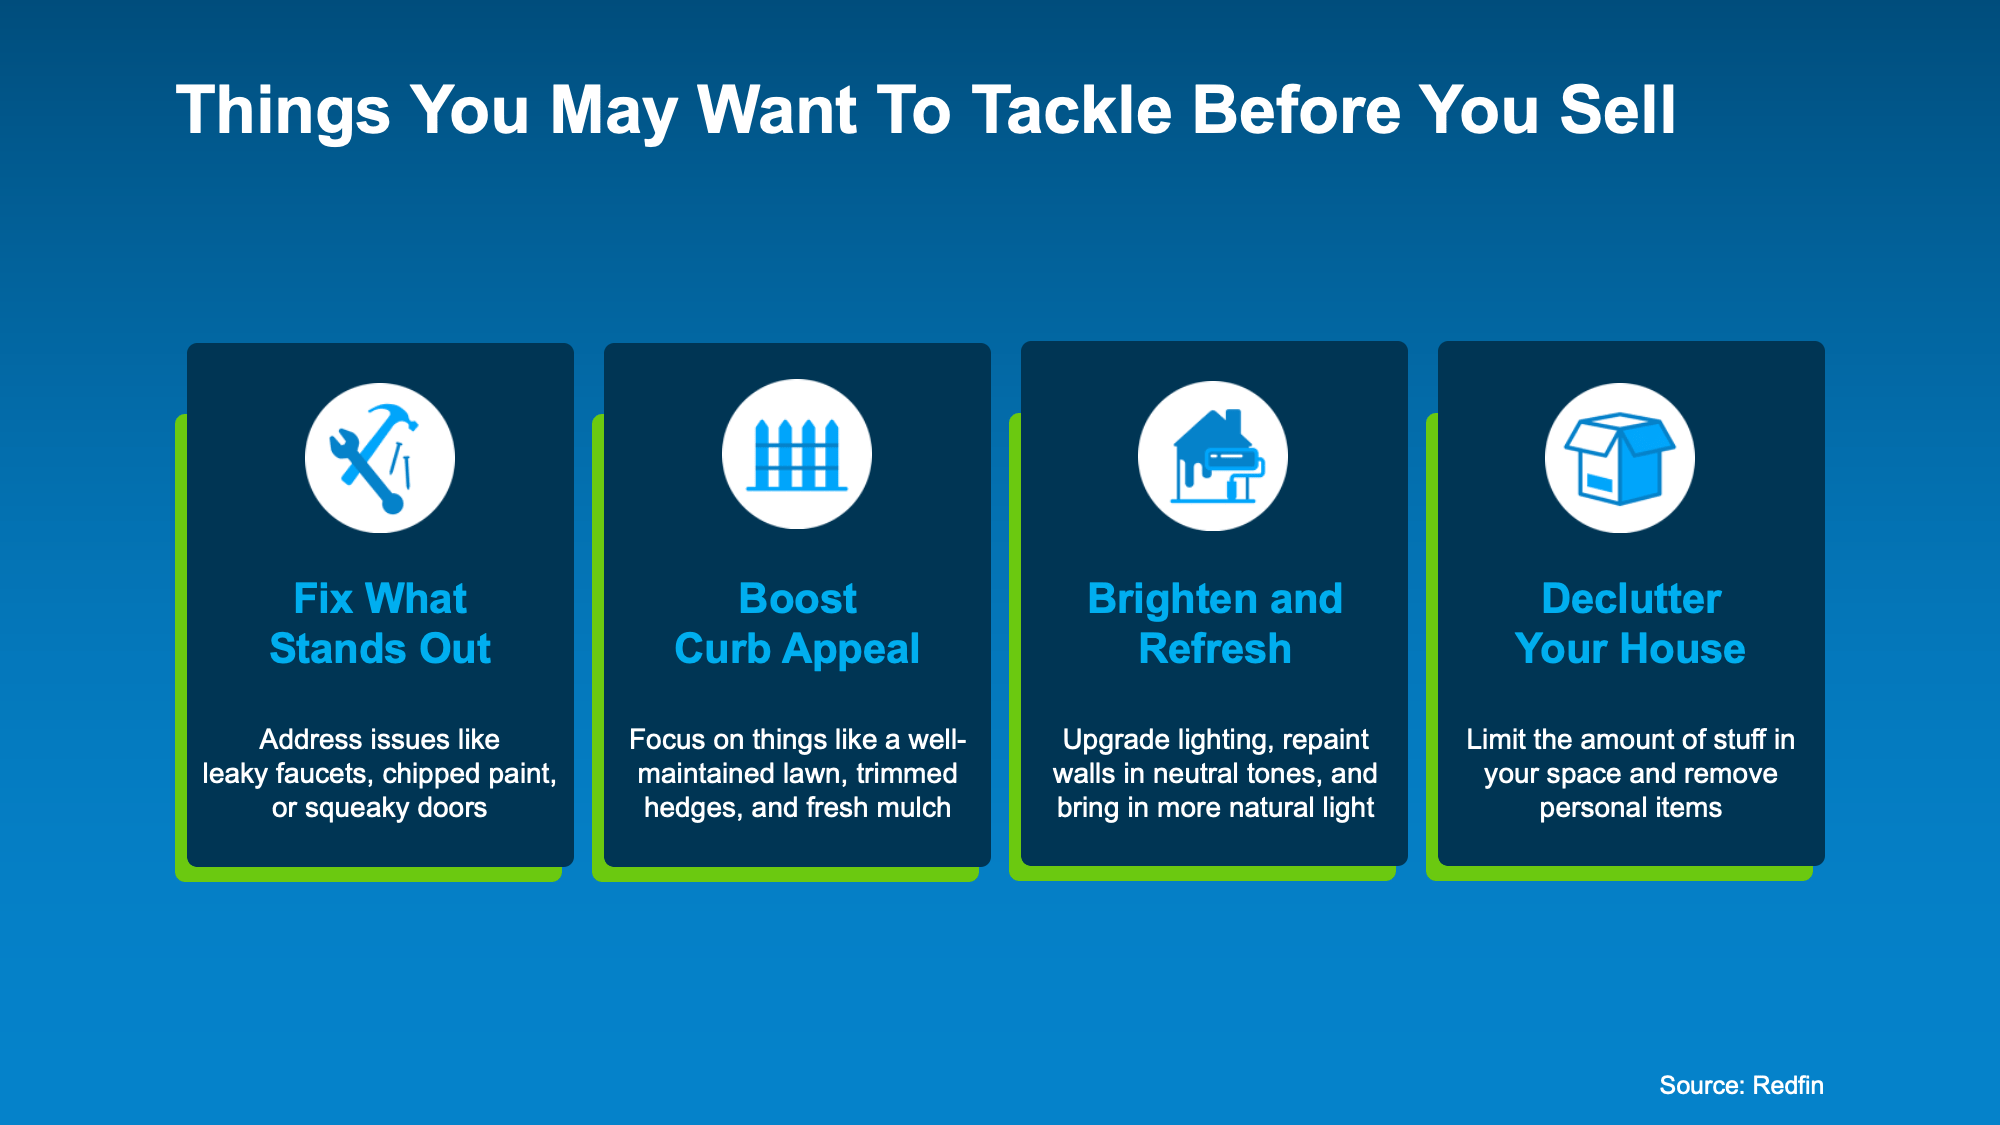
Here’s a quick example of things an agent may recommend based on information from Redfin:

At the end of the day, when your prep time’s short, doing the right things matters more than doing more things.

Bottom Line

Zillow says the best time to list your house is just around the corner. Are you ready to make the most of it?

If you want to take advantage of this Spring sweet spot and get top dollar for your house, talk to a local agent about what you need to do now to get ready to hit the market.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Stay or Sell? How To Make the Right Call as You Age

Stay or Sell? How To Make the Right Call as You Age Simplifying The Market

At some point, as you start thinking about the years ahead, this question tends to come up:

“Could I stay here long-term… or would it make more sense to move?”

It’s not always urgent. It often shows up in small moments, like going up and down the stairs, keeping up with the maintenance, or just thinking about what the next chapter of your life might look like in this home.

And for most people, the answer is simple. They want to stay.

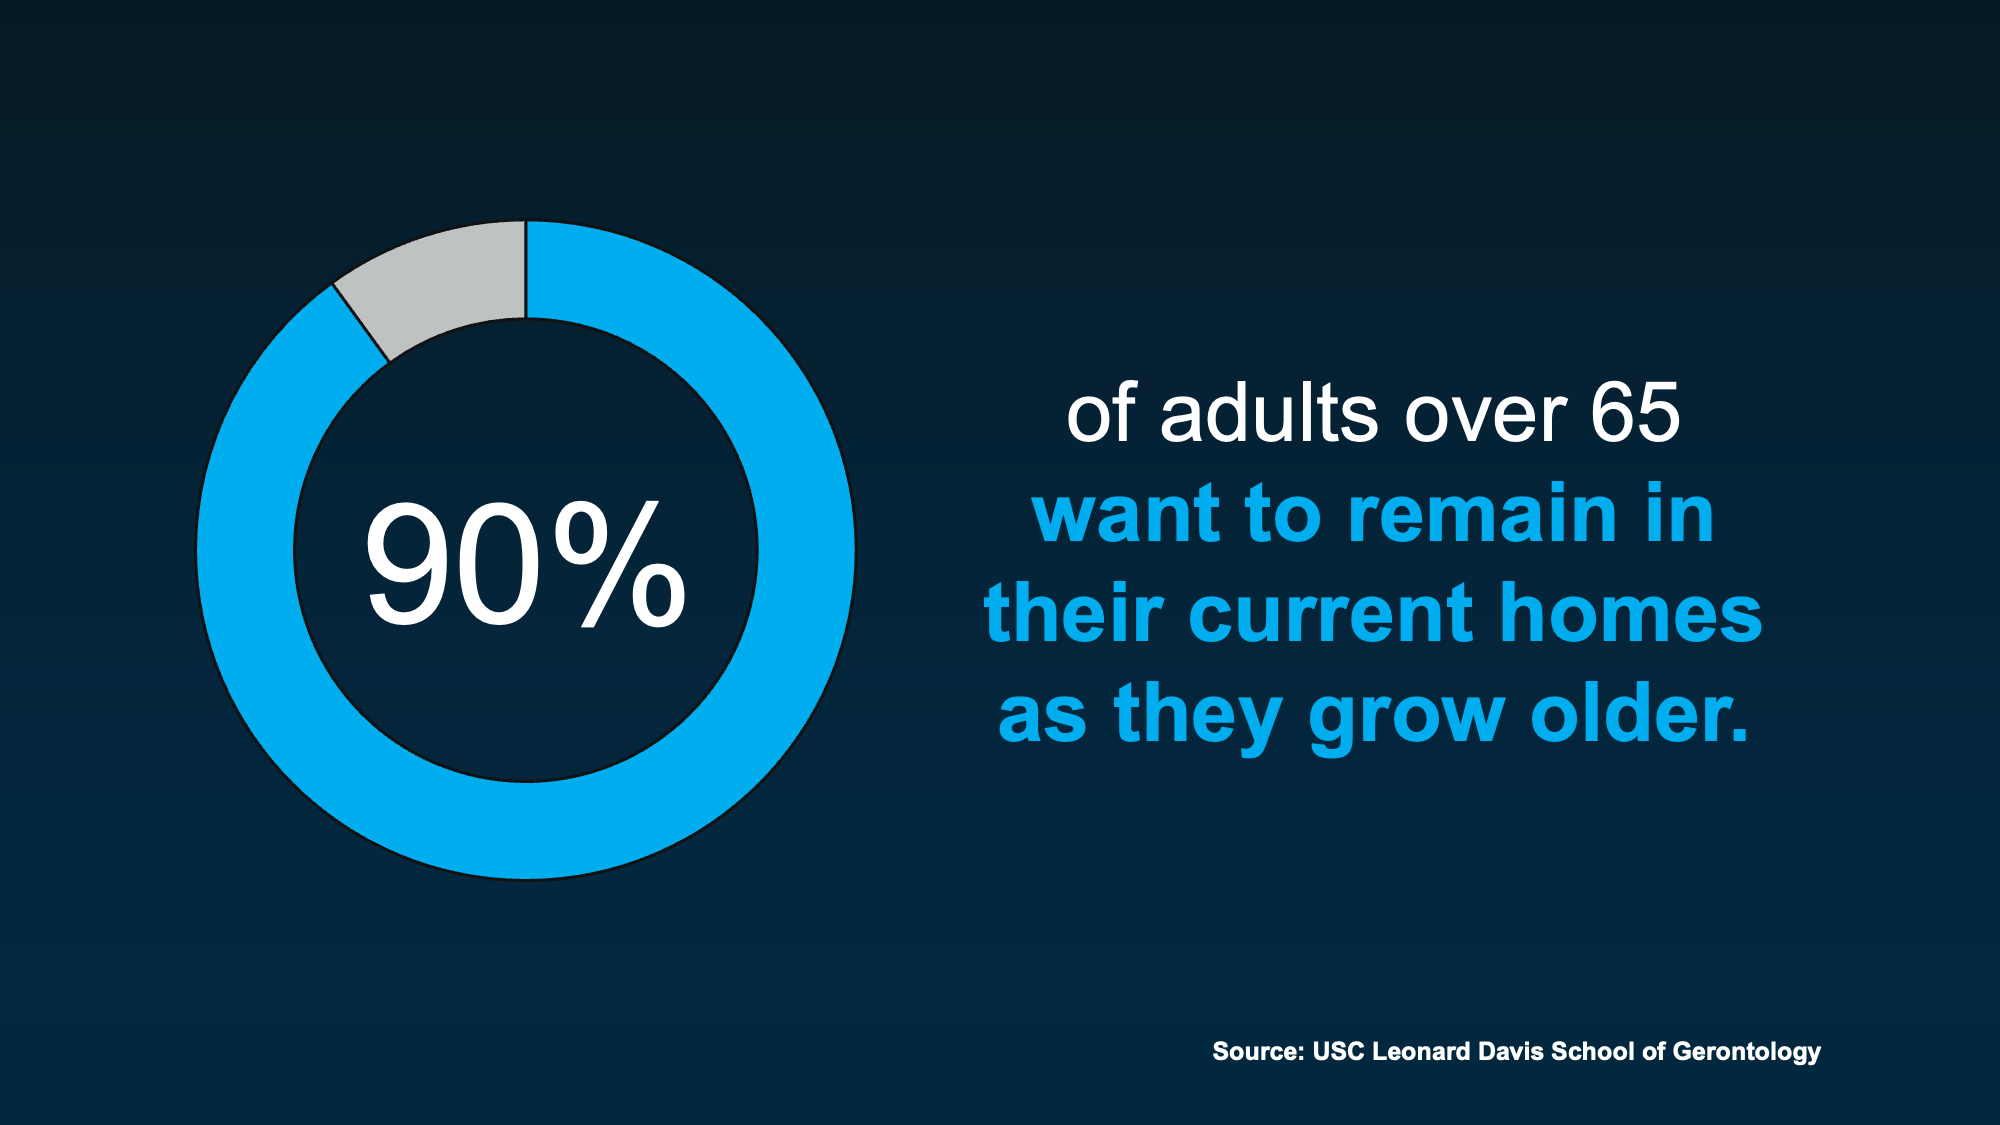
The USC Leonard Davis School of Gerontology found about 90% of adults over 65 prefer to stay in their homes as they get older (see below):

a blue circle with white textBut even if staying feels like the right answer, it’s still worth thinking ahead about what that might actually look like. That’s where the right agent can really help.

What You Need To Plan for If You’re Staying in Your Home

Aging in place is definitely possible. But it’s better if you have a plan. And here’s why. The home that once worked perfectly may need to change with you over the years. And it’s easier if you can anticipate those expenses.

  • Sometimes that means small updates: like adding grab bars in the shower.
  • Other times, you’ll have to make bigger decisions: like reworking layouts or moving key spaces to the first floor.

Some of those changes are going to be simple. Others can be a meaningful investment. And that’s why thinking about it early matters. Not because you need to decide anything right now, but because it gives you time.

  • Time to understand what your home may need.
  • Time to explore your options.
  • Time to find the right contractors.
  • Time to space out the expense of the upgrades.

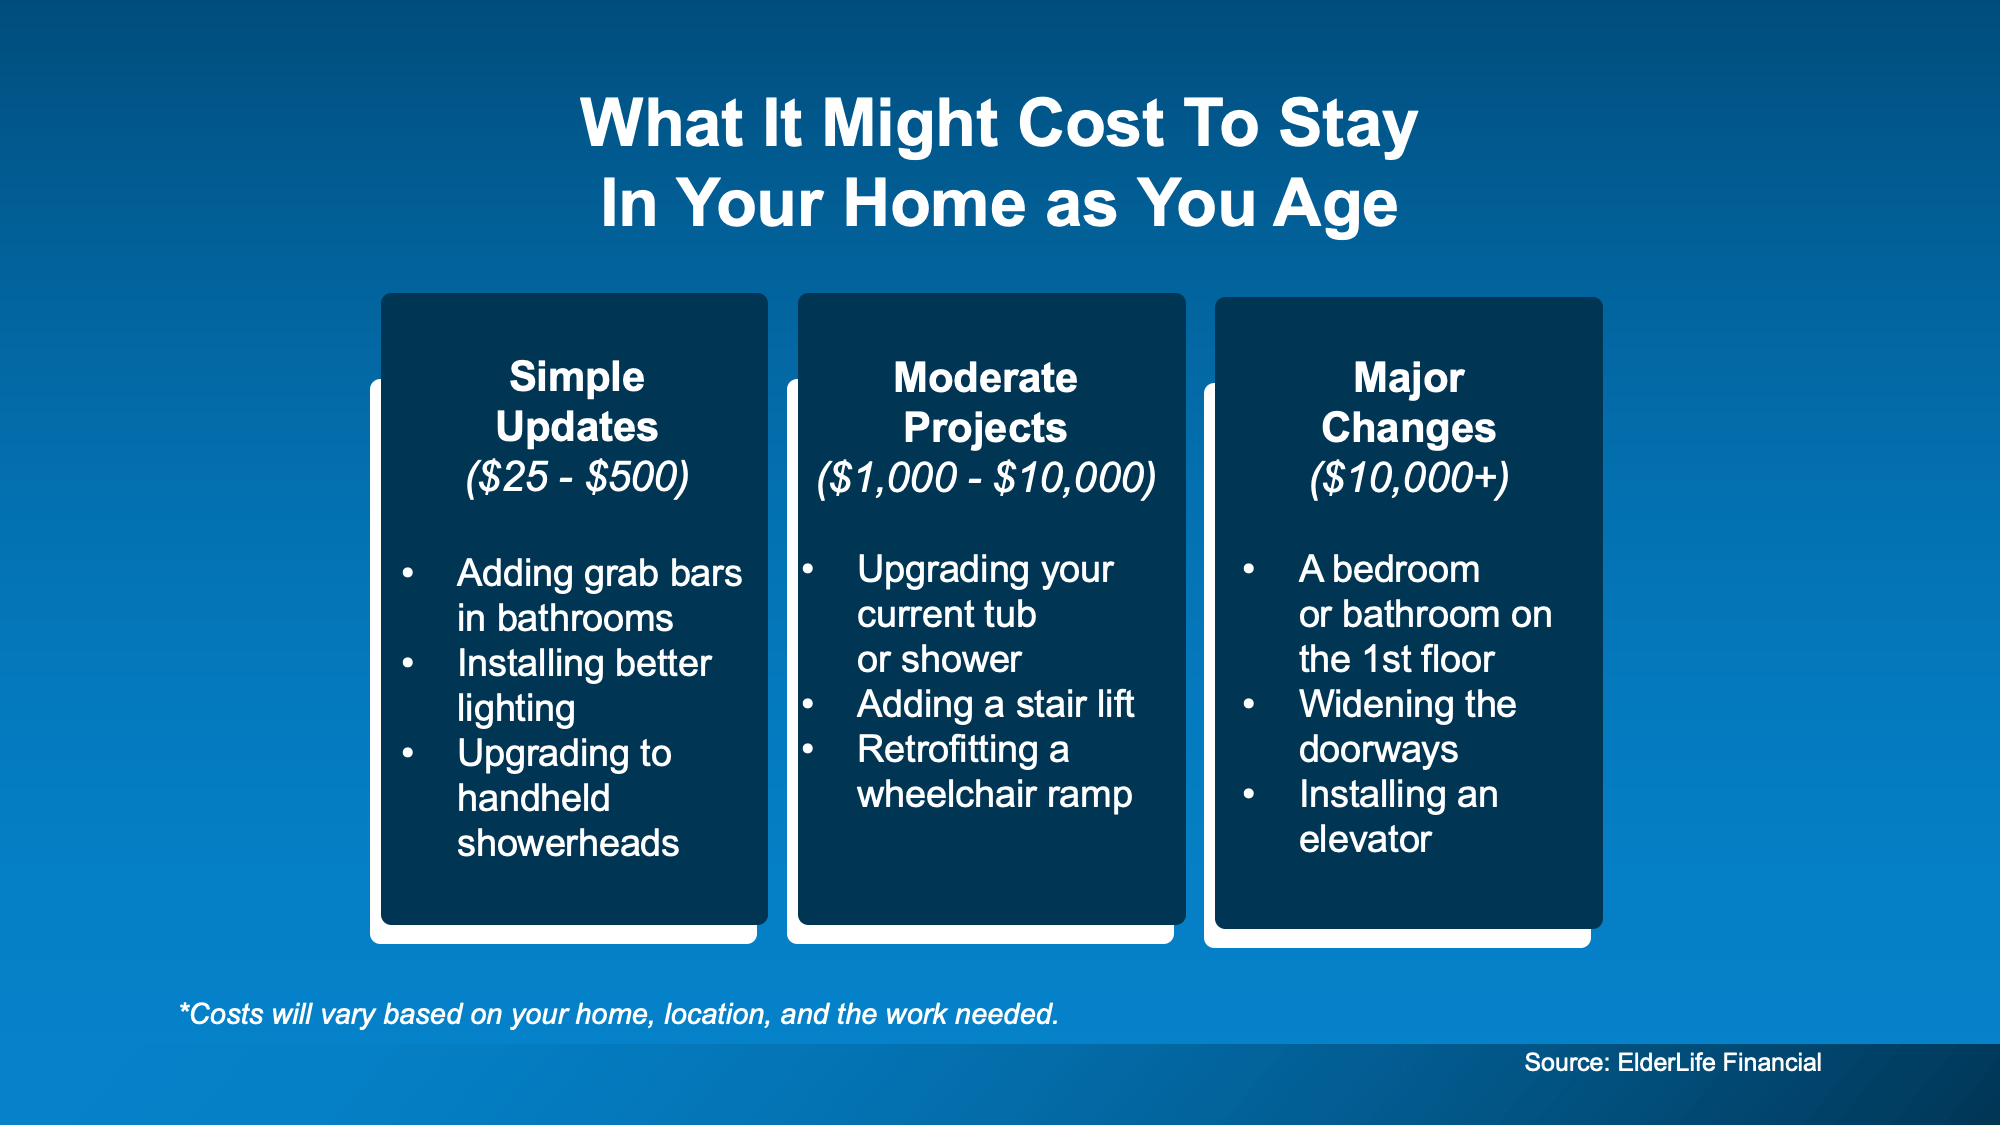
According to ElderLife Financial, here’s a rough baseline of what it could cost depending on what needs to be done (see below):

a blue and white rectangular signAnd don’t worry. If your heart is really set on staying, but the costs feel like a concern, it helps to know you have options. Depending on your situation, there may be financial assistance programs available, along with tools like home warranties to help manage unexpected costs.

Just remember, if you’re thinking about making updates, it’s always worth having a quick conversation before you start. A real estate agent can help you understand which changes tend to make sense for your situation and how they may impact your home’s value based on your local market.

When Moving Might Make More Sense

But staying isn’t always the best fit for every situation. According to Pegasus Senior Living:

“While most seniors hope to age in place, practical considerations sometimes make selling a home the wiser choice.”

Sometimes, it comes down to a simple shift: when the home that once made life easier, starts to make it harder.

That might look like:

  • Maintenance or yardwork that’s starting to feel overwhelming
  • Stairs or layouts that are getting harder to manage day-to-day
  • Or needing more support or care or being too far from loved ones

And sometimes, it’s not about necessity at all. It’s about lifestyle. Some homeowners just don’t want to live through major renovations. Others are ready to simplify, downsize, or move somewhere that better fits this next chapter, whether that’s a smaller home, a 55+ community, or a place closer to family. 

For them, moving simply means making daily life easier.

Bottom Line

There’s no one-size-fits-all answer here.

Some people stay and make updates. Others move to simplify things. Either can be the right choice. The goal isn’t to pick one today. It’s to understand your options early, so when the time comes, you feel confident instead of rushed.

And if you ever want a sounding board to think through what the future could look like for you, a local real estate agent is there to help.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Think You Have To Put 20% Down? Most First-Time Homebuyers Don’t.

Think You Have To Put 20% Down? Most First-Time Homebuyers Don’t. Simplifying The Market

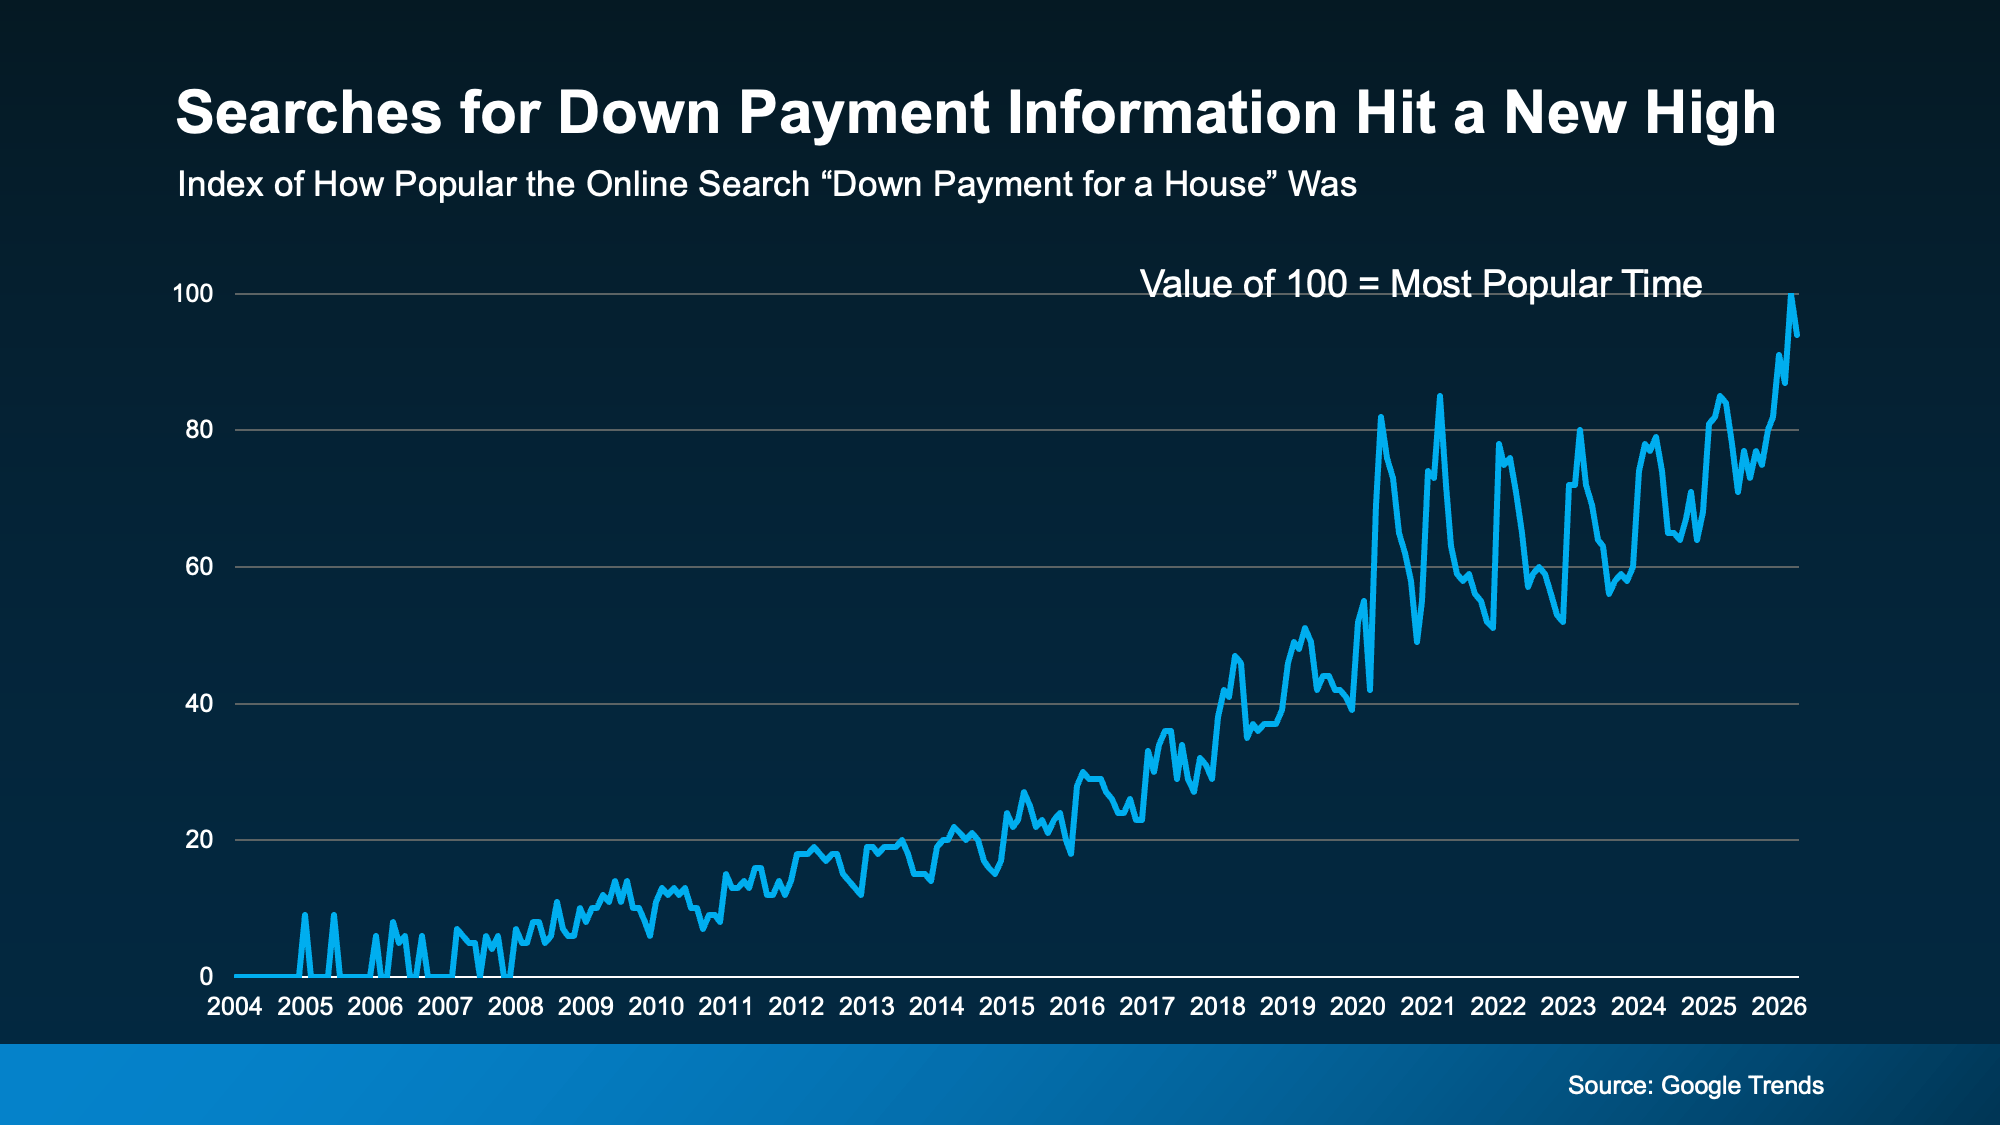
According to Google Trends, online searches for down payment information recently hit an all-time high. And that’s a clear sign more buyers are trying to figure out what they really need to save before making a move (see graph below):

a graph of a line graphIf you’re wondering the same thing, you can always turn to the internet for answers. But a lot of the time, it’s better to ask a local expert. Because here’s what a pro would tell you.

The 20% Down Payment Myth

The idea that you need 20% down to buy a home is one of the biggest misconceptions around the homebuying process. And the data debunks the myth.

While there are benefits to putting that much money down, most first-time buyers put down far less.

Here’s why. Unless it’s stated by your lender, you typically don’t have to have a 20% down payment. There are even some loan options designed to help you get into a home with a much smaller upfront cost. As the Mortgage Reports explains:

“The amount you need to put down will depend on a variety of factors, including the loan type and your financial goals. If you don’t have a large down payment saved up, don’t worry—there are plenty of options available, and you don’t need to put down the traditional 20% . . . many homebuyers are able to secure a home with as little as 3% or even no down payment at all . . .”

For example, FHA loans allow down payments as low as 3.5%, while VA and USDA loans offer zero down payment options for qualified applicants, like Veterans.

And those options are just one reason so many first-time buyers are able to buy without a 20% down payment.

What Buyers Are Actually Putting Down

So, if buyers aren’t doing 20%, how much do they actually put down?

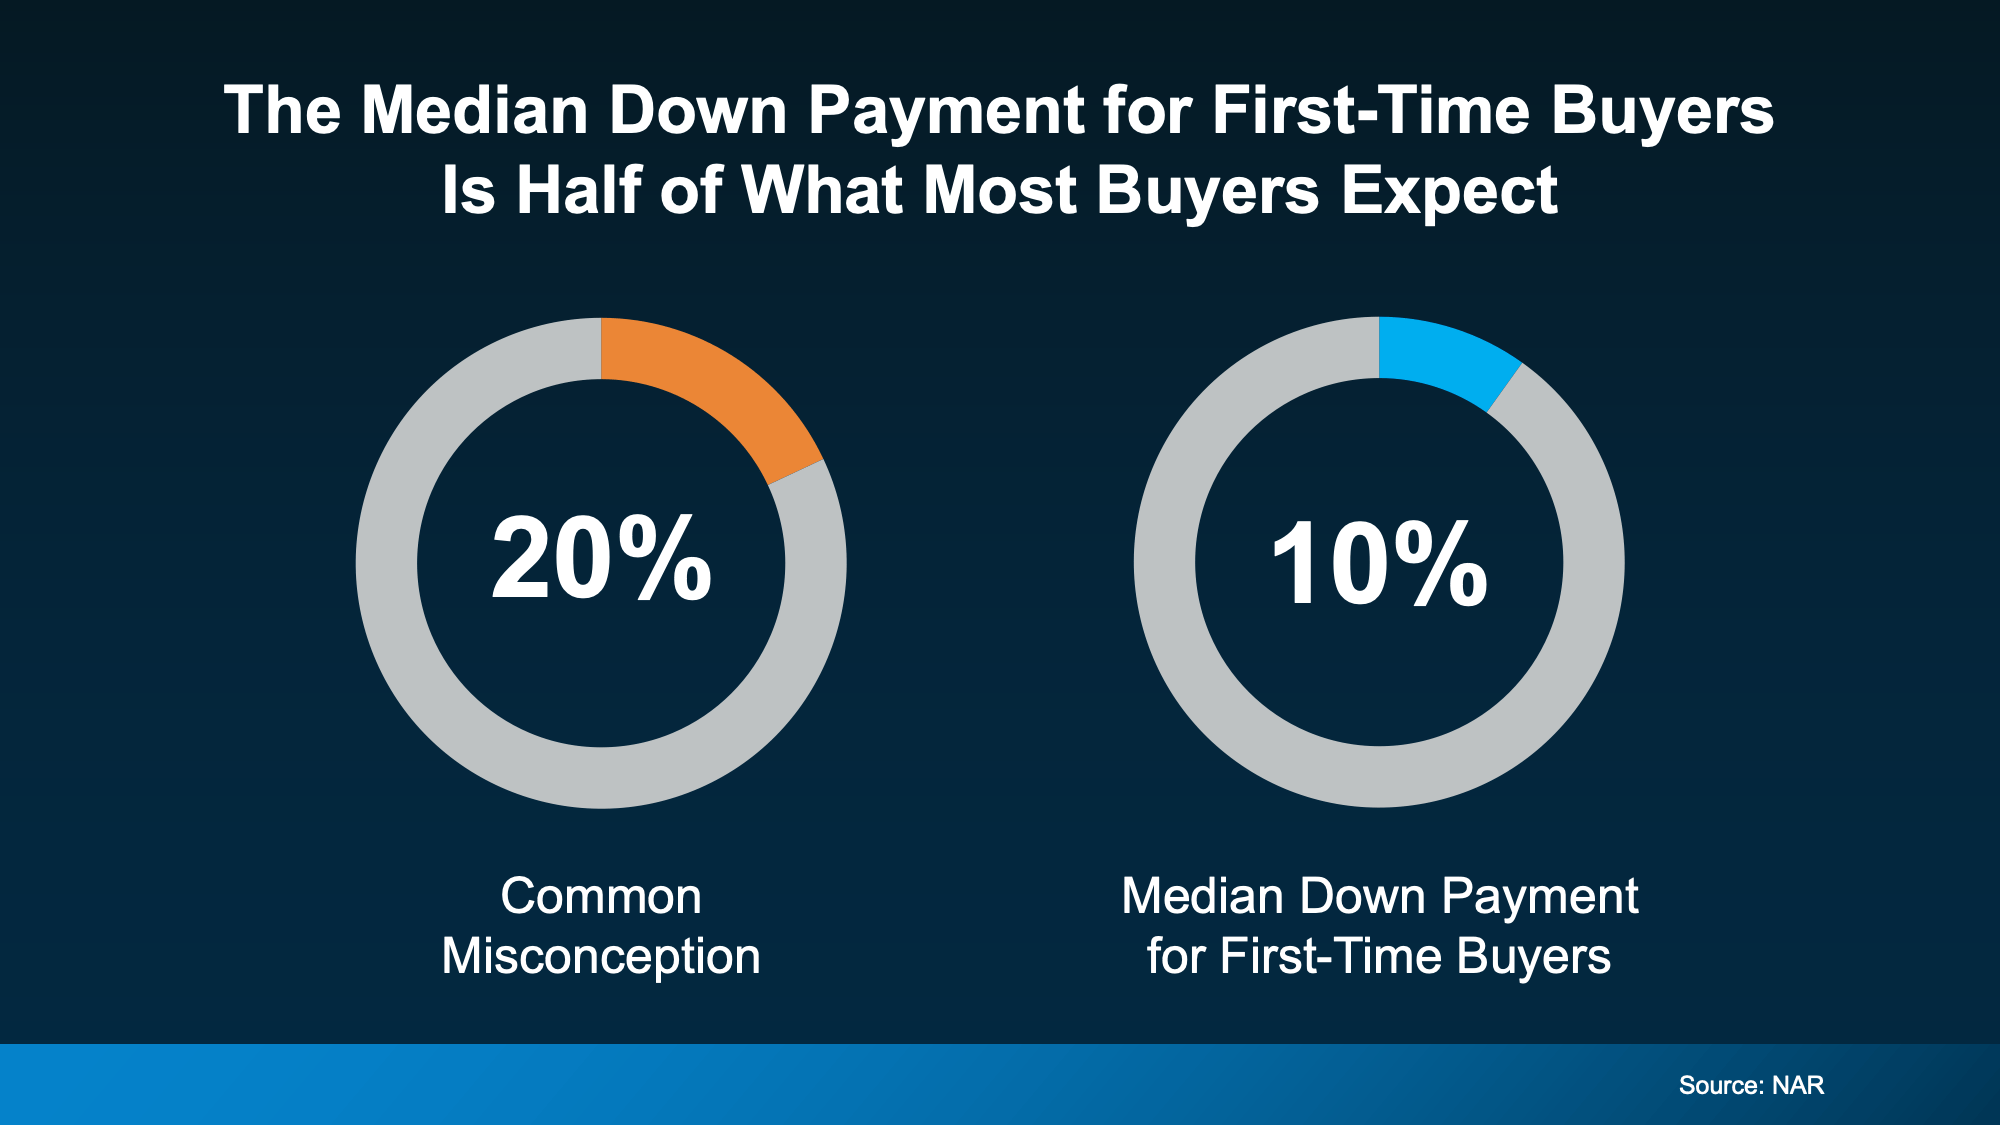
According to the National Association of Realtors (NAR), the median down payment for first-time homebuyers is only 10%. That’s half of what you probably expected.

a diagram of a pie chartThat means if you’re aiming to save 20% because you think you have to, you may be setting a timeline that’s longer than necessary.  

And here’s some more good news. It’s not only that you may be able to buy with less money down than you thought, but there are also options to help you get to your down payment goal even faster.

Why You Should Look into Down Payment Assistance Programs

There are a lot of programs designed to help you save for a down payment – and they can make a big difference in how fast you hit your savings target. Unfortunately, buyers don’t realize how many there are, or that they may qualify for help.

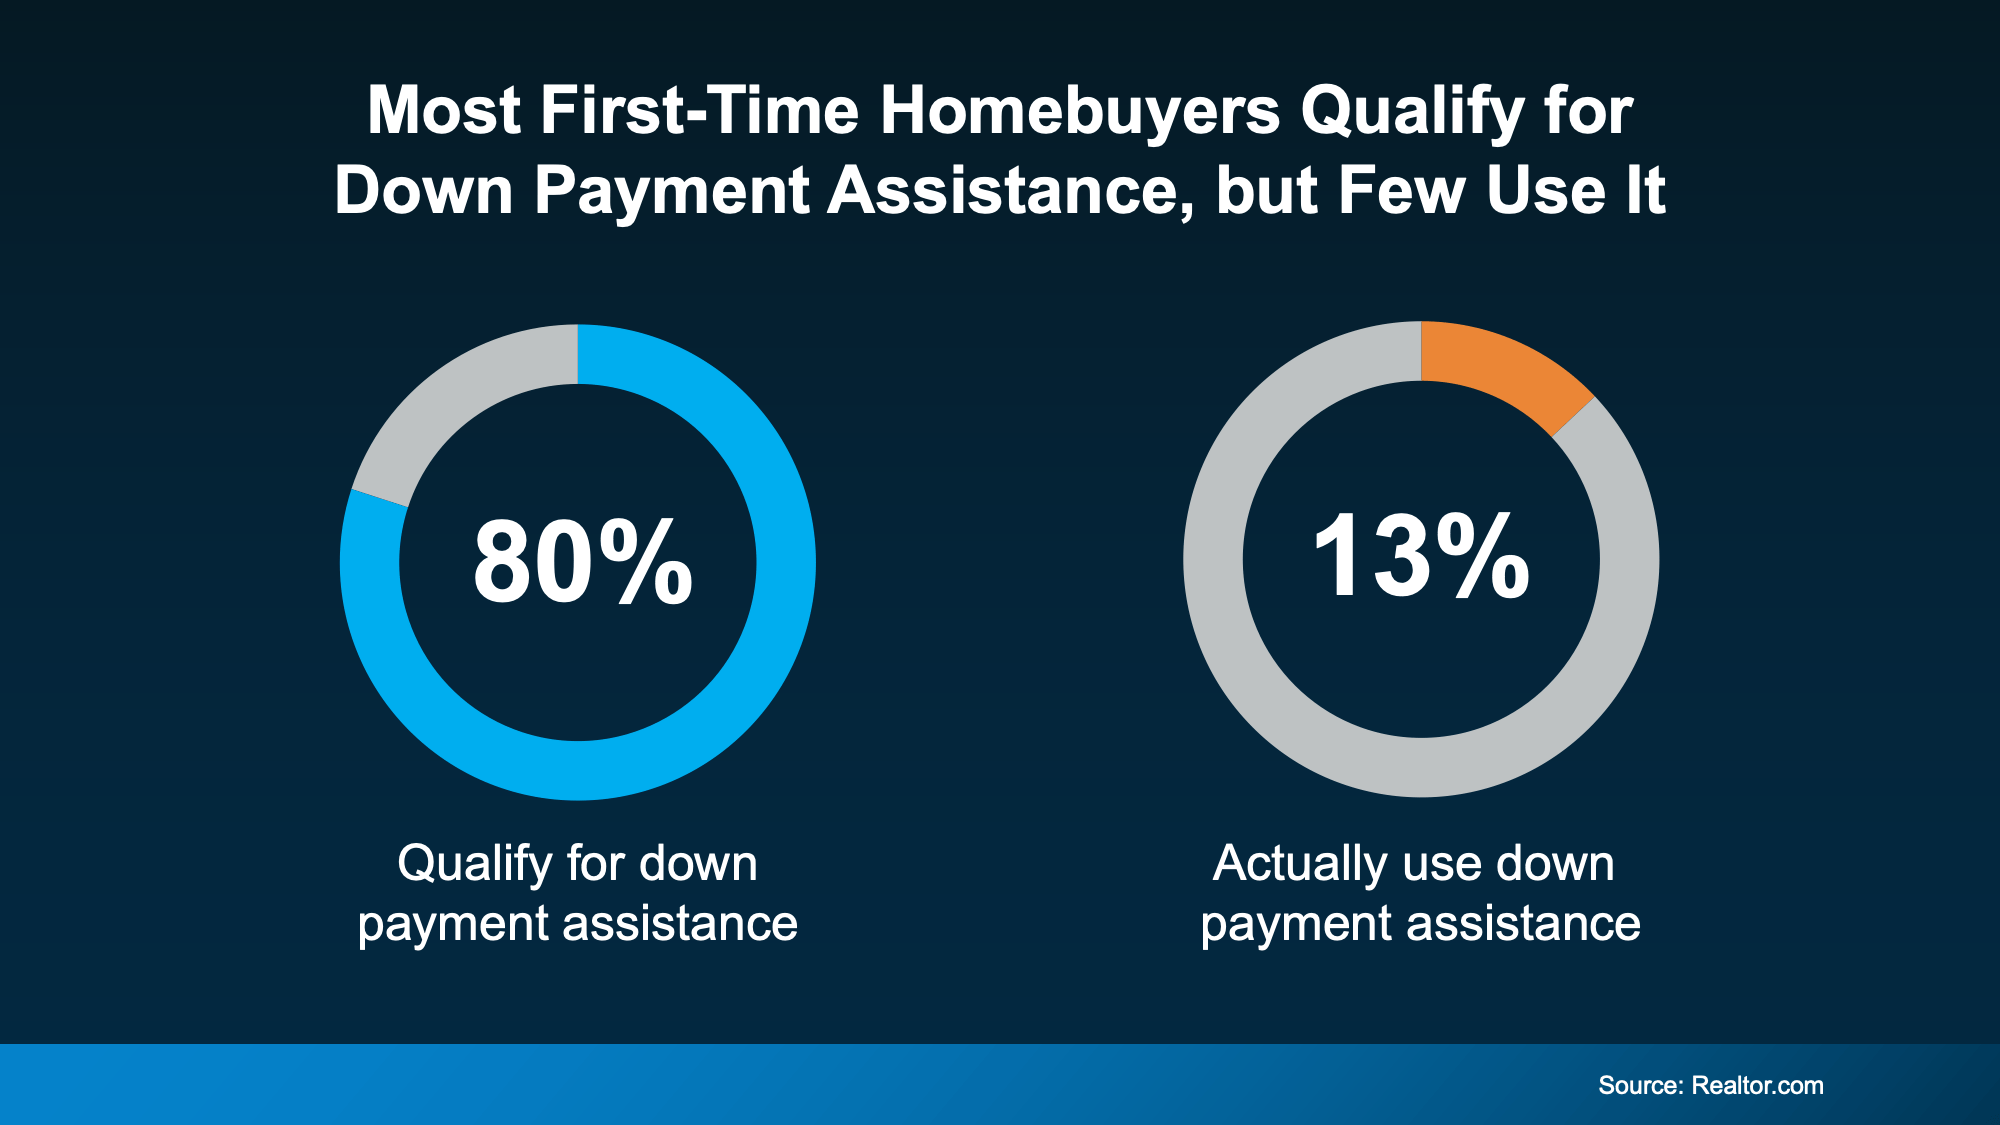
Research from Realtor.com shows almost 80% of first-time homebuyers qualify for down payment assistance (DPA), but only 13% actually use it (see chart below): 

a blue and orange pie chartAnd that’s another big miss holding would-be buyers like you back.

In the U.S., there are over 2,600 homeownership programs available, many offering significant financial support. As Down Payment Resource shares:

“With an average benefit of $18,000, down payment assistance (DPA) remains one of the most essential tools for addressing the nation’s affordability challenges. Programs continue to expand in scope, serving a broader range of incomes, property types and borrower needs, including first-generation, military and repeat buyers.”

Imagine how much further your savings could go with an extra $18,000 you can use to buy. In some cases, you may even be able to stack multiple programs, giving what you’ve saved an even bigger boost.

Bottom Line

The simple truth is: most first-time buyers don’t put 20% down. And if you’ve been waiting to buy until you have that saved, you may be setting a timeline that’s longer than necessary.

To find out what you really need to save and if you qualify for any help, connect with a trusted lender who can walk you through your options. You may be able to buy sooner than you thought.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida