Available 7 Days/Week       MON - FRI  8am - 7pm       SAT - SUN  10am – 6pm
Call us (407) 955-4575
Apply Now

Category: For Sellers

Auto Added by WPeMatico

Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know.
Should You Pay for Your Buyer’s Closing Costs? What Sellers Need To Know. Simplifying The Market

A few years ago, sellers could get away with saying “no” to just about everything.

No repairs.

No concessions.

No negotiation.

If buyers wanted the house, they pretty much had to take it on the seller’s terms. But now that inventory’s grown, negotiations are becoming a normal part of the process again.

That’s why one of the most important things sellers need to understand right now is this:

The goal isn’t to “win” every negotiation.

Sometimes, it’s worth meeting buyers where they are to get a deal done, fast. One example? Helping with a buyer’s closing costs.

Let’s break that down, so you know what to expect if it comes up in your sale.

What Are Buyer Closing Costs?

Closing costs are the extra expenses buyers pay on top of their down payment when they purchase a home. Freddie Mac gives some examples:

  • Loan origination fees

  • Appraisal and inspection costs

  • Title and attorney fees

  • Survey fees and more

Typically, buyer closing costs range from about 2% to 5% of the home’s purchase price. So, on the typical $400,000 home, that could mean anywhere from $8,000 to $20,000 out of pocket.

And in today’s affordability-challenged market, that upfront cash can be a major hurdle for some buyers – even if they can comfortably afford the monthly mortgage payment itself. 

That’s why more people are asking sellers for help.

And More Sellers Are Saying “Yes”

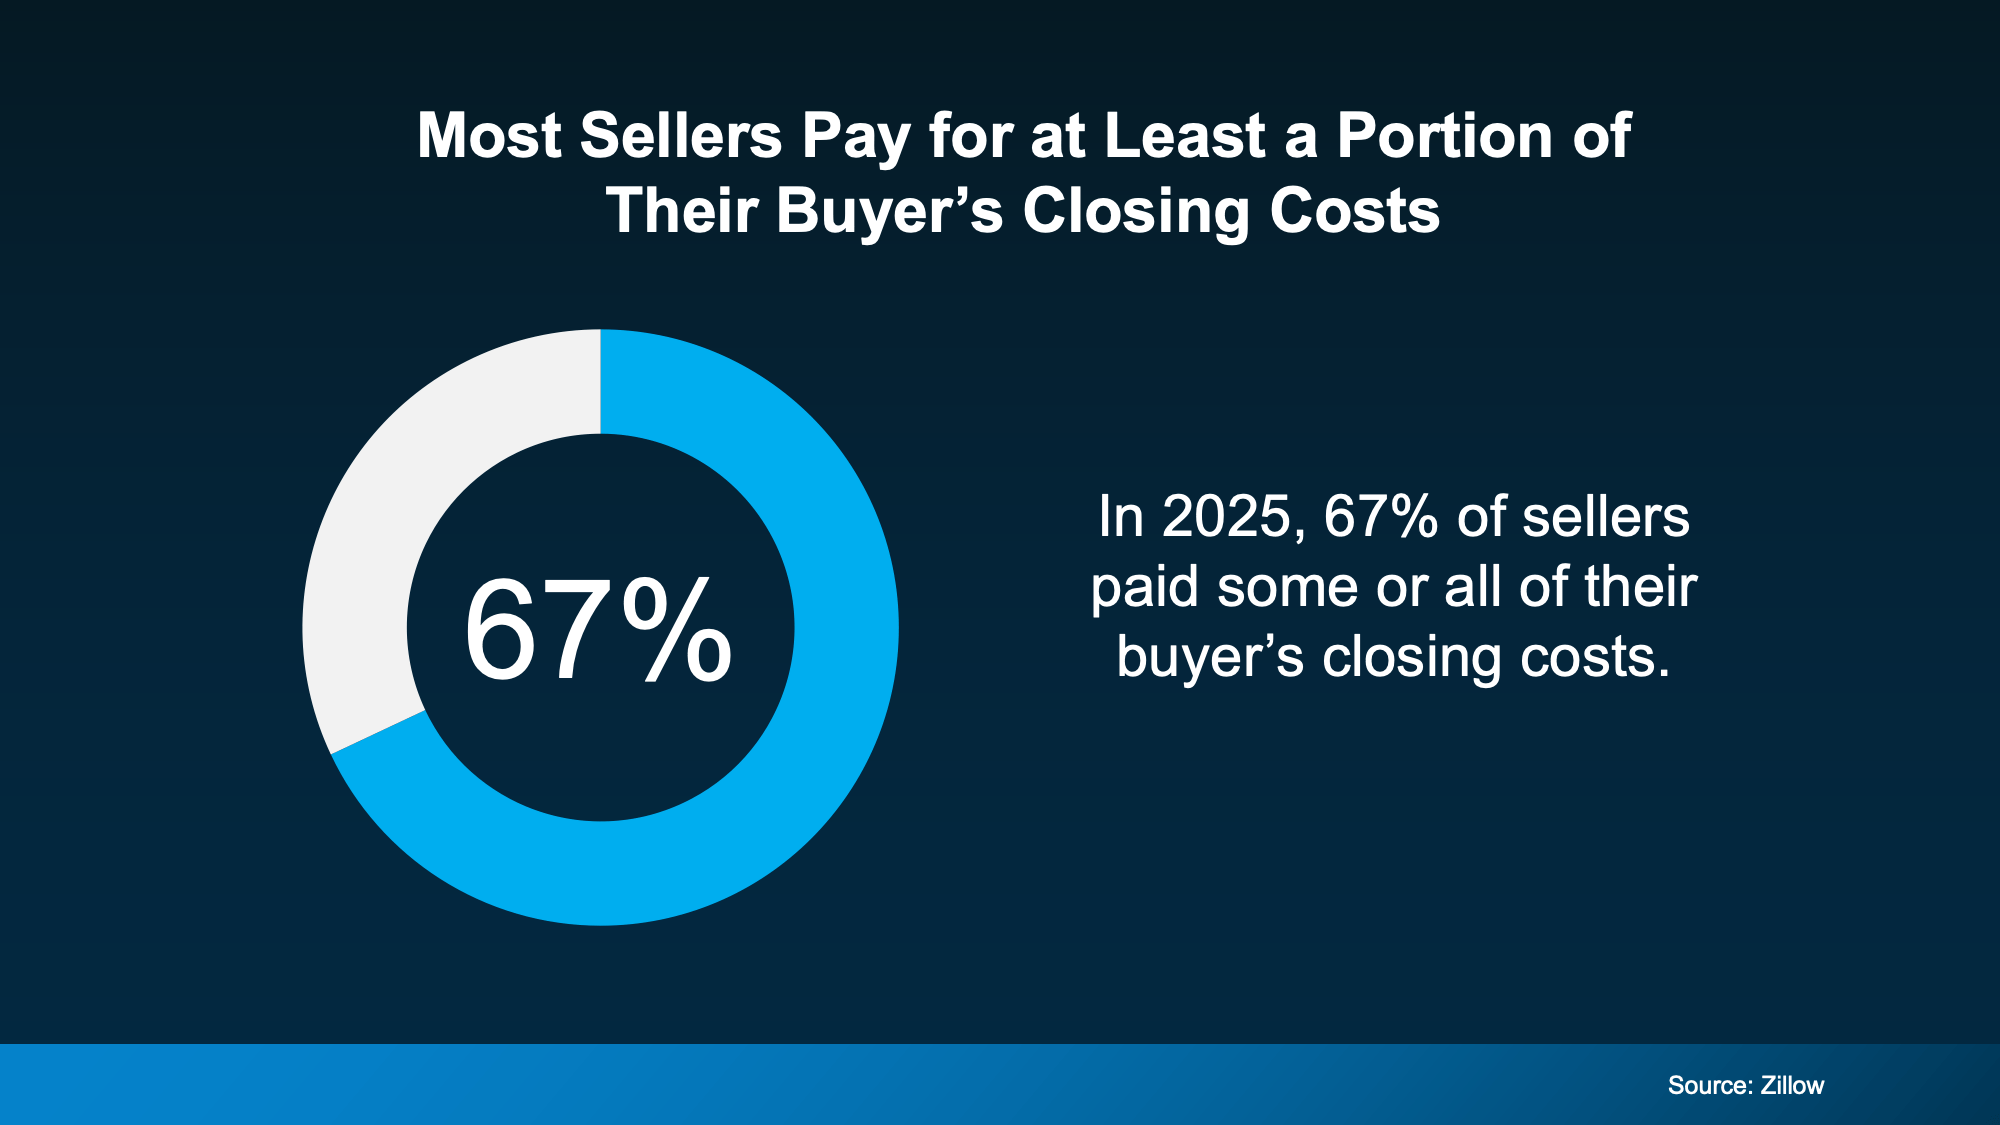
According to the latest data from Zillow, 67% of sellers reported paying some or all of the buyer’s closing costs in 2025 (see chart below):
a blue circle with white text

Now, that doesn’t mean every seller is doing it. And it definitely doesn’t mean every seller should. But it does show how common concessions have become as the market has shifted. And that’s important for you to know.

When Paying Closing Costs May Make Sense

This is where many sellers get stuck. They hear “help with closing costs” and immediately think: “Why should I pay for their expenses?”

But that’s not always the right way to look at it. You’ve got to consider who has the leverage in today’s market.

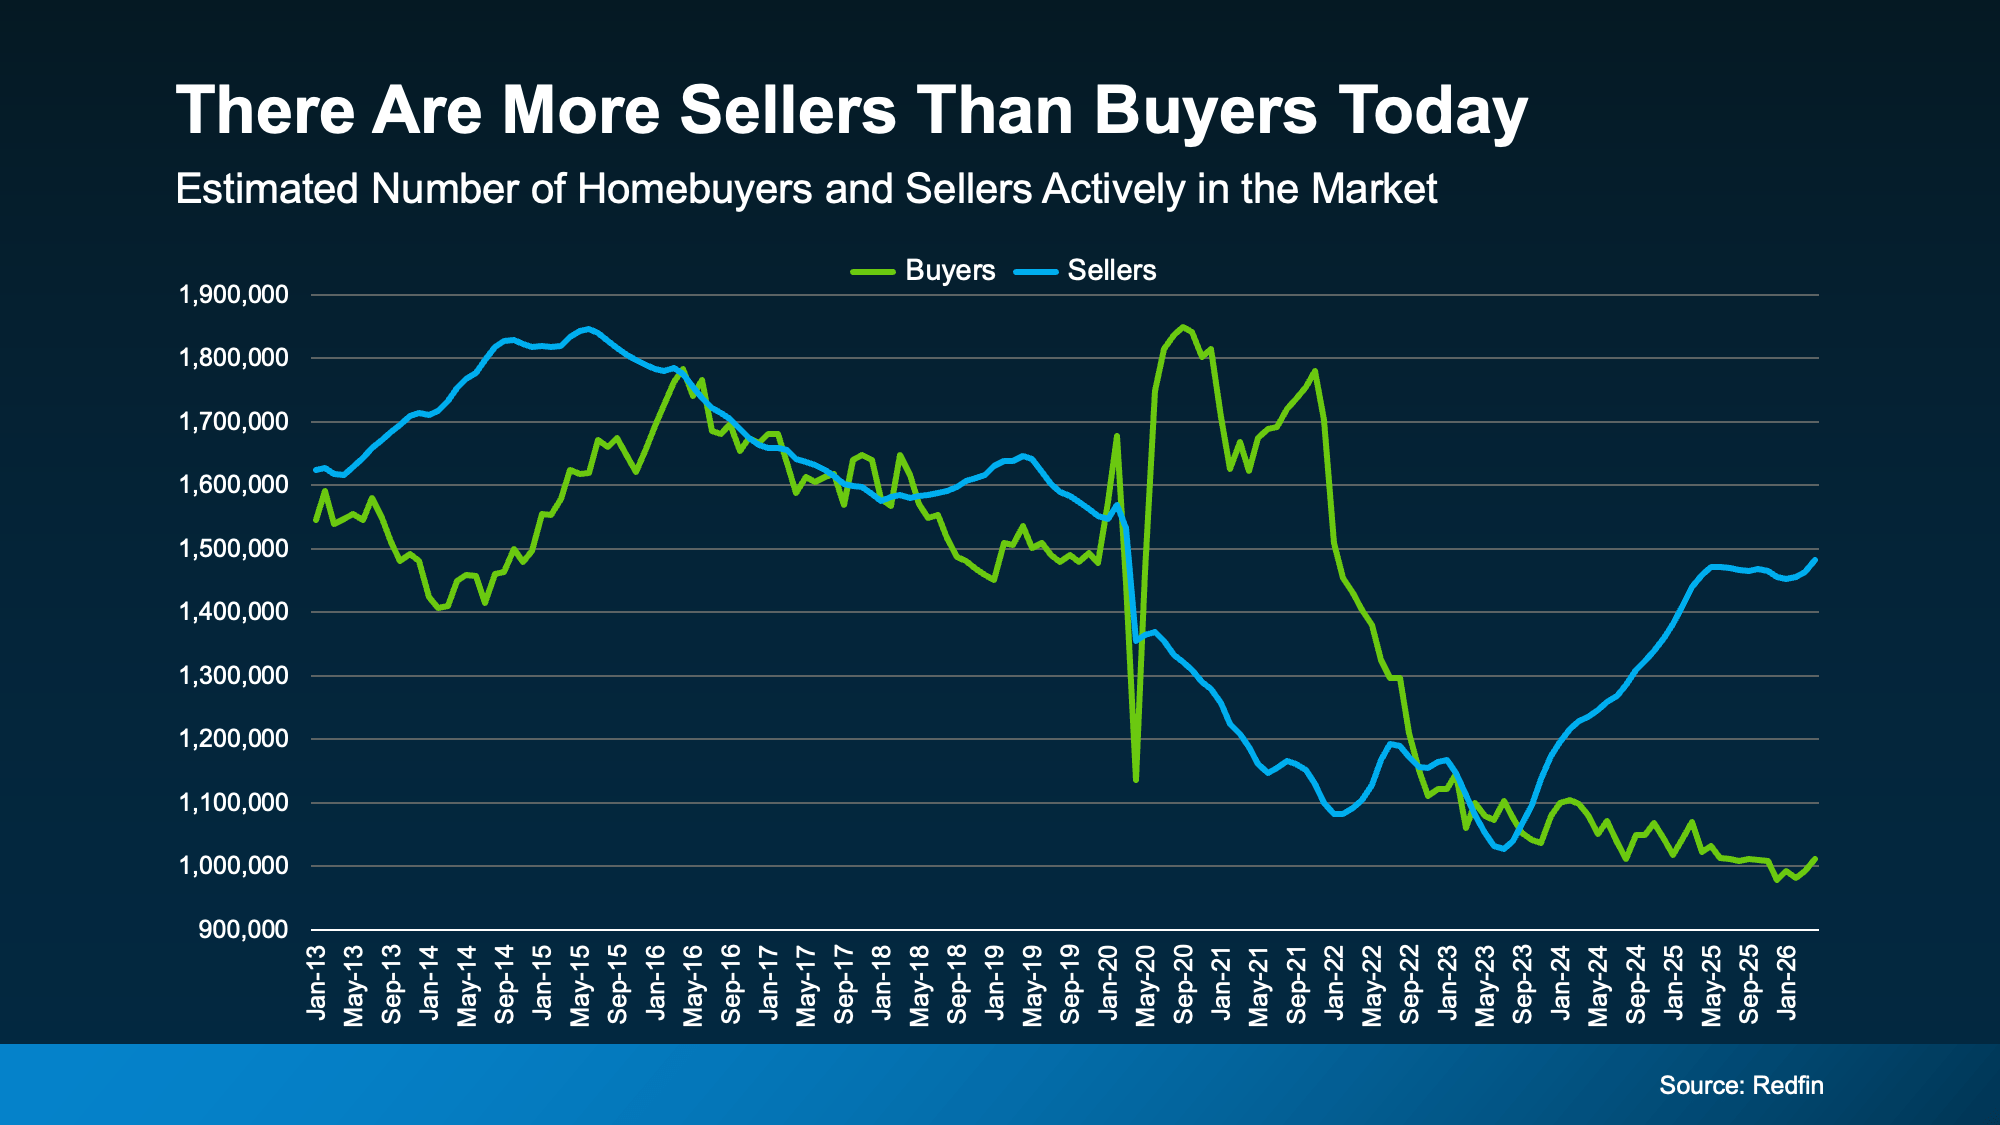
Redfin data shows there are more sellers than buyers active today. And that shifts the market dynamics (see graph below):
a graph of sales and buyers

That doesn’t mean every market favors buyers. Far from it. In some areas, homes are still selling quickly and sellers have plenty of leverage. But in others, buyers have more room to negotiate than they’ve had in years.

That’s why local market conditions matter so much when you make your decision.

For example, helping with closing costs may be worth considering if:

  • There are a lot of homes for sale in your area

  • Your house has been sitting on the market longer than expected

  • You’ve had showings, but no offers

  • You’re motivated to move quickly

  • Or you’re trying to keep a deal together during negotiations

After all, if it’s the thing that helps bring a serious buyer across the finish line, it could be well worth it.

Other Concessions You Could Offer Instead

Just remember, being flexible doesn’t mean saying “yes” to every request.  It means understanding which compromises actually help you accomplish your goals. Because there are always alternatives.

Redfin suggests considering other concessions if you’re not interested in helping with closing costs, like:

  • A home warranty

  • Repair credits

  • Flexible closing dates, or

  • Leave behind appliances or furniture

The right answer depends on what buyers in your market are asking for and what matters most to you. That’s exactly why working with an experienced local agent is so important.

Bottom Line

The sellers having the most success today are the ones who understand the market has changed and are adapting to meet it where it is.

Sometimes that means negotiating on closing costs. Sometimes it means offering something else. The key is knowing which concessions are worth it for your local market.

If you’re wondering what’s normal in your area, what’s worth negotiating, and where it makes sense to stand firm, connect with an agent.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
Two Big Reasons To Move This Summer

Two Big Reasons To Move This Summer Simplifying The Market

A lot of people who want to move are telling themselves the same thing: “Maybe I’ll just wait until later this year once things calm down.” 

While waiting sounds like a good plan, there’s something worth knowing before you decide. Rates aren’t expected to change much, so if that’s the #1 reason you’re waiting, it may not pay off. And there may be other things you miss out on in the meantime. 

Historically, Summer is one of the strongest seasons of the year for both buyers and sellers. And if you delay your move until Fall or Winter, some of those opportunities may already be fading.

Buyers: Fresh Inventory Is Your Real Summer Advantage

One of the biggest frustrations buyers have faced over the past few years has been a lack of affordable options. Maybe you’ve run into that yourself:

  • You find a house you like, but it’s out of your budget.

  • You find something in your budget, but you don’t like it.

  • Or worse, nothing interesting hits the market for weeks.

Historically, Summer helps with that.

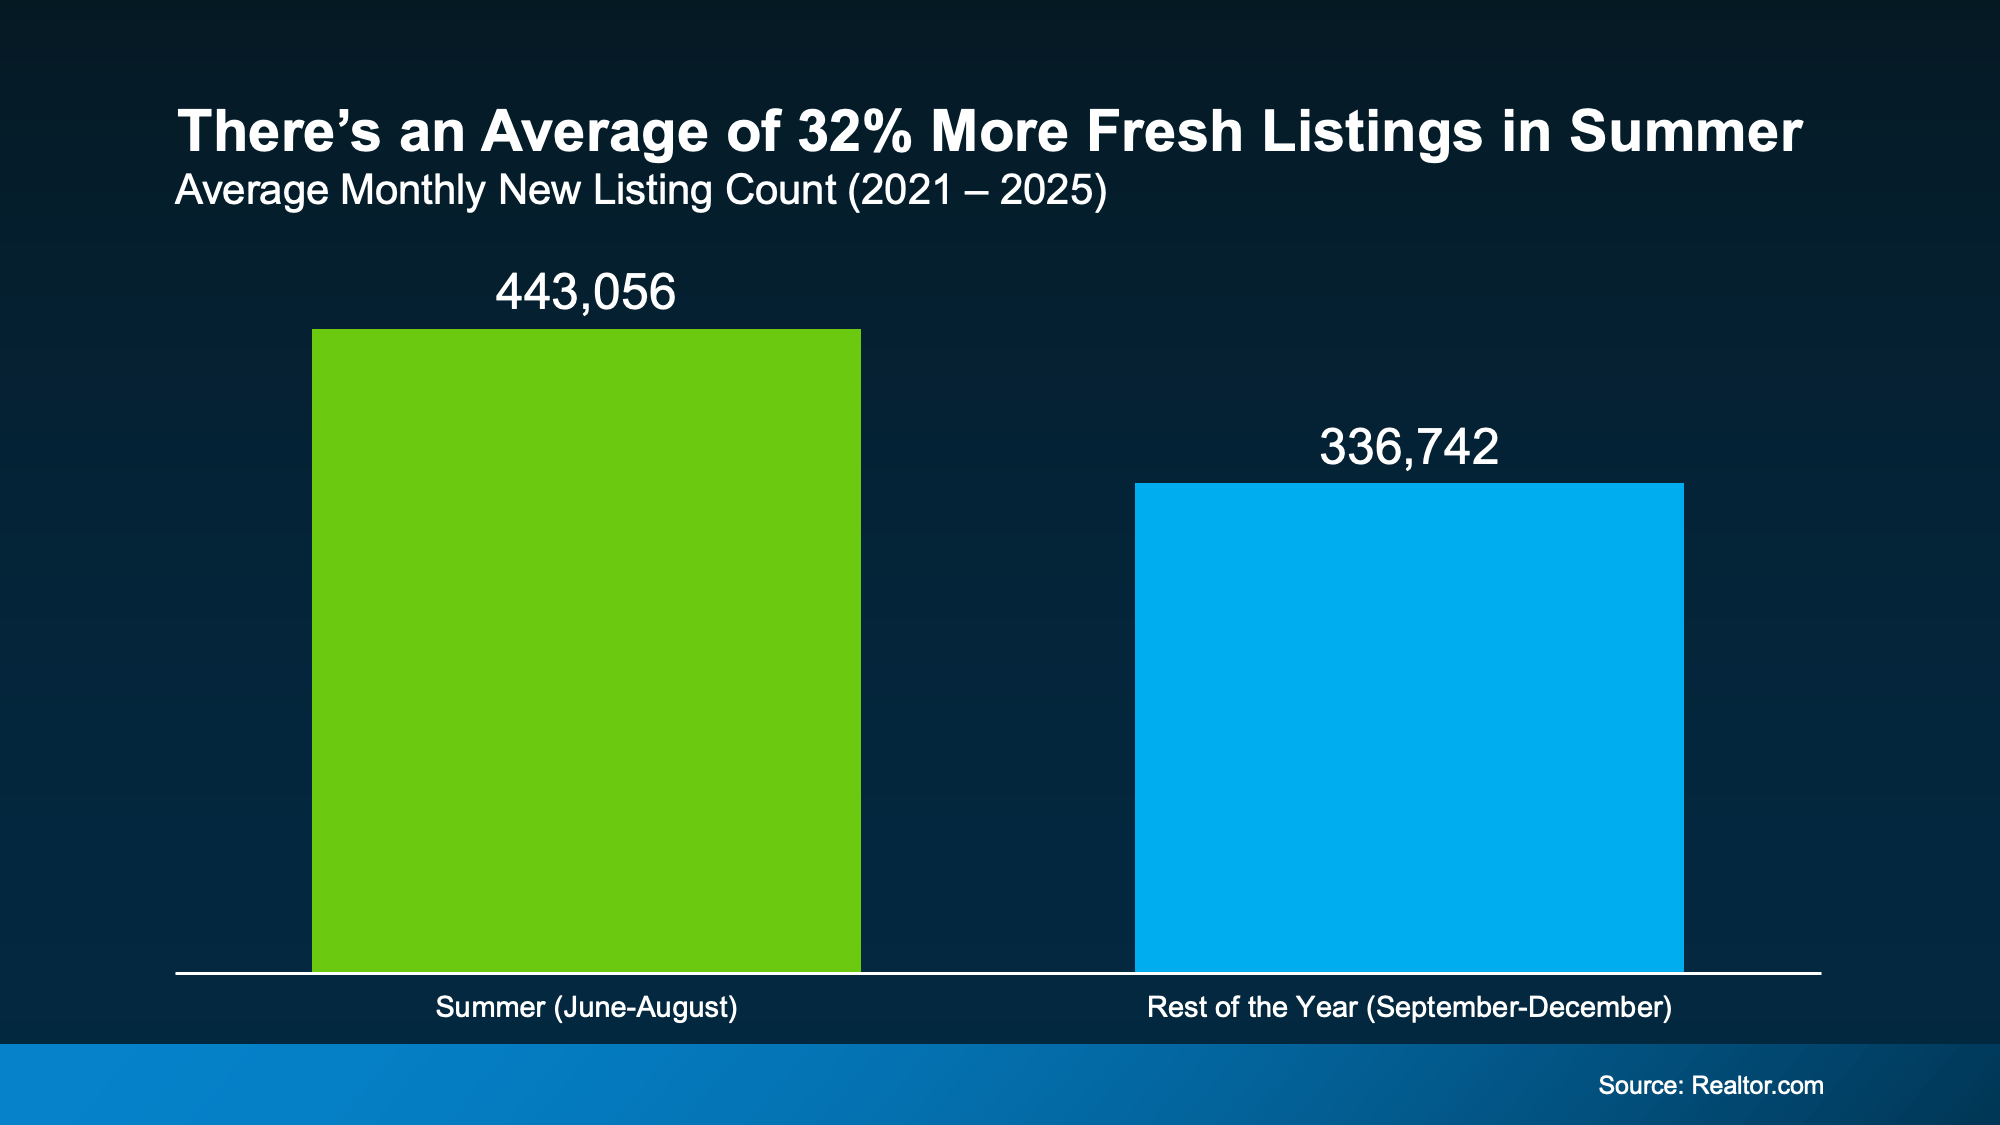
Looking at data from the last few years, Summer months consistently bring more sellers into the market than later in the year. And that gives buyers a real window of fresh choices.

According to Realtor.com, any given Summer month typically sees about 32% more fresh options than the average month from September-December.

a graph showing a number of prices

With more newly listed homes, there’s a better chance of finding one you like where the numbers actually work.

Because all it really takes is one home to completely change your search. And if you’ve got more popping onto the market to choose from, maybe one of those is exactly what you need. 

But keep in mind, this seasonal window isn’t open forever. Fresh inventory tends to slow down once Summer ends.

Many homeowners who planned to sell this year have already listed by then. Families who wanted to move before school starts have often already gotten it done, or at least, set it into motion. So, new listing activity usually cools as we head into Fall and Winter.

Of course, every year is different. But if finding the right home at the right price has been your biggest challenge, waiting until later in the year may not necessarily give you more options. In fact, recent history suggests it may do just the opposite.

Sellers: Homes Usually Sell for More in the Summer

If you’re thinking of selling, you may be considering holding off because you’ve seen headlines about lower asking prices, price cuts, and softer conditions in some markets. But those headlines don’t tell the whole story or convey just how much it varies by area.

Here’s what you really need to know. Even though the market’s becoming more balanced and some pockets are experiencing price declines, that doesn’t mean you’ve missed your chance to sell. 

Seasonality can still work in your favor no matter where you are. And this Summer could still give you the chance to sell for a good price.

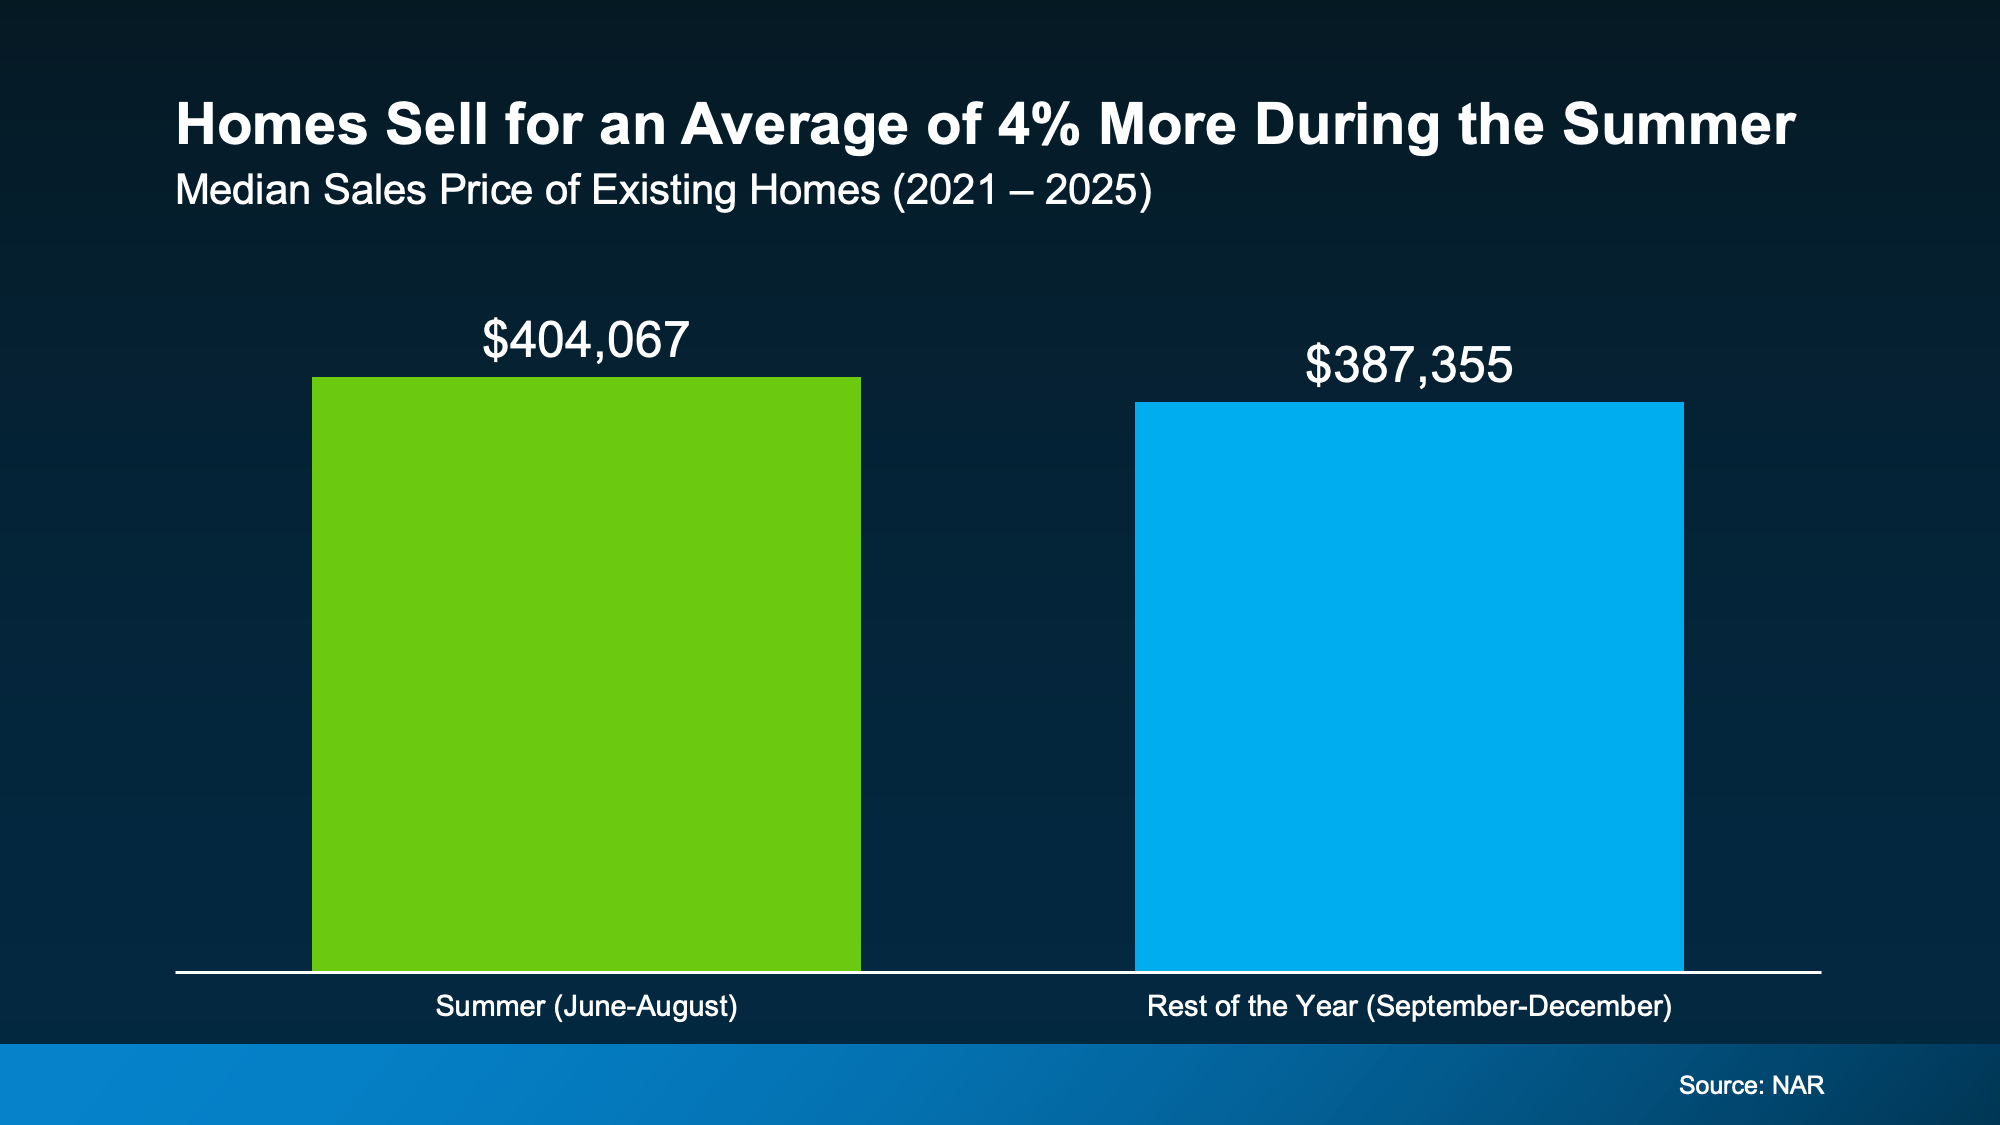
According to the National Association of Realtors (NAR), homes sold during a Summer month usually sell for about 4% more than homes sold during the typical month from September-December:

a graph of a sales report 

Why? Summer buyers are usually operating on a set timeframe. They’re trying to move before the next school year or when they have more PTO and warmer weather to tour houses. That urgency can translate into better offers.

Now, that doesn’t mean you should price your house 4% higher this Summer. That would actually be a mistake in today’s market.

It just means if you’re looking to get as much for your house as you reasonably can, a Summer move could be a smarter play than waiting until later this year. 

Because based on typical seasonality, you may get more for your house than you would if you waited until the Fall or Winter (when there are typically fewer buyers active).

And if you’re considering a move anyway, that’s worth factoring in.

Bottom Line

Could waiting until later this year work out? Sure. But it’s important to understand what you may gain by moving now too – that way you have the full picture before you decide.

If a 2026 move is on your radar, talk to an agent about what matters most to you. Depending on your priorities, Summer could be your moment.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida

Is Late May the Best Time To List Your House?

Is Late May the Best Time To List Your House? Simplifying The Market

You may have heard April 12-18 was the “best week” to list your house. That’s based on a report from Realtor.com. But now that it’s passed, you may be wondering if you missed your moment.

Here’s the good news – you didn’t. 

Because the reality is, there isn’t just one perfect week to sell your house this Spring. There’s a window. And right now, you’re still in it.

Your Window To Sell Is Still Wide Open

Here’s why. Different organizations run studies like this every year. And they don’t always land on the exact same week. That’s okay. It’s because they’re using different research methods and even different definitions of what “best” means.

But the fact that the results vary points to a larger trend. While there may be sweet spots, the entire Spring season gives sellers an opportunity to get some of the best conditions (and best sales prices) of the year.

And it’s definitely not too late to jump in.

Why Listing in Late May Is the Perfect Play

According to Zillow, the best time to list your house this year is the last 2 weeks of May. And that’s approaching fast.

Based on their analysis, this is the ideal time to do it if you want to make top dollar. Because, in this 2-week window, homes sell for more. Sometimes, quite a bit more.

Depending on where you are and the price point in your area, some homeowners may even net tens of thousands of dollars extra in this sweet spot. As Zillow explains:

“Why late spring? Buyer demand typically peaks before Memorial Day. Families want to move during the summer and settle in before the new school year. More buyers shopping at once can spark competition and lift prices.”

And they’re not the only ones saying listing in May could be the key to selling for more. ATTOM Data analyzed almost 52 million home sales over the past 10 years and found sellers in May are achieving some of the highest returns.

That means the ideal window this year is very much still open.

What This Means for You 

If your goal is to sell for the strongest possible price, this is where timing and strategy come together. And you want to be sure you’re ready to make the most of it.

So, what should you be doing right now?

When prepping for a fast-moving window like this, you don’t want to waste time or money on the wrong prep work. And your agent is your go-to to make sure you’re focusing on the right things.

They’ll be able to tell you if the “best week” is slightly different in your market. And what quick repairs or updates can help you get a higher price, without taking a ton of time or effort.

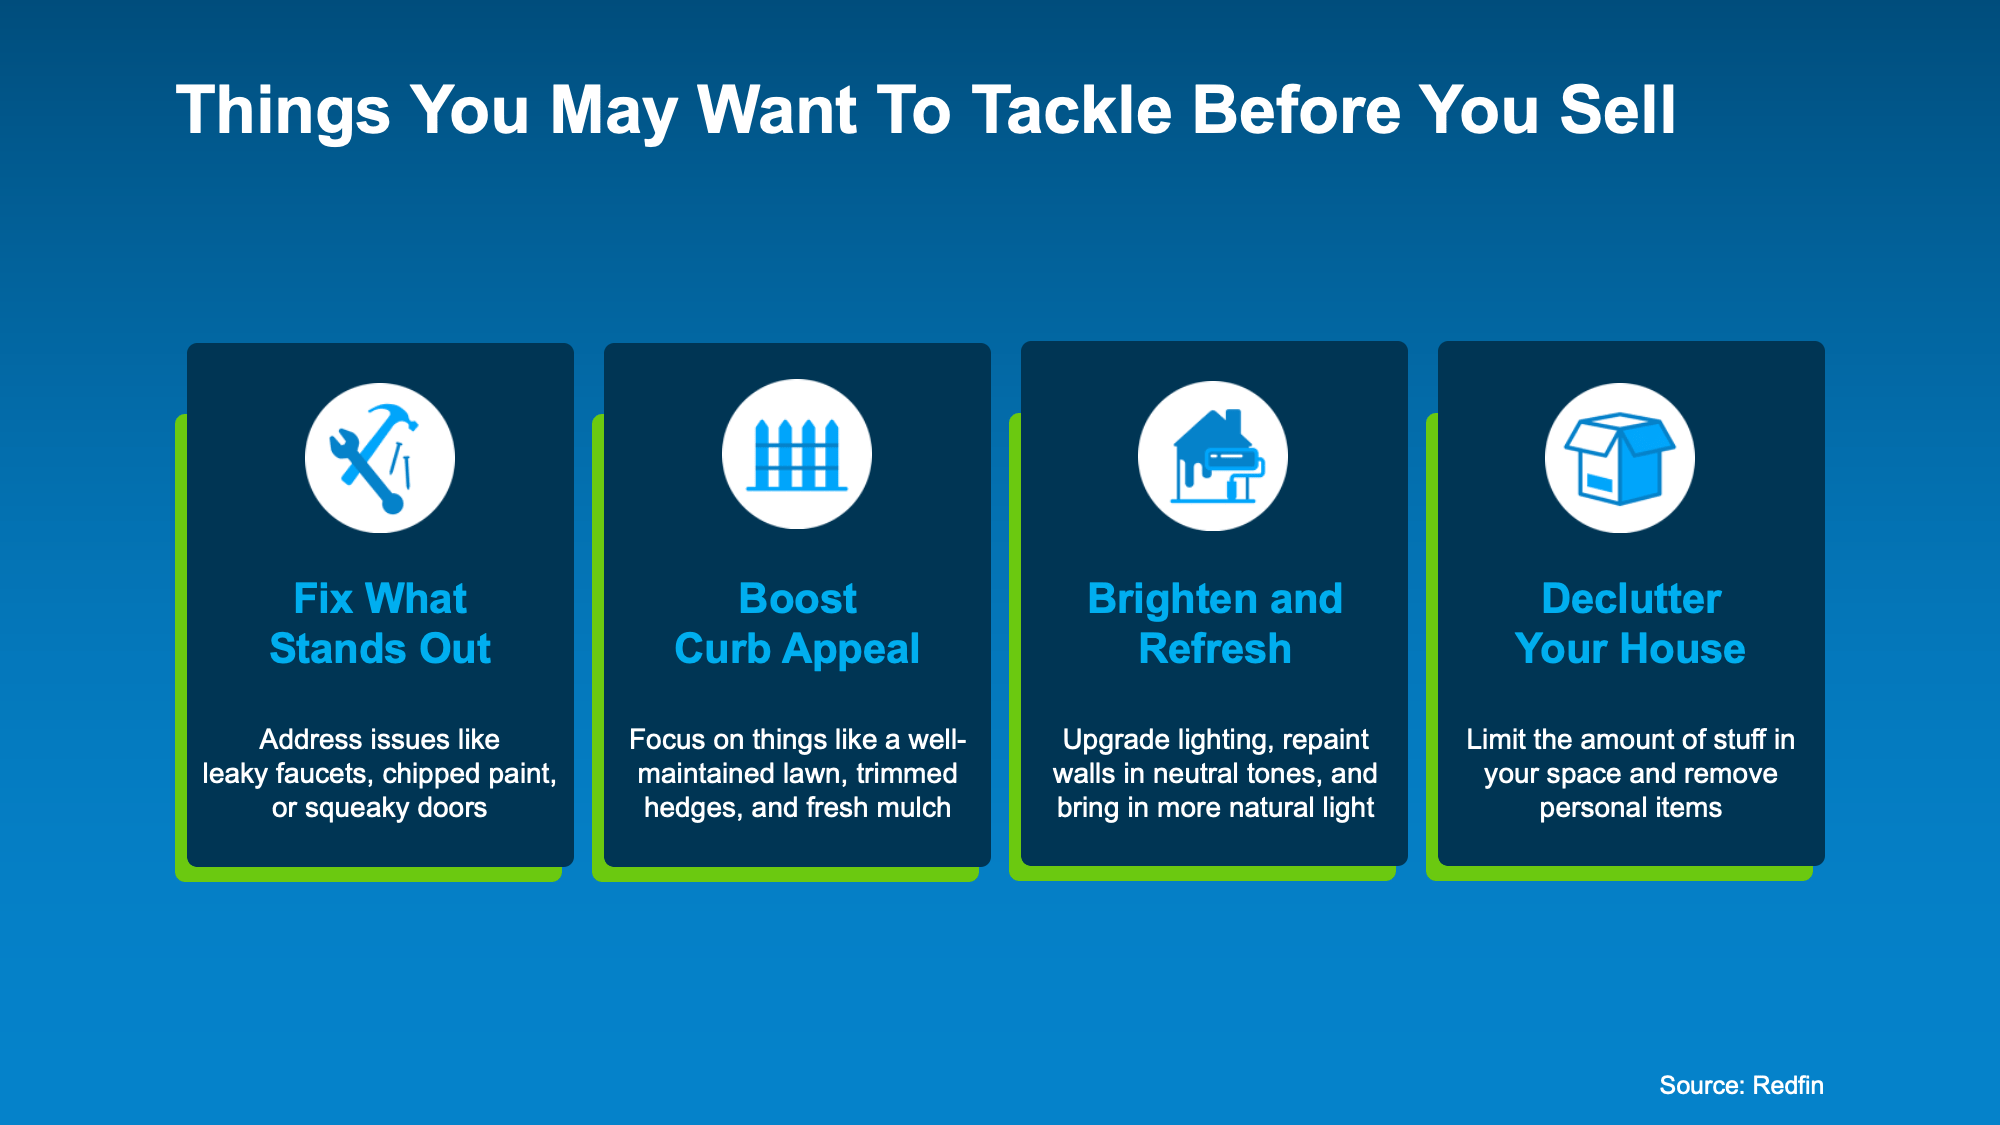
Here’s a quick example of things an agent may recommend based on information from Redfin:

At the end of the day, when your prep time’s short, doing the right things matters more than doing more things.

Bottom Line

Zillow says the best time to list your house is just around the corner. Are you ready to make the most of it?

If you want to take advantage of this Spring sweet spot and get top dollar for your house, talk to a local agent about what you need to do now to get ready to hit the market.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida

Stay or Sell? How To Make the Right Call as You Age

Stay or Sell? How To Make the Right Call as You Age Simplifying The Market

At some point, as you start thinking about the years ahead, this question tends to come up:

“Could I stay here long-term… or would it make more sense to move?”

It’s not always urgent. It often shows up in small moments, like going up and down the stairs, keeping up with the maintenance, or just thinking about what the next chapter of your life might look like in this home.

And for most people, the answer is simple. They want to stay.

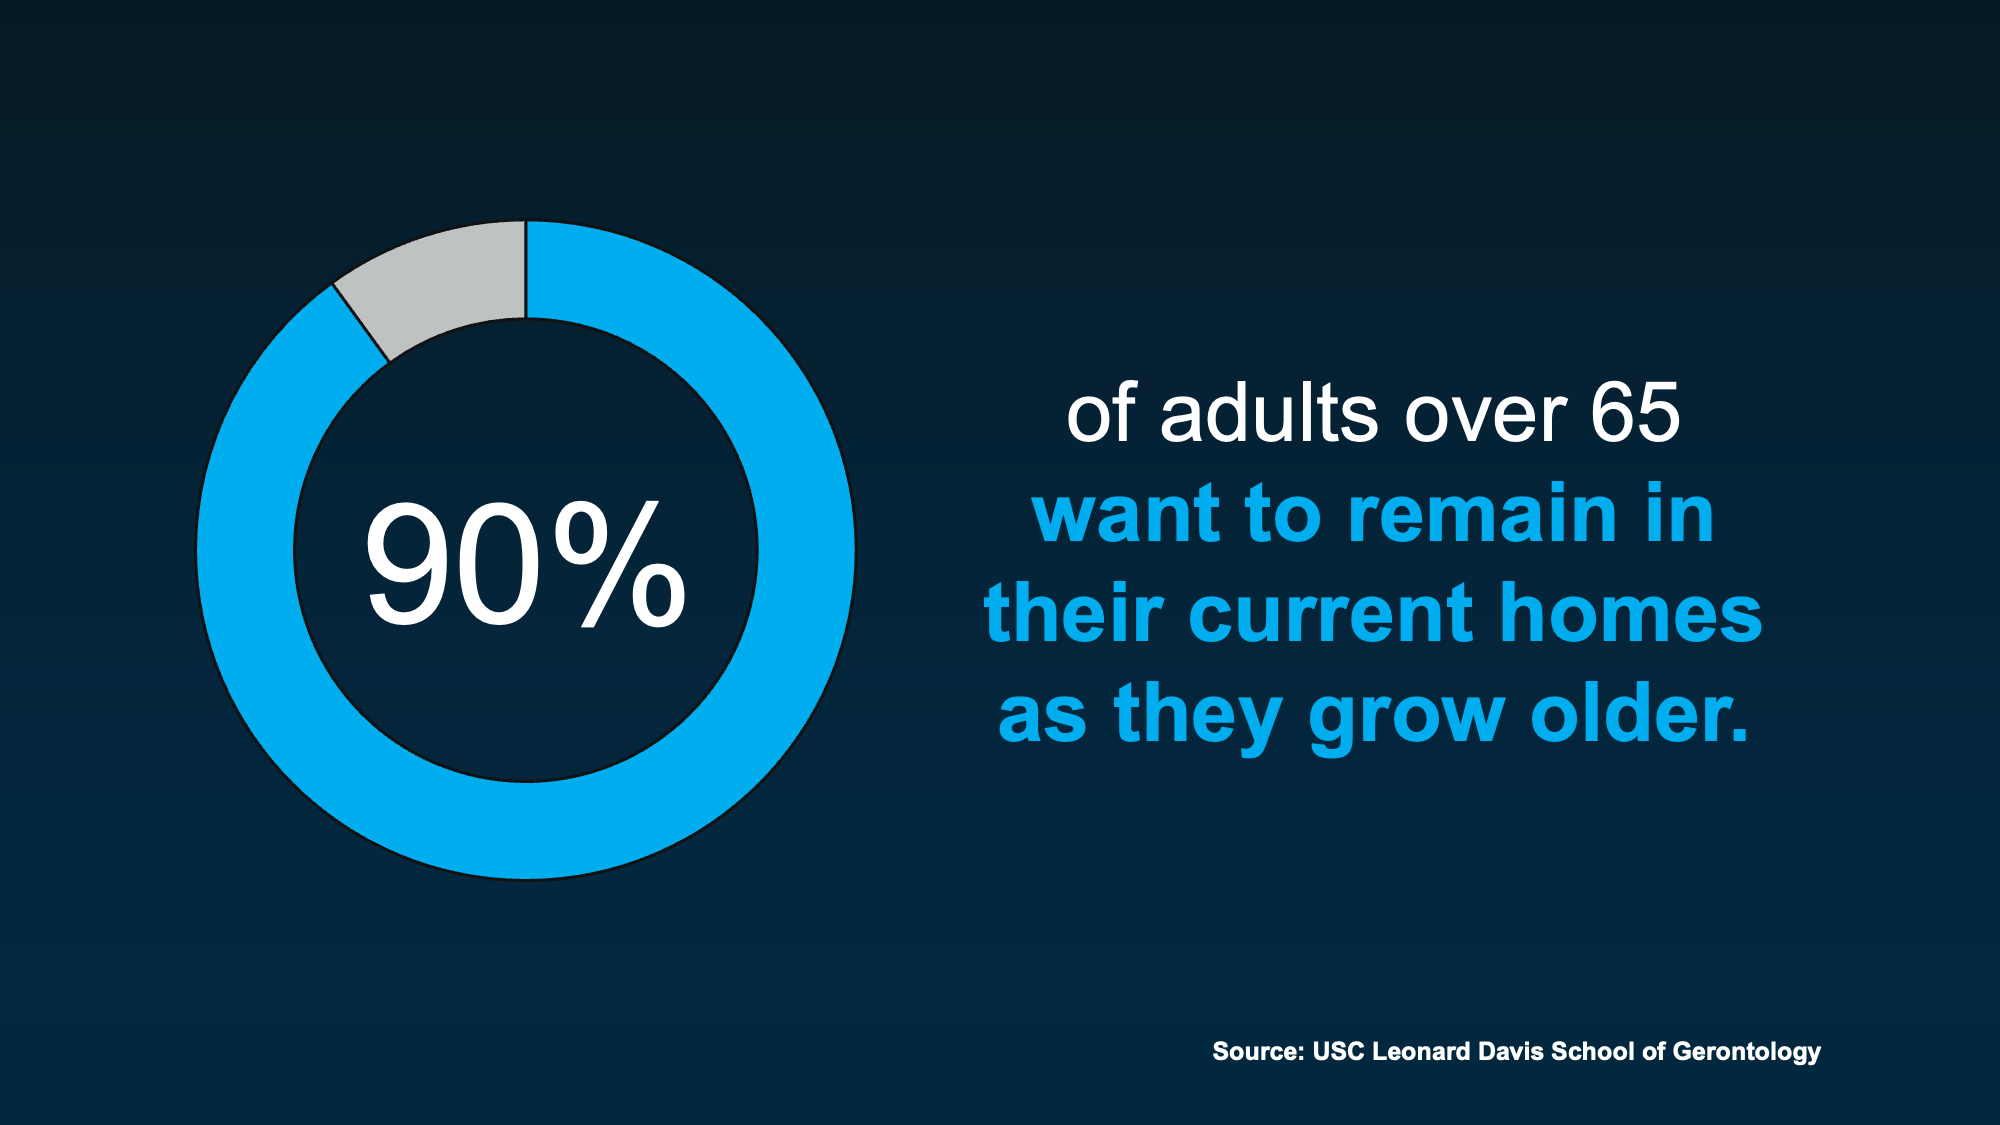
The USC Leonard Davis School of Gerontology found about 90% of adults over 65 prefer to stay in their homes as they get older (see below):

a blue circle with white textBut even if staying feels like the right answer, it’s still worth thinking ahead about what that might actually look like. That’s where the right agent can really help.

What You Need To Plan for If You’re Staying in Your Home

Aging in place is definitely possible. But it’s better if you have a plan. And here’s why. The home that once worked perfectly may need to change with you over the years. And it’s easier if you can anticipate those expenses.

  • Sometimes that means small updates: like adding grab bars in the shower.
  • Other times, you’ll have to make bigger decisions: like reworking layouts or moving key spaces to the first floor.

Some of those changes are going to be simple. Others can be a meaningful investment. And that’s why thinking about it early matters. Not because you need to decide anything right now, but because it gives you time.

  • Time to understand what your home may need.
  • Time to explore your options.
  • Time to find the right contractors.
  • Time to space out the expense of the upgrades.

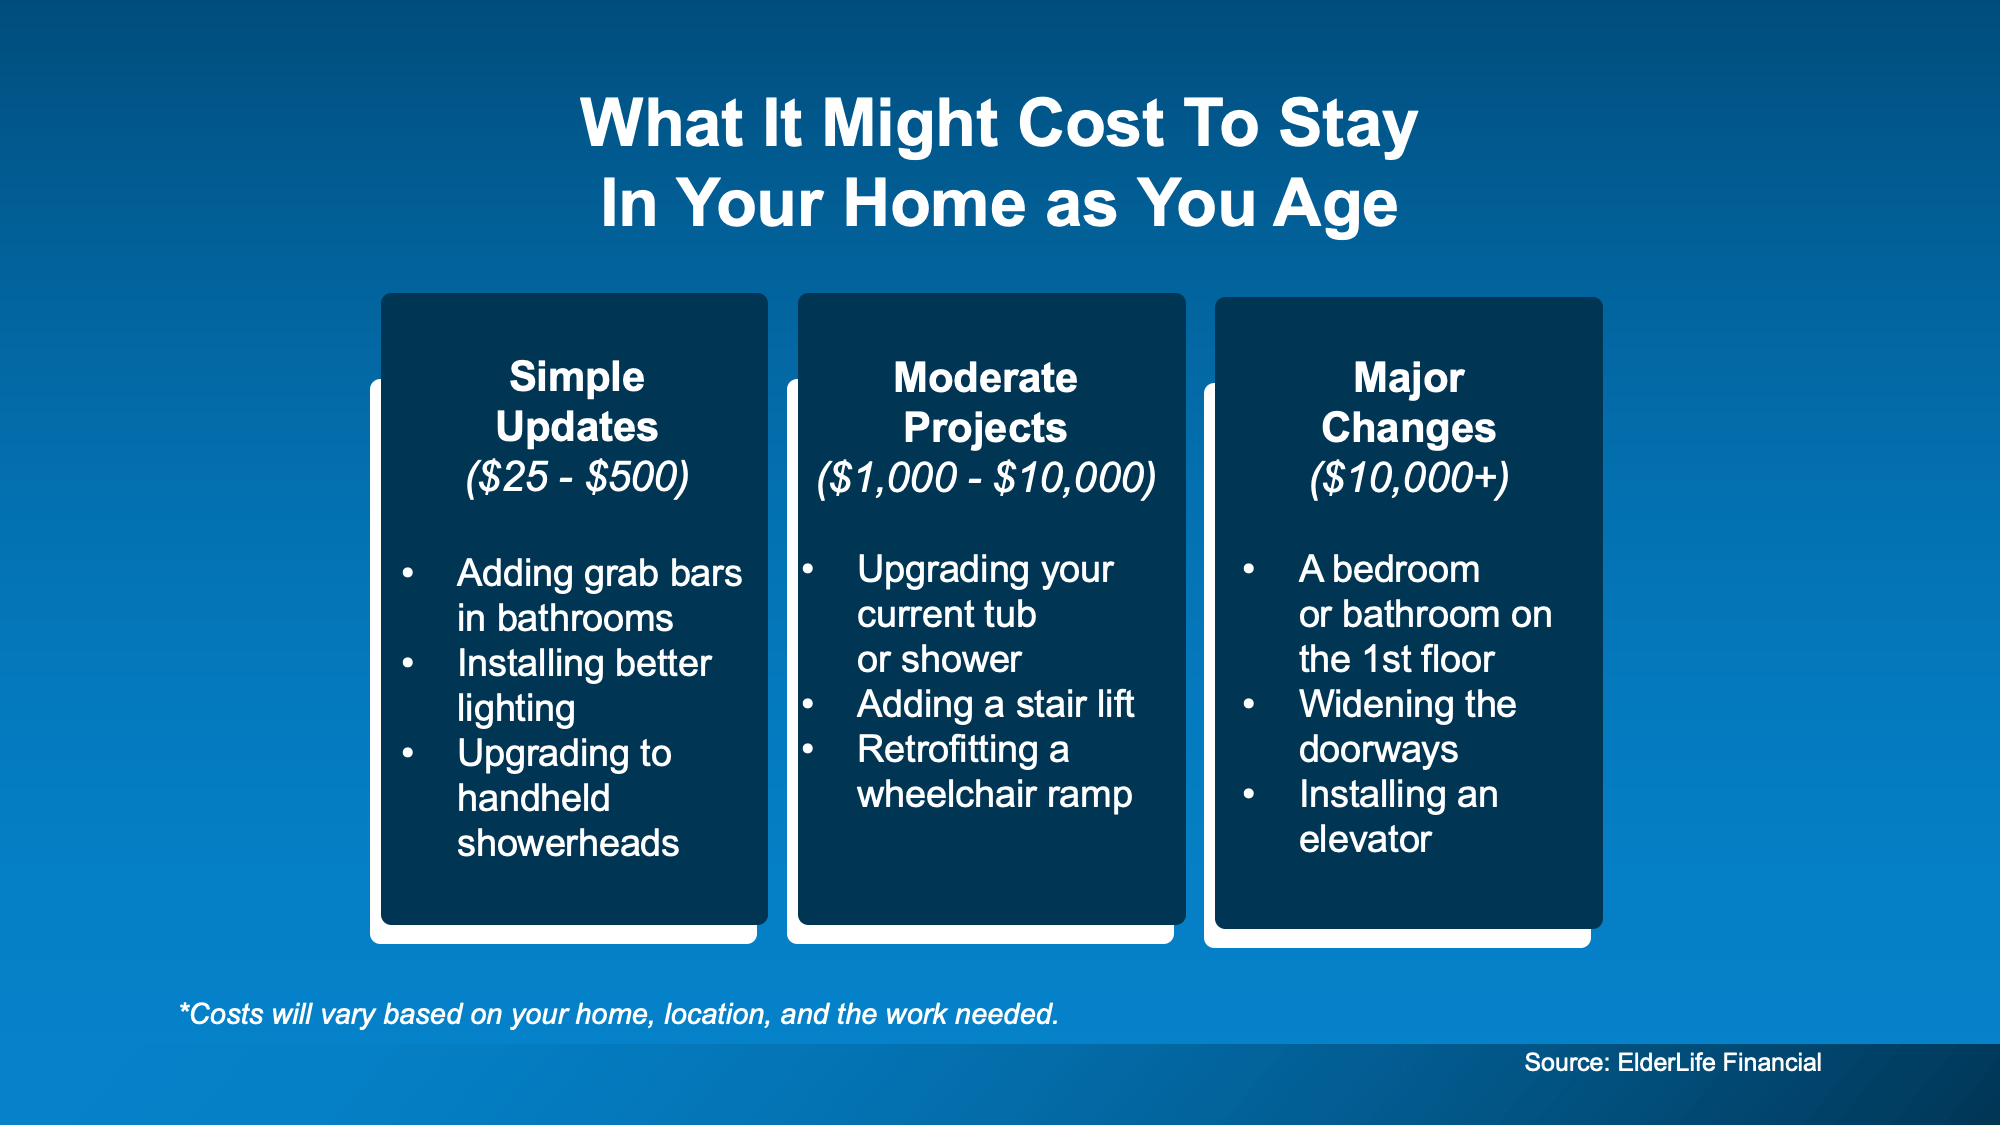
According to ElderLife Financial, here’s a rough baseline of what it could cost depending on what needs to be done (see below):

a blue and white rectangular signAnd don’t worry. If your heart is really set on staying, but the costs feel like a concern, it helps to know you have options. Depending on your situation, there may be financial assistance programs available, along with tools like home warranties to help manage unexpected costs.

Just remember, if you’re thinking about making updates, it’s always worth having a quick conversation before you start. A real estate agent can help you understand which changes tend to make sense for your situation and how they may impact your home’s value based on your local market.

When Moving Might Make More Sense

But staying isn’t always the best fit for every situation. According to Pegasus Senior Living:

“While most seniors hope to age in place, practical considerations sometimes make selling a home the wiser choice.”

Sometimes, it comes down to a simple shift: when the home that once made life easier, starts to make it harder.

That might look like:

  • Maintenance or yardwork that’s starting to feel overwhelming
  • Stairs or layouts that are getting harder to manage day-to-day
  • Or needing more support or care or being too far from loved ones

And sometimes, it’s not about necessity at all. It’s about lifestyle. Some homeowners just don’t want to live through major renovations. Others are ready to simplify, downsize, or move somewhere that better fits this next chapter, whether that’s a smaller home, a 55+ community, or a place closer to family. 

For them, moving simply means making daily life easier.

Bottom Line

There’s no one-size-fits-all answer here.

Some people stay and make updates. Others move to simplify things. Either can be the right choice. The goal isn’t to pick one today. It’s to understand your options early, so when the time comes, you feel confident instead of rushed.

And if you ever want a sounding board to think through what the future could look like for you, a local real estate agent is there to help.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida

Your House Hasn’t Sold Yet. Should You Rent It Out Instead?

Your House Hasn’t Sold Yet. Should You Rent It Out Instead? Simplifying The Market

When your house sits on the market longer than expected, it can get frustrating fast.

You start asking: what now? And for a growing number of homeowners, that turns into: should I just rent it instead?

While it sounds like a simple backup plan, becoming “accidental landlord” is actually a much bigger decision than most people realize. That’s when someone planned to sell, didn’t get the price or traction they hoped for, and decided to rent the house out instead.

And lately, that’s happening more often.

Why the Number of Accidental Landlords Is Rising

If you’re faced with the same choice to rent or to sell, here’s what you need to know. First, you’re not alone. And that should actually be some comfort.

According to Zillow about 2.3% of homes available for rent were previously listed for sale. That may not sound like a lot, but it’s actually the highest share in almost 6 years.

Before you go that route yourself, it’s worth slowing down and looking at the full picture. Ask yourself these 3 questions first.

1. Would Your House Actually Work as a Rental?

What’s right for your situation is going to depend on your location, your home’s condition, and what the rental market looks like in your area. Think about:

  • If you’re moving away, do you have a plan for how you’ll handle ongoing maintenance and repairs from afar?
  • Does your house need repairs before it’s rental-ready? And do you have the time, energy, and the funds for that?
  • What’s the market like in your area? Are there a lot of rental vacancies?
  • What monthly rent could you realistically expect?

As C&C Property Management explains:

“At the heart of any rental market is the balance between supply and demand. When more tenants are looking for housing than there are available units, rental prices rise. On the other hand, if new construction adds hundreds of apartments or homes to a neighborhood, prices can soften as tenants have more choices.”

If your home would struggle to stand out or command the rent you need, that’s something to take seriously. Just because you can rent it doesn’t mean it’s the best option for you.

2. Are You Ready To Be a Landlord?

This is the part people don’t always think about upfront. On paper, renting sounds like easy passive income. But in reality, it’s a hands-on responsibility. Imagine:

  • Taking midnight calls about clogged toilets or broken air conditioners
  • Chasing down missed rent payments
  • Covering unexpected repairs
  • Fixing damage between tenants

And those costs can hit when you least expect them.

3. Have You Run the Real Numbers?

There’s also the financial side of things. For starters, renting out your house comes with extra expenses. Here are a few of the biggest according to Bankrate:

  • Higher insurance premiums (landlord insurance typically costs about 25% more)
  • Management fees (if you use a property manager, they typically charge around 10% of the rent)
  • Routine maintenance and services
  • Advertising fees to find tenants
  • Gaps between tenants, where you cover the mortgage without rental income coming in

For some people, that’s totally manageable. For others, it’s more than they want to take on.

Your Next Step: A Conversation with Your Agent

Before you make any decision, talk to your current agent about overhauling your sales strategy first. Sometimes it’s not that buyers aren’t out there. It’s that something about the pricing, presentation, or marketing isn’t quite lining up with what they’re looking for.

And a few small adjustments can make a big difference.

Because while renting can be a great choice for the right person with the right house, if you’re only considering it because your listing didn’t get traction, there may be a better solution.

Bottom Line

If you’re torn between selling and renting, make sure to carefully weigh the pros and cons first. For some homeowners, the hassle (and the expense) of renting may not be worth it.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida

Don’t Let Home Prices Headlines Fool You

Don’t Let Home Prices Headlines Fool You Simplifying The Market

Spend about 5 minutes online searching for news about the housing market, and odds are you’ll see something pop up about home prices. You may even stumble onto social media influencers saying we’re headed for a crash. Let’s get you the context you need.

The truth is prices are going to vary depending on where you live. But they’re not crashing.

Here’s what you need to know.

The Local Perspective: Home Price Trends by Area

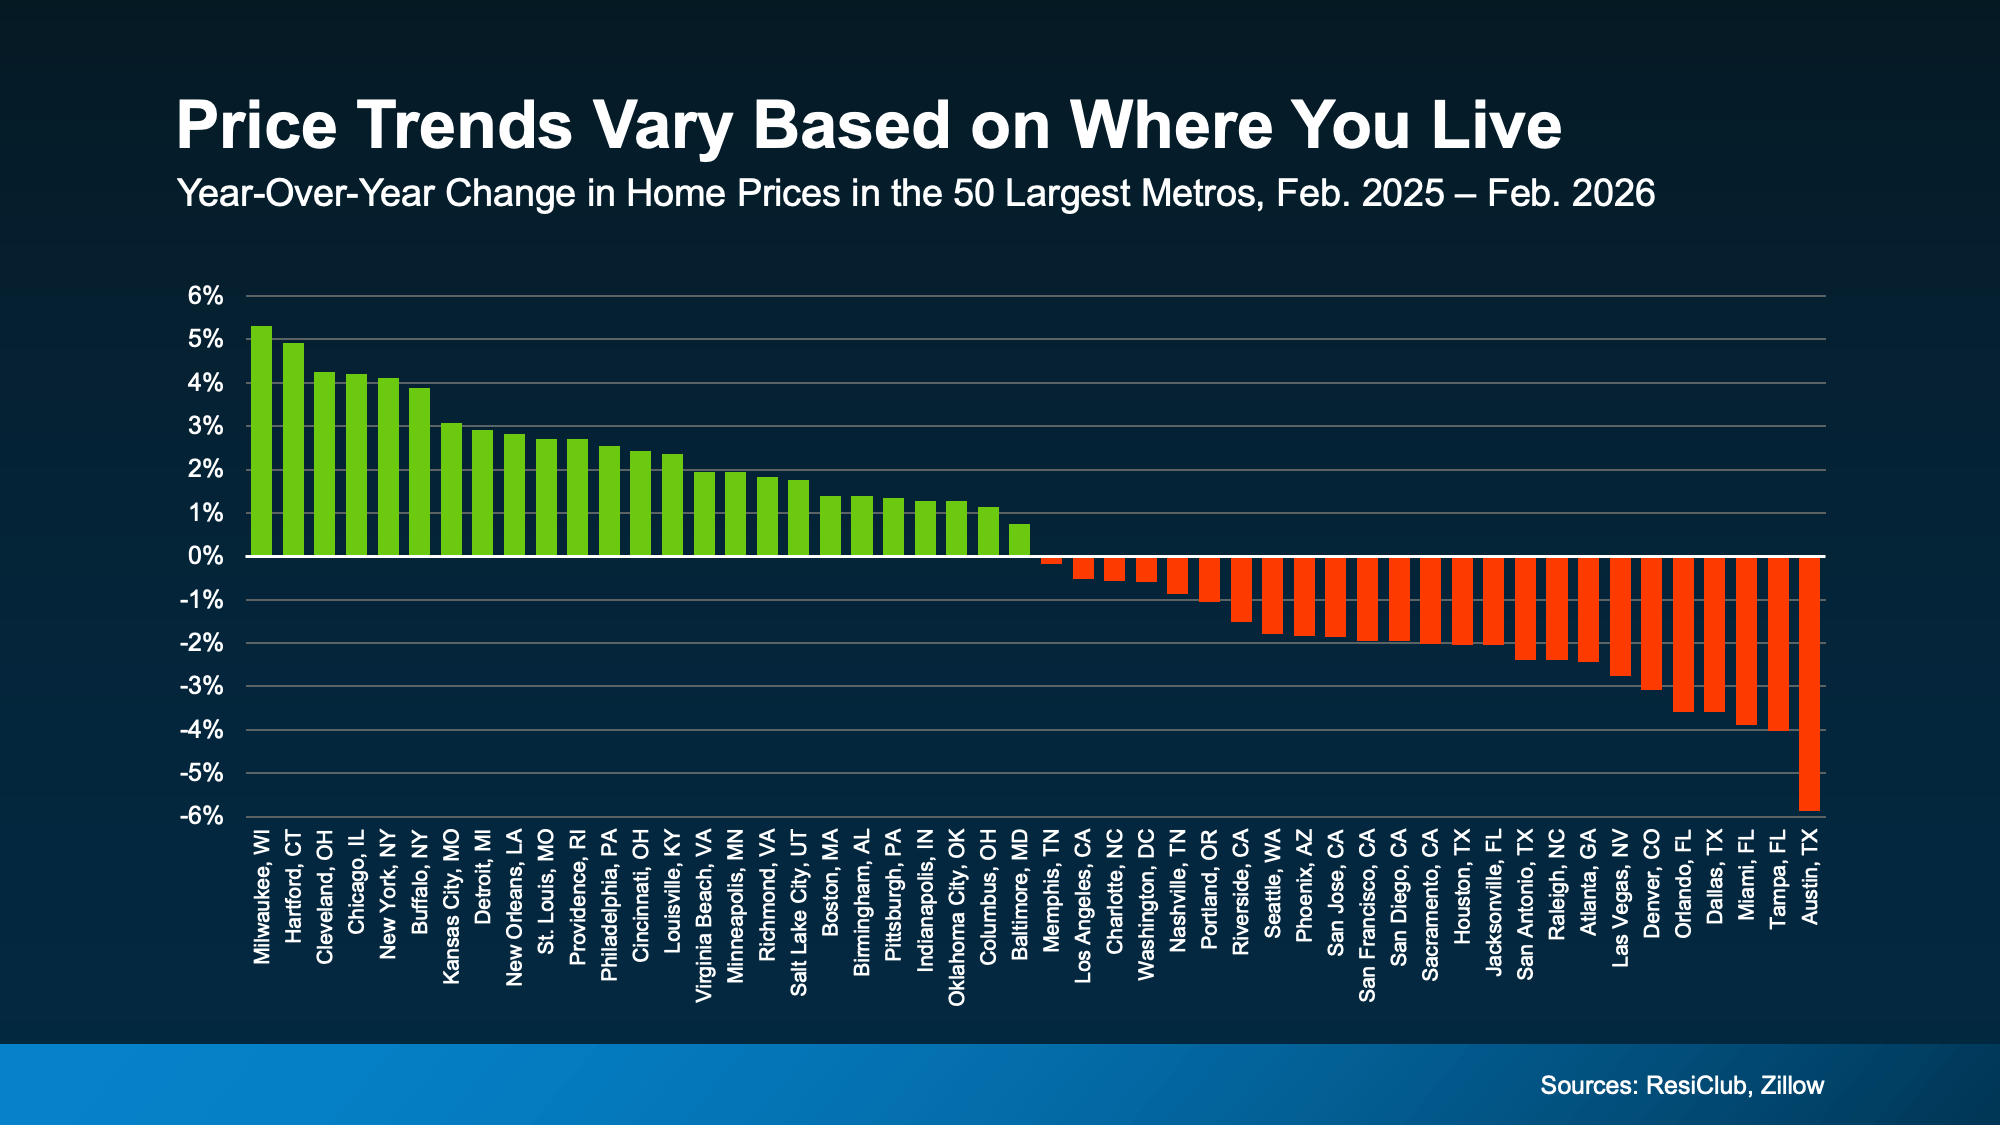
The biggest thing feeding into the confusion online is how different home price trends are by area right now. Take a look at this data from ResiClub and Zillow (see graph below).

About half of the largest metros are seeing prices go up.

The other half are seeing some declines.

a graph of different colored linesUnfortunately, the online chatter only focuses on the markets where prices are down – and that makes it sound like something bigger is happening.

But, as you can see in this graph, that’s only one side of the story. The full picture is different.

The National Perspective: Moderate Price Growth

As a country, when you average it all together to get a true baseline, one thing becomes clear, home prices are still net positive at the national level.

According to the Redfin, national home prices were up about 1% year-over-year in February. So, what we’re seeing right now isn’t a collapse. It’s a market that’s normalizing after a period of unusually fast growth. And that impacts some local markets more than others – particularly those where prices rose too far, too fast during the pandemic. 

A true crash, like what happened in 2008, would mean prices dropping sharply across the entire country. That’s just not what the data shows today. And it’s not where things are going either.

Experts Agree This Isn’t 2008

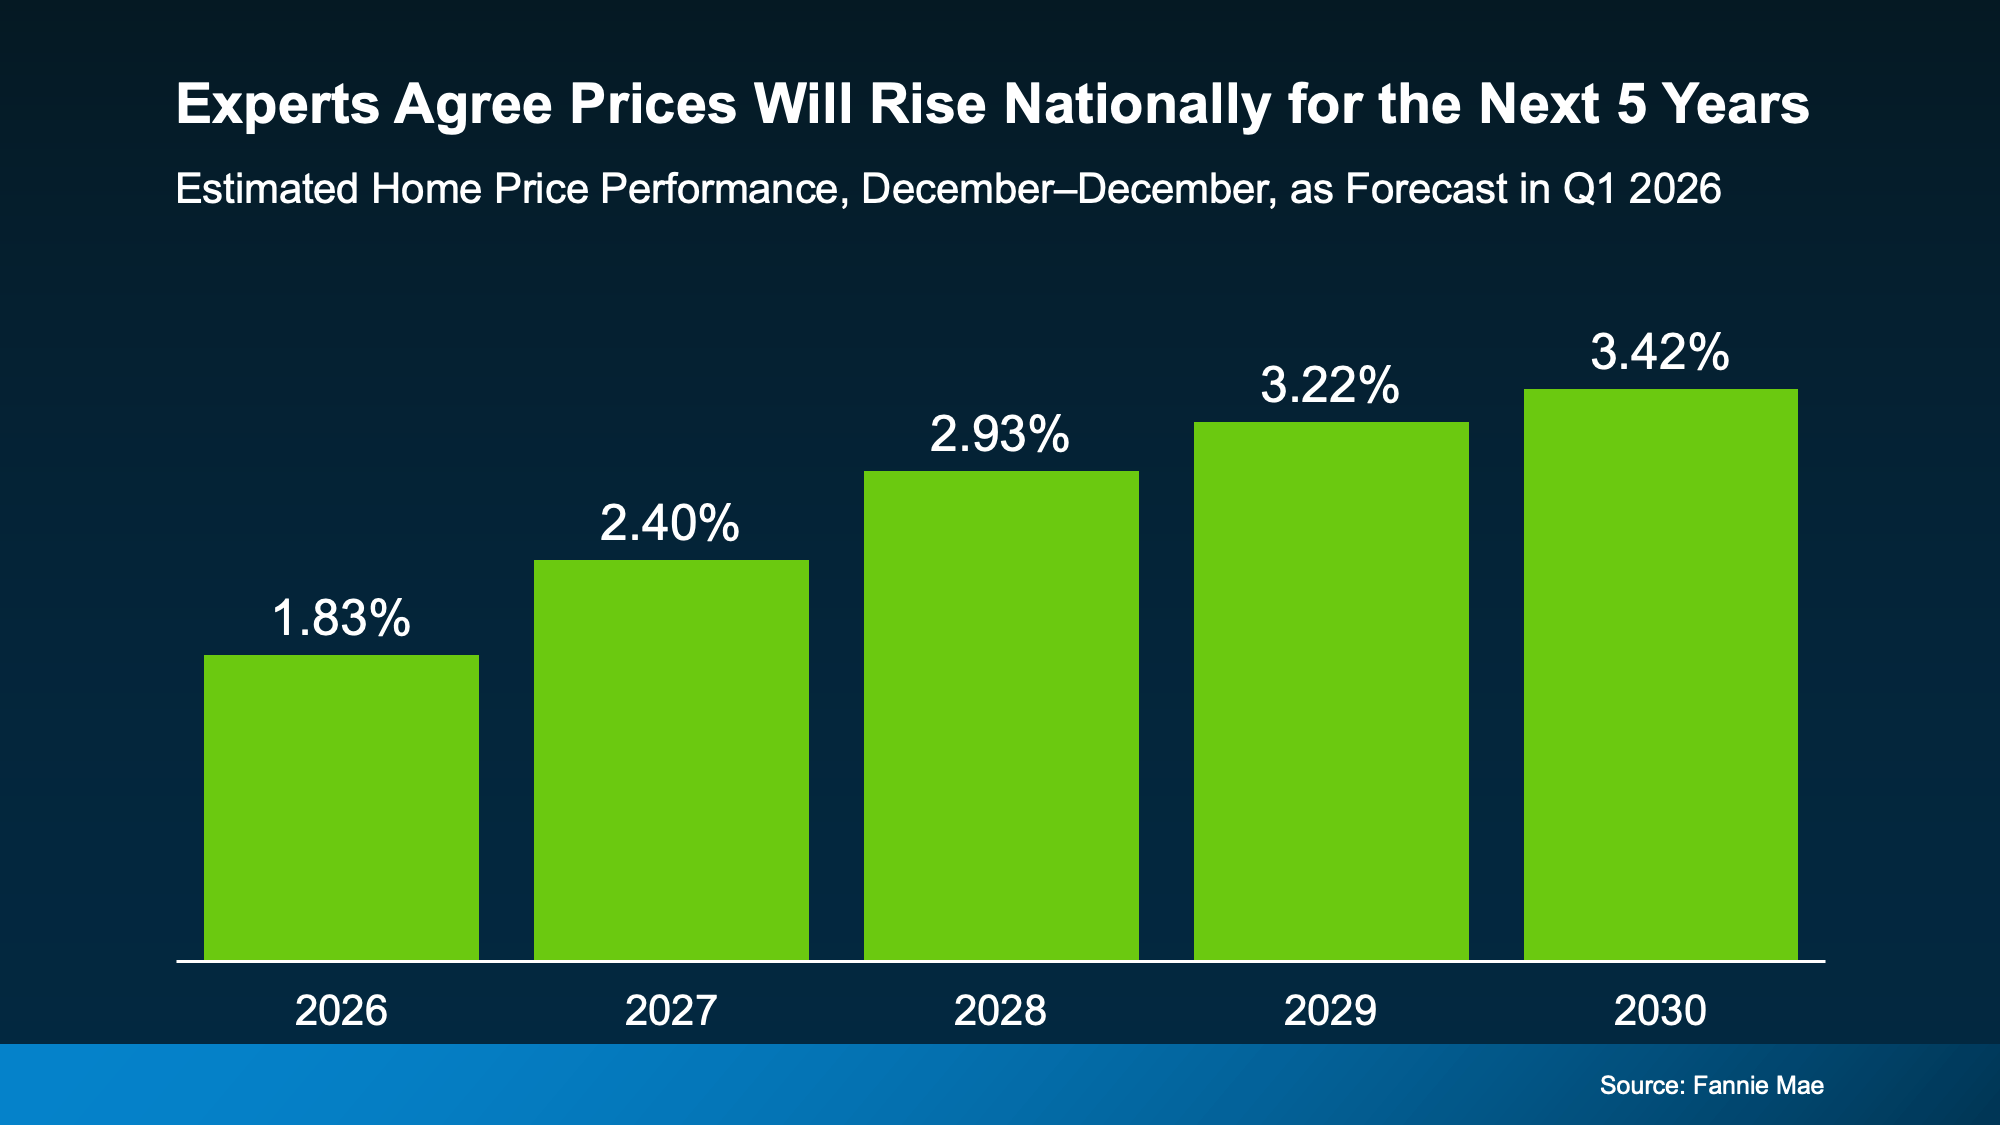
In fact, Fannie Mae surveyed over 100 housing market experts to ask their opinions on where prices are headed from here. And the experts agree, nationally, prices are expected to keep rising over the next five years: 

a graph of green rectangular bars with numbersThat rise will be moderate, particularly this year, but the trend is clear. Nationally, prices are forecast to grow every year now through at least 2030 – and that’s normal. Daryl Fairweather, Chief Economist, at Redfin explains:

“House prices aren’t going to fall on a national scale any time soon—and that’s actually a good thing. It’s normal for house prices to rise gradually over time . . .”

That’s why even in the select areas where prices have dropped slightly this year, the decline is expected to be temporary. According to that same quarterly Fannie Mae survey mentioned above, 85% of the experts say the markets that are seeing mild declines right now will return to positive price growth before the end of 2027.

The main takeaway? This isn’t a crash. And prices aren’t expected to fall nationally. If anything, the few areas experiencing declines are expected to rebound in the next year or so.

Bottom Line

It’s easy to get caught up in headlines that make it sound like something big is about to happen. But don’t be fooled. The housing market isn’t crashing. It’s just shifting.

The key is understanding what’s actually happening in your market, so you can make the right move for you. Connect with a real estate agent if you want the local perspective.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida

The Remodel You’ve Been Dreaming About May Be Closer Than You Think

The Remodel You’ve Been Dreaming About May Be Closer Than You Think Simplifying The Market

That kitchen you’ve been mentally redesigning…

The bathroom that really needs a refresh…

Or the outdoor space you keep saying you’ll get to someday…

What if you already have what you need to finally make it happen? Because a growing number of homeowners are realizing just that.

Homeowners are expected to spend over $522 billion on home improvements by the end of 2026 – and they’re not draining their savings accounts to get it done. Many are using their home equity.

And if you’ve owned your home for 10+ years, there’s a chance you could use your equity to fund some home upgrades too. Let’s break down what you need to know first.

What Is Equity? And How Does It Help?

Equity is the difference between what your house is worth and what you owe on your mortgage.

And according to Cotality, the average homeowner has about $313,000 worth of equity today. That’s more than enough to finally knock some projects off your list. And more people are realizing they can use that to give their home a little TLC.

Research coming out of Meridian Link says home improvements are the top thing people are using their equity for today.

Top Motivations for Equity-Based Borrowing:

  • Funding home improvements (45%)
  • Using it to pay down other debts / debt consolidation (16%)
  • Investing in other properties (16%)

Maybe it makes sense for you to do the same. But here’s what’s important. Just because you can use your equity doesn’t mean you have to. It also doesn’t mean every project makes sense.

What Projects Are Actually Worth It?

If you’re going to go this route, you’ll want to focus on upgrades that actually pay off. A good renovation should be something that improves the value of your home. Because, even if you’re not planning to sell soon, you want to make sure you’re setting yourself up for success when you do.

And an agent is the best resource as you weigh your options. They know what other homeowners are doing and what buyers in your area like. And that can be really helpful as you narrow down your project list. As the National Association of Realtors (NAR) puts it:

“Being able to help sellers prioritize home improvements and maximize their net on the sale is a key value real estate agents offer.”

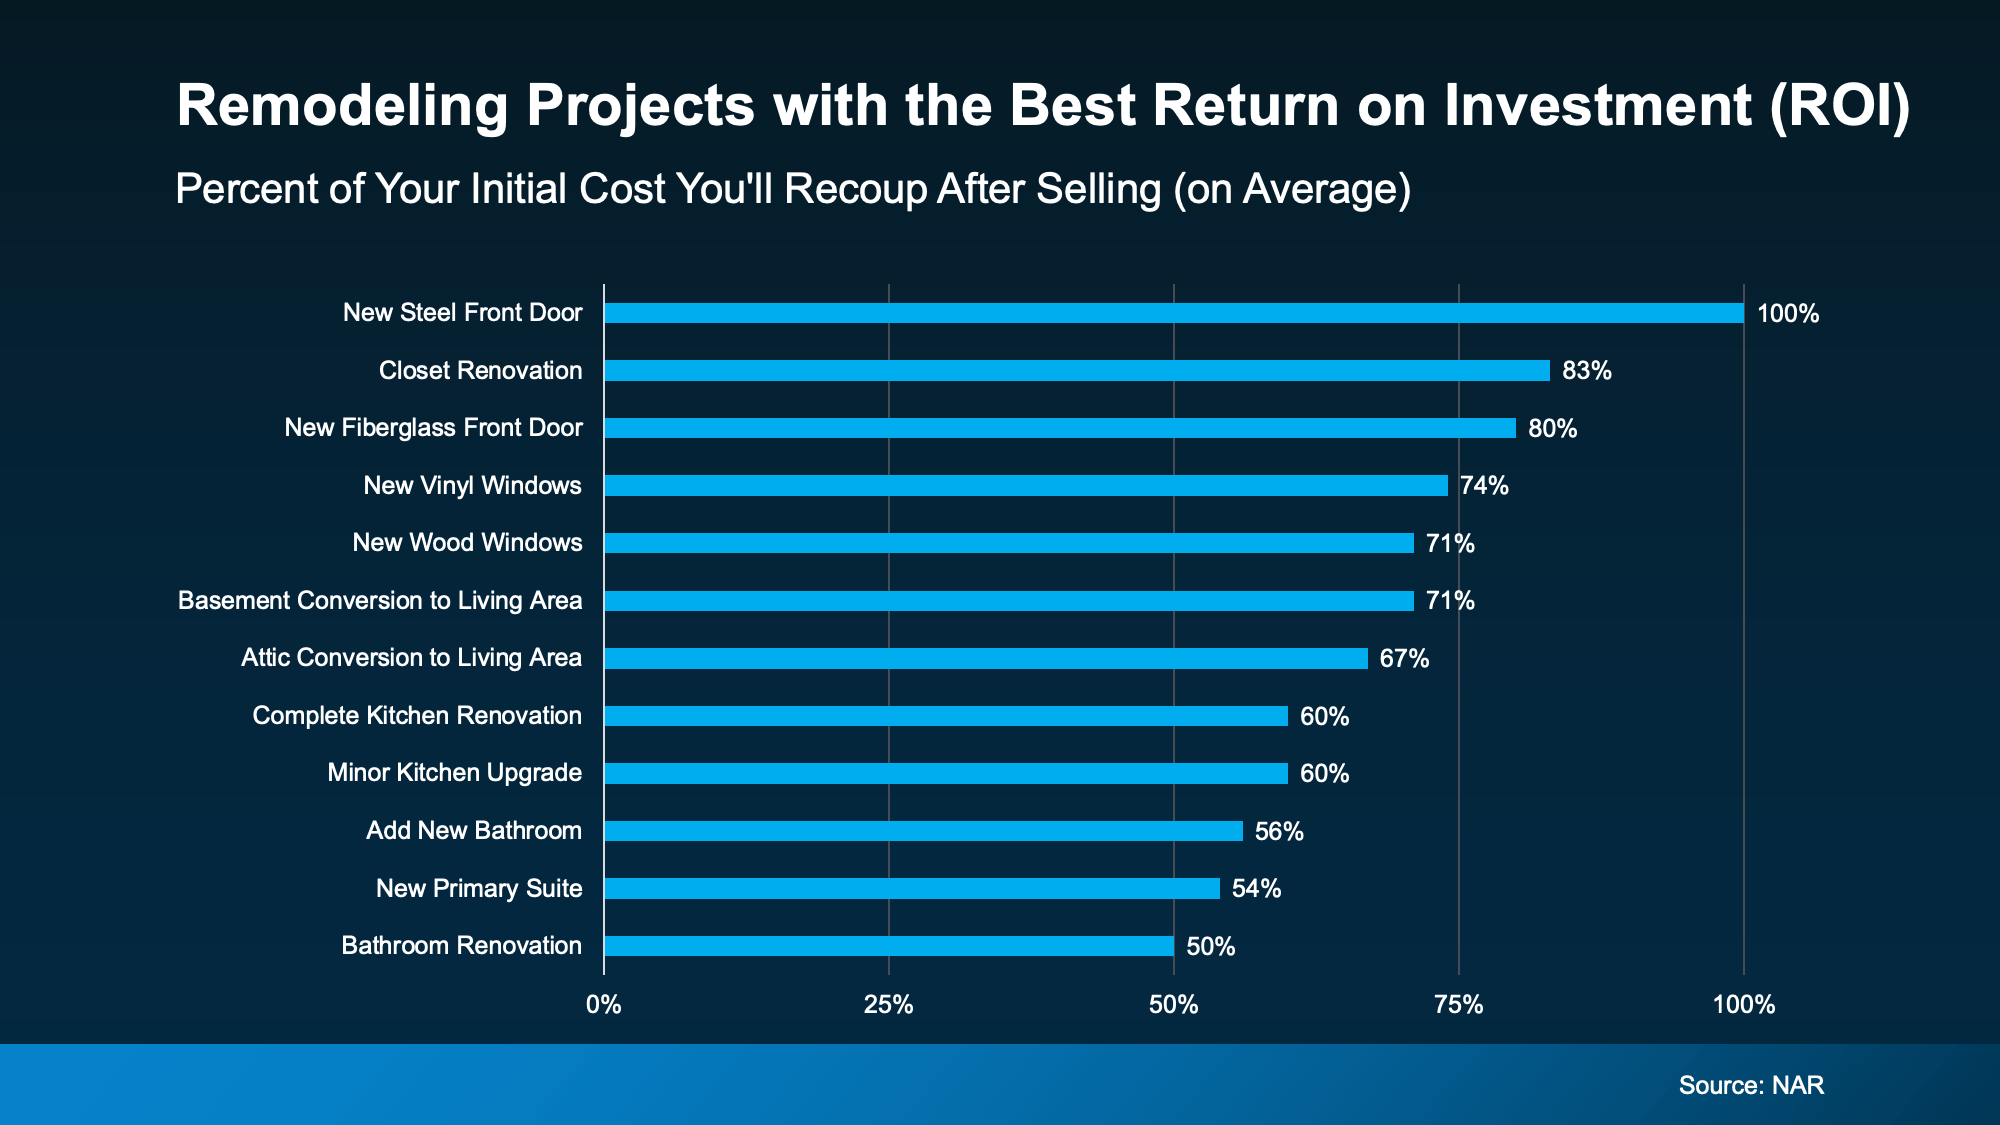
Here’s a quick rundown of the projects with the best potential to recoup your costs according to NAR (see graph below). While it’s a good starting point, just remember it can’t match the expertise an agent can provide.

a graph of a number of blue and white barsAs you can see, there’s a wide range of projects on that list. Yes, some are bigger-ticket items, like kitchens or baths. But others are smaller updates with surprisingly strong ROI.

A new front door is a great project. But it’s not something to use your equity for. But revamping your kitchen? That’s where your equity can come in and lighten the load.

Where To Go from Here

Whether the project you’ve been thinking about is on this list or not, chat with an agent to make sure it’s worth the time, money, and effort before calling in any contractors.

Because the goal isn’t to do everything, it’s to invest where it counts.

And if you want to use your equity to get one of the bigger projects done, meet with a financial advisor too. Because you’ll want to make sure you’ll maintain a good loan-to-value (LTV) threshold even after using your equity. That way you have all the information you need to make your decision.

Bottom Line

Whether you’re selling next year or just giving your house some TLC, the right home improvements today can set you up for success tomorrow. And the best part? Your equity may be the key to making it happen.

What’s one upgrade you’ve been thinking about – and wondering if it’s worth it?

Have a quick conversation with an agent to find out if it’s the right decision for your home.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida

The #1 Reason Buyers Walk Away (And How To Get Ahead of It)

The #1 Reason Buyers Walk Away (And How To Get Ahead of It) Simplifying The Market

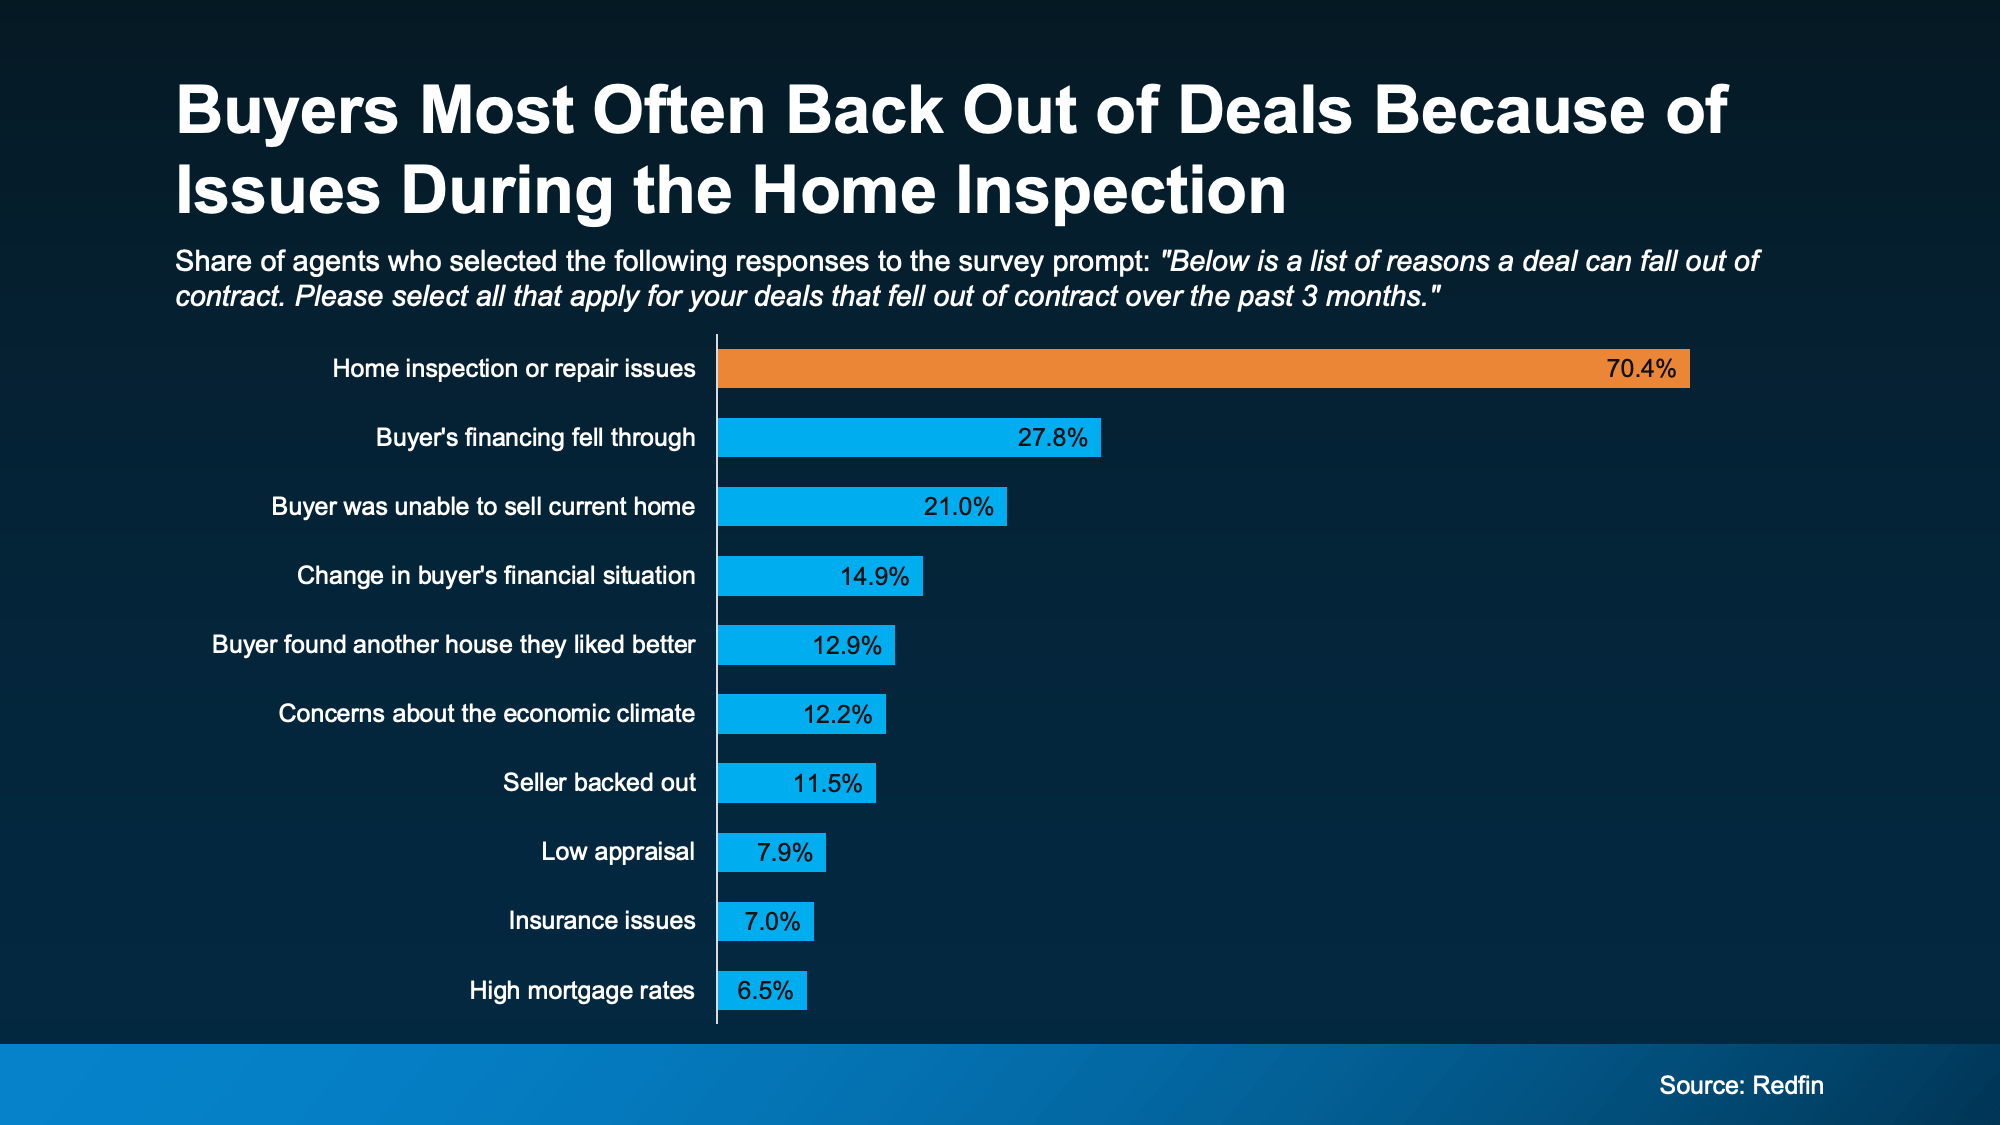
You may have seen headlines on social saying the number of buyers backing out of their contracts is on the rise – and has recently reached a high not seen since 2017. That can sound intimidating. But it varies a lot by market.

And here’s the key thing to understand if you want to sell. A lot of the time, there’s one common cause. And it’s something you can actually control.

Here’s what you can do to get ahead of the biggest dealbreaker before it ever becomes a problem.

The Top Dealbreaker: Issues That Pop Up During the Inspection

A Redfin survey shows over 70% of recently cancelled contracts happened because of issues during the home inspection (see graph below): 

a screenshot of a surveyAnd that makes sense. Because today’s buyers have something they didn’t have a couple of years ago: options.

Why Fixing Things Before You List Matters More Today

A few years back, when buyers felt rushed or boxed in due to the limited number of homes for sale, they were more willing to overlook issues.

But in today’s market, skipping essential repairs is one of the fastest ways to lose a deal.

Now that there are more homes to choose from, buyers can be more selective. If a house feels risky, outdated, or like it’s hiding expensive surprises, they’re a lot more likely to walk away. So, what do you have to fix? Just ask an agent.

How Your Agent Can Help Give You the Edge

A local agent will be able to walk through your house and offer advice on what to tackle based on your specific home, your market, and what buyers are prioritizing in your area. They’ll also have first-hand knowledge about some of the biggest turnoffs for buyers today. And you can use that expertise to prevent future headaches.

For example, according to Zillow, these are some of the issues buyers will care the most about:

  • Roof leaks or damage: sagging, leaking, etc.
  • Plumbing problems: standing water, leaks, water damage, etc.
  • Electrical concerns: outdated or exposed wiring, missing GFCI outlets, etc.
  • HVAC issues: non-functioning units
  • Pest or insect damage: termite colonies, etc.
  • Hazardous materials: lead, mold, asbestos, etc.
  • Safety/code violations: missing smoke detectors, windows stuck closed, etc.
  • Structural problems: cracks in the foundation, sagging floors, etc.


Odds are not all of this even applies to your house. Maybe only 1-2 things do. Or maybe none of them do. It just depends. But an agent will have the tools and resources to help you figure it out and stay one step ahead.

The Benefits of a Pre-Listing Inspection

To buyers, these aren’t cosmetic issues. They’re trust issues. And that’s what you need to watch out for today. Once buyers start wondering “what else might be wrong,” it’s hard to recover momentum.

That’s why some agents are even recommending a pre-listing inspection as a sneak peek into what buyers will see on their own inspection. With that insight, you can:

  • Fix concerns before you list, or disclose issues upfront
  • Avoid having to respond or negotiate under pressure
  • Stop scrambling to find contractors with availability before your closing date

But remember, you don’t have to fix everything. You just have to be strategic about what you do tackle, so you and your buyer aren’t caught off guard.

And that’s why you need an agent who can:

  • Decide if a pre-listing inspection is worth it where you live
  • Recommend a trusted inspector (if you decide to get one)
  • Look at the results with you to identify true dealbreakers in your market
  • Help you decide what to fix or what to credit
  • Make sure you avoid over-spending or under-preparing

Bottom Line

One of the biggest dealbreakers for buyers today is inspection issues – and that’s something you can control. You just need to be proactive about high-impact repairs before you list.

If you want help figuring out where to focus, connect with an agent.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
One Key Sign We’re Not Headed for a Wave of Foreclosures

One Key Sign We’re Not Headed for a Wave of Foreclosures Simplifying The Market

Foreclosures are ticking up. And that may make your mind jump straight to thoughts of 2008 – specifically to what happened to the market during the housing crash. So, let’s do exactly what your brain already wants to do, and see if there’s any connection there.

The simple truth is foreclosure filings are rising. But they’re nowhere near crisis levels. And that’s not where they’re headed either. Here’s why.

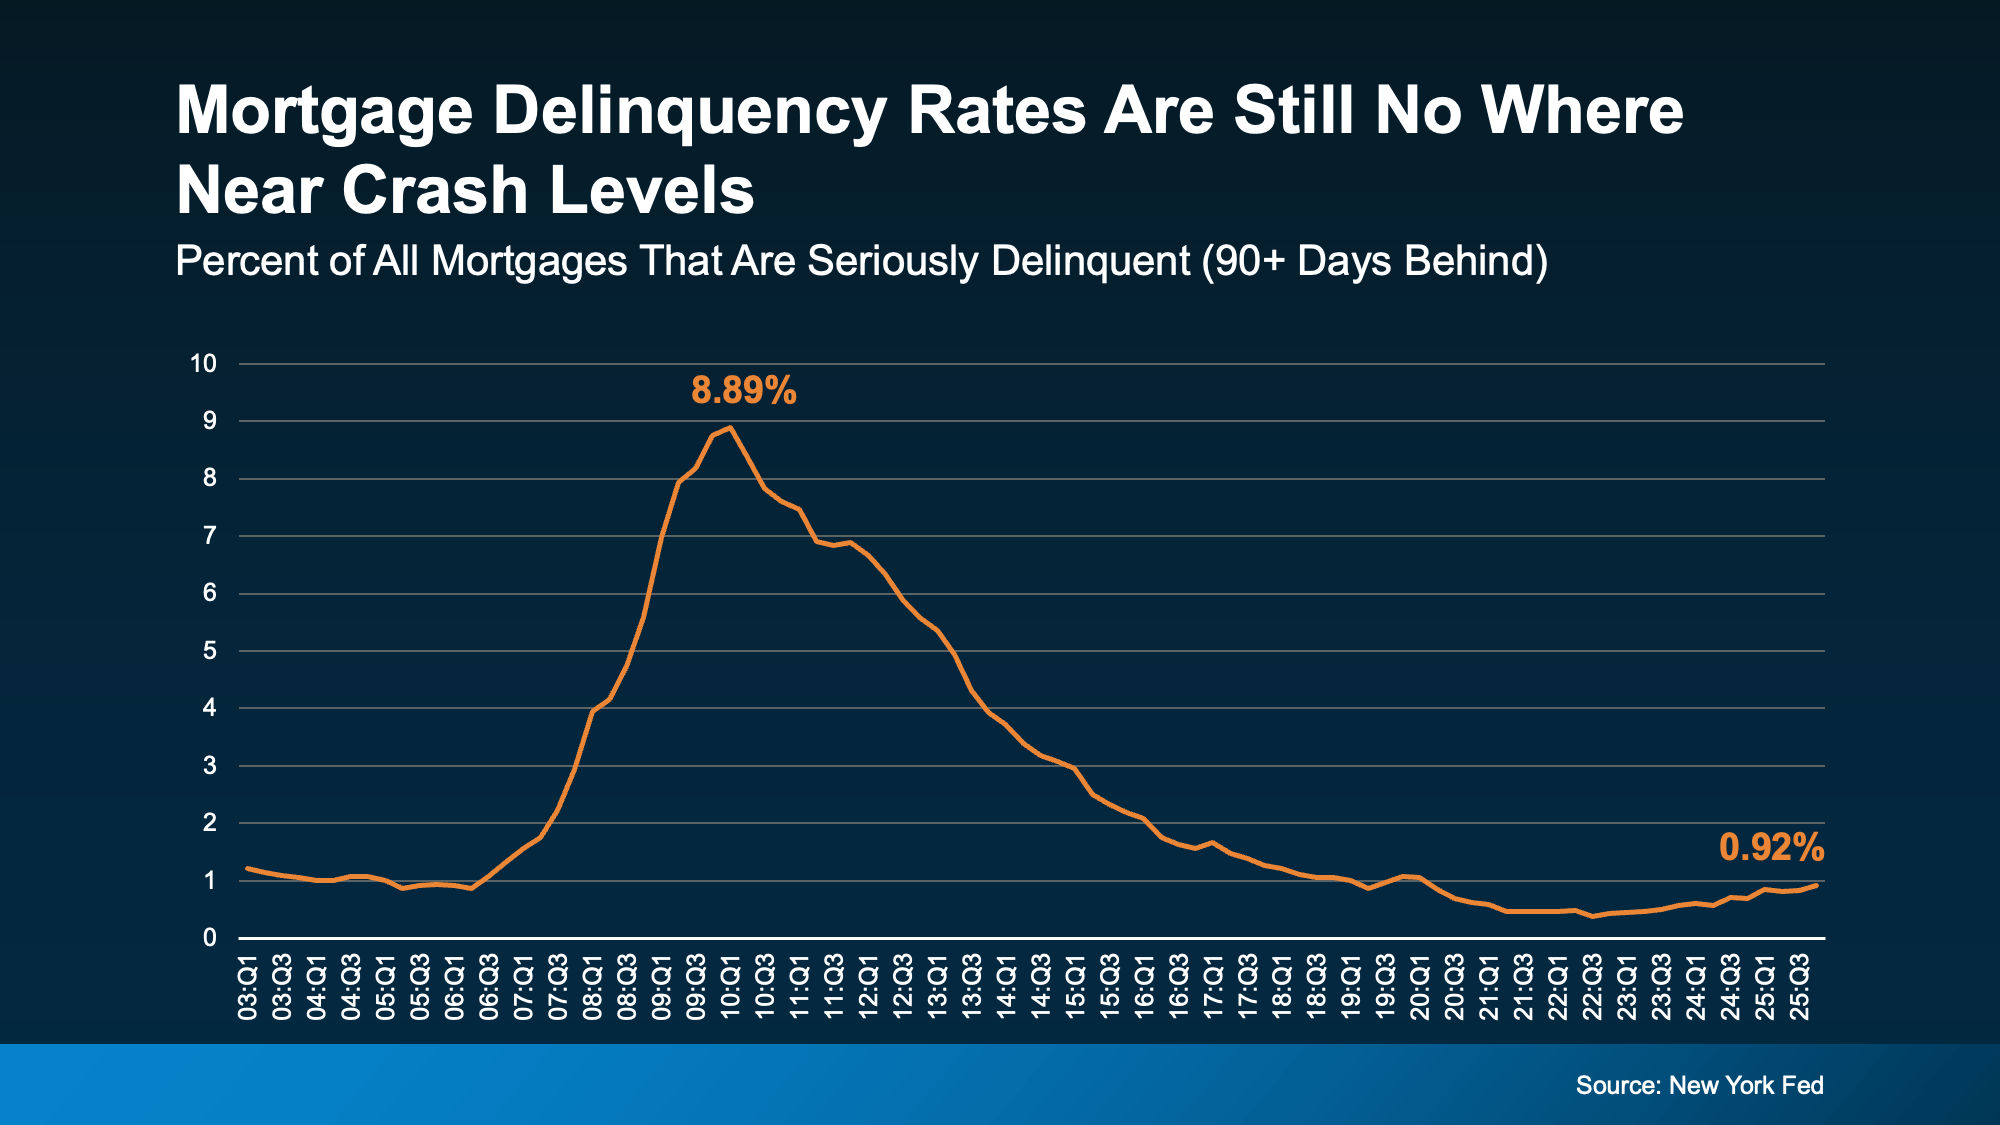
Take a look at serious delinquencies – loans where the homeowner is more than 90 days late on their mortgage payments.

While those have increased slightly, data from the New York Fed shows they still remain low. And they aren’t anywhere close to levels seen when the market crashed (see graph below):

a graph with numbers and a lineRight now, about 1% of mortgages are seriously delinquent. That’s only 1 in 100.

In the years around the crash, they were up around 9%. That’s 1 in 11.

That’s a big difference.

And it’s important to remember not all delinquencies even become foreclosure filings. Some homeowners who are falling behind will work out repayment plans with their banks and lenders because banks don’t want to see a wave of foreclosures either.

That’s why foreclosure numbers are even lower than delinquencies. ATTOM shows only 0.3% of all homes are currently going through a foreclosure filing. And those won’t even all go to a full foreclosure. That’s not a wave. That’s a ripple at most.

If People Are Falling Behind on Payments, Why Aren’t There Even More Foreclosures?

And maybe you’re wondering, if people are struggling financially, why aren’t there more foreclosures? Here’s the easiest way to answer that.

When households feel financial pressure, they tend to prioritize their mortgage payment above almost everything else. Because the last thing they want to lose is their home.

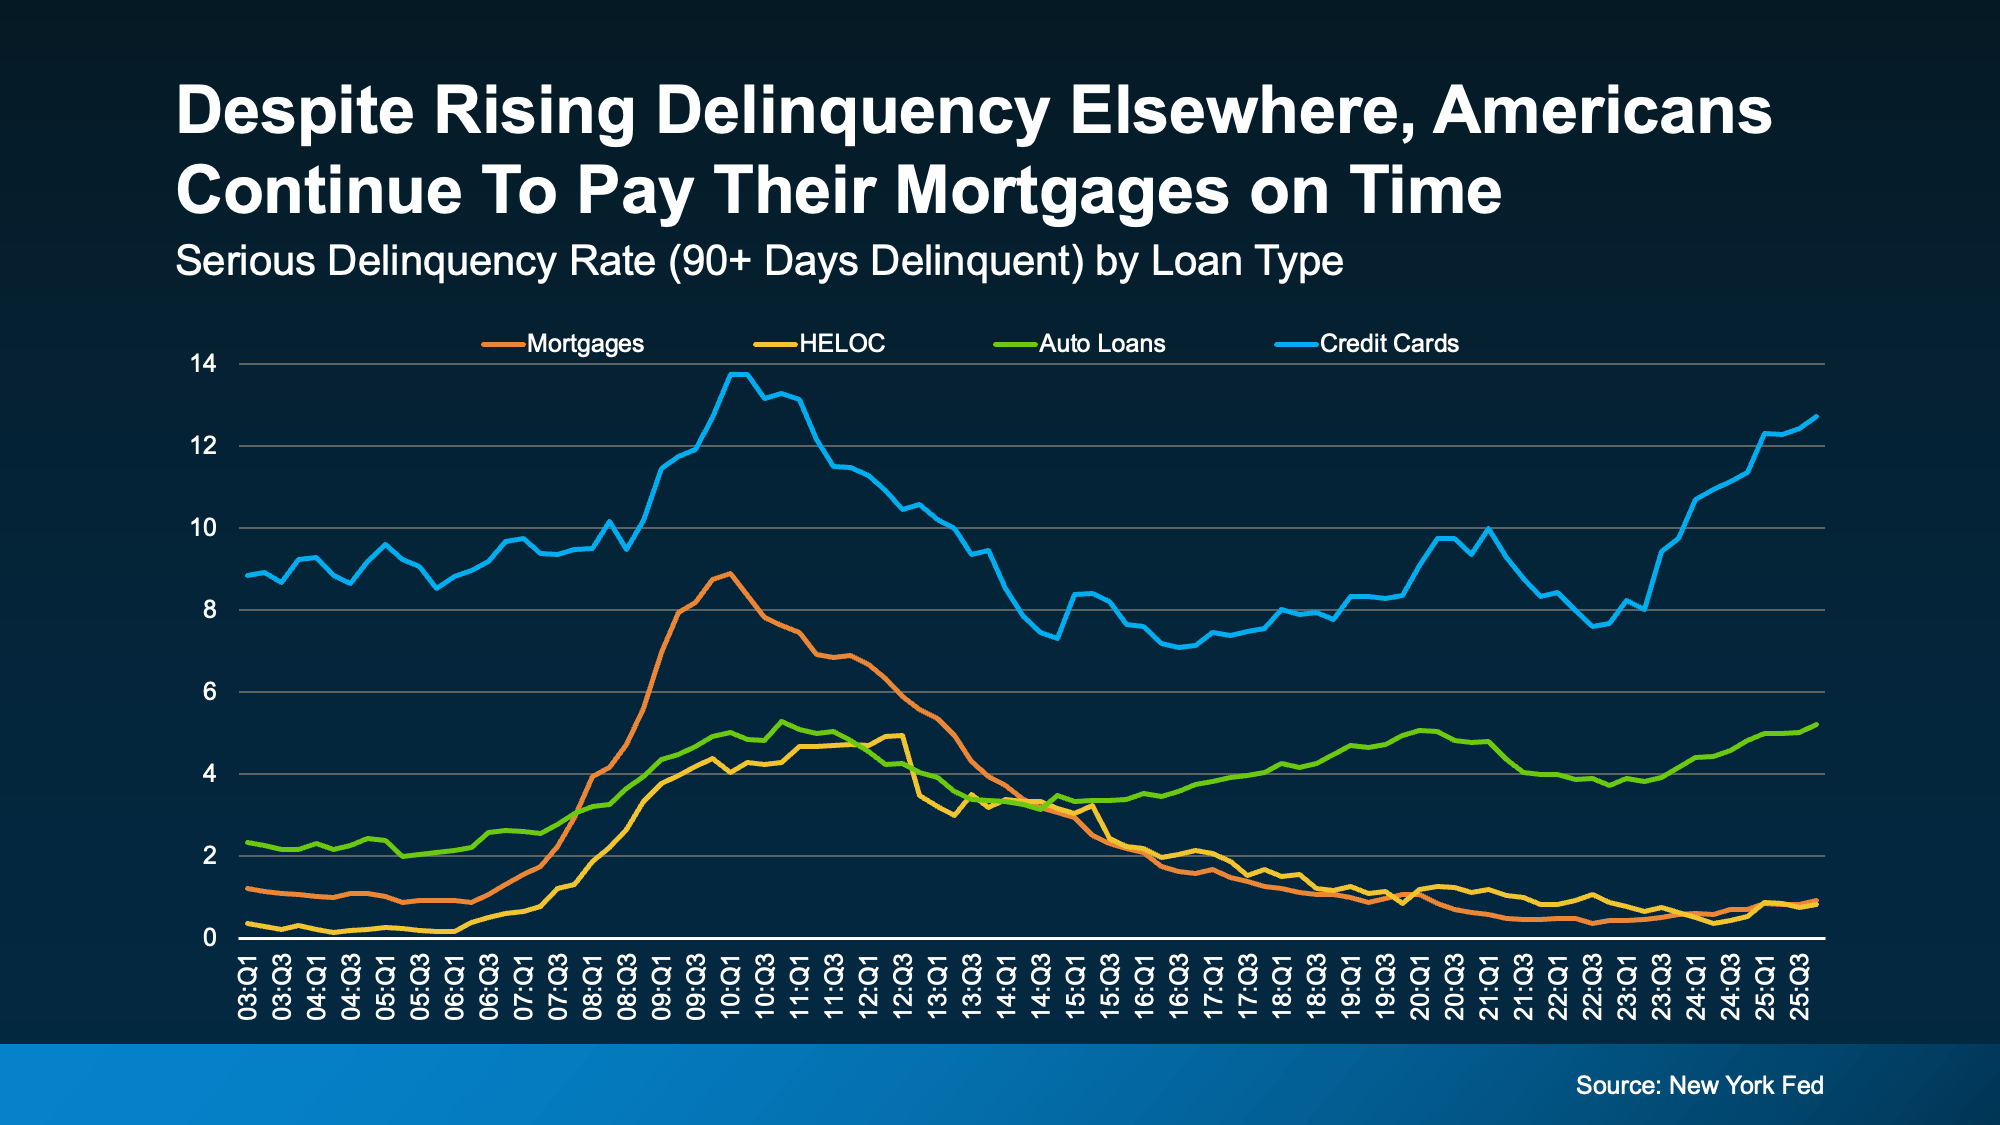
Data from the New York Fed shows serious delinquencies have risen more for credit cards and auto loans (the blue and green lines). But mortgage delinquencies and home equity lines of credit (borrowing against the value of your home) aren’t seeing the same big uptick (the yellow and orange lines). They’re a lot more stable overall.

In other words, people may fall behind on other debts, but they fight hard to keep their homes. And, in today’s housing market, they’re also in a strong equity position to do so.

Home Equity Changes Everything

Many people have built significant equity over the past several years. And that creates options. As Daren Blomquist, VP of Market Economics at Auction.com, explains:

“Distressed homeowners… many times they still have equity in their homes. There’s an opportunity for them to sell that home, avoid foreclosure, and walk away with equity.”

That’s a major difference from 2008. Back then, many homeowners owed more than their homes were worth. And selling wasn’t an easy solution. Today, for many people, it is. And even in situations where equity isn’t enough, homeowners are encouraged to contact their loan servicer early to explore alternatives to foreclosure.

Bottom Line

Are foreclosure filings rising slightly? Yes. Are they anywhere near crash territory? No. And homeowners today have far more equity and flexibility than they did during the crash.

If you’re concerned about what you’re seeing in the headlines, the best move isn’t panic, it’s perspective. And the data right now says this isn’t 2008 all over again.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida
If Your House Isn’t Getting Offers, Read This.

If Your House Isn’t Getting Offers, Read This. Simplifying The Market

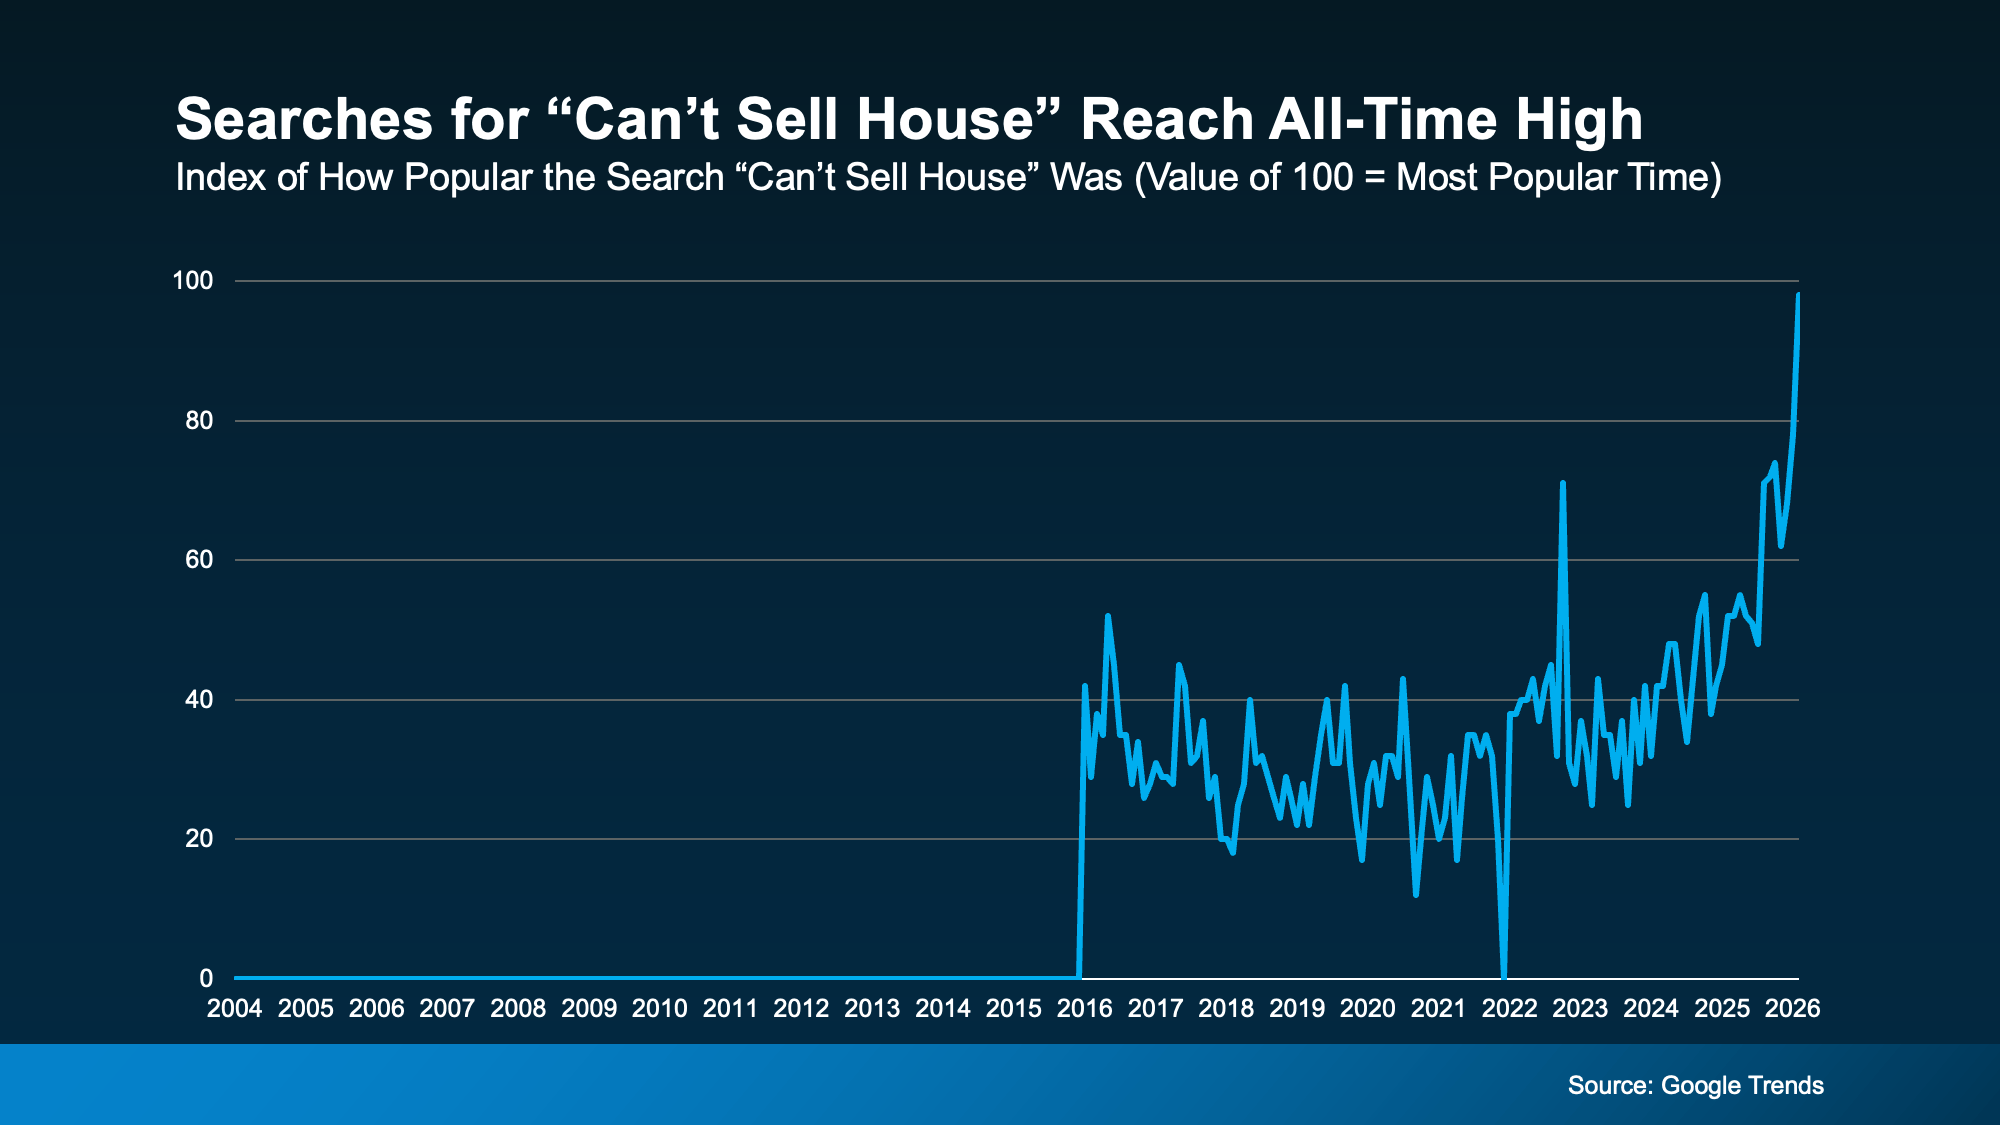
Online searches for “can’t sell house” just hit an all-time high according to Google Trends. So, if your house has been sitting on the market without any bites, you’re not the only one. But it’s also not the end of the road. 

Homes are selling every day, so you can turn this around. You just need to take another look at your approach.

a graph of a house priceIf you’re feeling this pain, know this: an online search engine isn’t where you should go for your answers. It’s much better to talk to your agent. Because a search engine doesn’t know your market or your house. But your agent does.

While a quick search or an AI platform may give you some tips on what to try, only an expert agent can actually diagnosis what’s going on – and how to fix it.

For example, your agent knows most homes that struggle to sell today are usually being held back by one (or more) of these three things.

1. Presentation: Buyers Will Compare Everything

When inventory was tight a few years ago, buyers overlooked imperfections because they had to, or they’d lose out to another bidder. Now? That’s no longer the case.

Today’s buyers scroll through dozens of listings in just minutes. They compare condition, updates, lighting, finishes, layout, and more – all side by side. If your home feels dated, cluttered, or in need of repairs, buyers will notice and it’ll knock your house right off their list of contenders.

This doesn’t mean you need a full renovation. But it does mean first impressions matter again. To compete today, you need curb appeal. Clean spaces. Neutral colors. Professional photos. If there are scuffs on the walls, obvious repairs, or too many outdated features, it could be what’s holding you back.

2. Pricing: If the Price Isn’t Compelling, It’s Not Selling

This is maybe the hardest one to hear, but what your neighbor sold their house for a few years ago isn’t necessarily the same price you’ll get today. As Selma Hepp, Chief Economist at Cotality, says:

“For sellers, the days of pricing aggressively and expecting instant offers are largely over. Homes that are well-priced and well-presented will still sell, but pricing discipline matters more than it did during boom years.”

Buyers are budget-conscious right now. If your home is priced based on outdated expectations instead of current demand, buyers may still look at your house online… but they likely won’t write an offer. Or, they’ll make an offer that you think is too low.

Pricing too high for this market is one of the top things sellers miss the mark on today. And those who aren’t willing to meet the market where it is or entertain offers may feel stuck.

3. Access: If Buyers Can’t See It, They Can’t Buy It

It sounds obvious but limited showing availability can kill your momentum. If your house isn’t easy to see because you’re restricting showings to evenings only, no weekends, or requiring a 24-hour notice, you’re cutting your buyer pool down by more than you may realize. 

And the more friction you create, the fewer buyers walk through the door.

In a market where buyers have more options, the last thing you want to do is give them a reason to skip your house. Availability matters because if no one sees it, no one buys it.

Don’t Let Search Results Decide Your Next Step

When your house isn’t selling, it’s tempting to spiral and wonder if it’s the market or if something’s wrong with your house. But instead of searching for answers online, here’s what to do.

Sit down with your agent and ask three honest questions:

  • What are buyers looking for in today’s market?
  • What feedback are we getting from showings?
  • Why do you think my house hasn’t sold yet?

That conversation will bring a lot more clarity than any search engine results.

Bottom Line

If your listing feels stuck, it’s not a sign you shouldn’t sell. It’s the market giving you feedback. And feedback is powerful when you use it.

Start with a real conversation with a real agent about what’s working and what’s not. Your agent will be able to tell you which small adjustments could totally change the momentum. Because in this market, the sellers who adapt are the ones who move.

#fidelityhomegroup, #floridamortgage, #floridamortgagerates, #mortgageflorida